Tell a chief engineer the yacht does not need maintenance because everything worked last summer.
Then take a respectful step backwards.
Tel: +34 93 665 8596 |
info@spectrum-ifa.com |

By Tom Worthington
This article is published on: 16th November 2026
Tell a chief engineer the yacht does not need maintenance because everything worked last summer.
Then take a respectful step backwards.
Engineers understand that reliability takes attention. So do chefs. A beautifully written menu achieves very little if the refrigeration fails, the delivery is missing and the only remaining vegetable is something nobody can confidently identify.
Yet investments are sometimes expected to look after themselves indefinitely.
The account was opened. The money went in. The paperwork arrived.
Job done.
Until someone asks what it costs, how it is invested or why the “low-risk” portfolio has made their morning considerably more stressful.
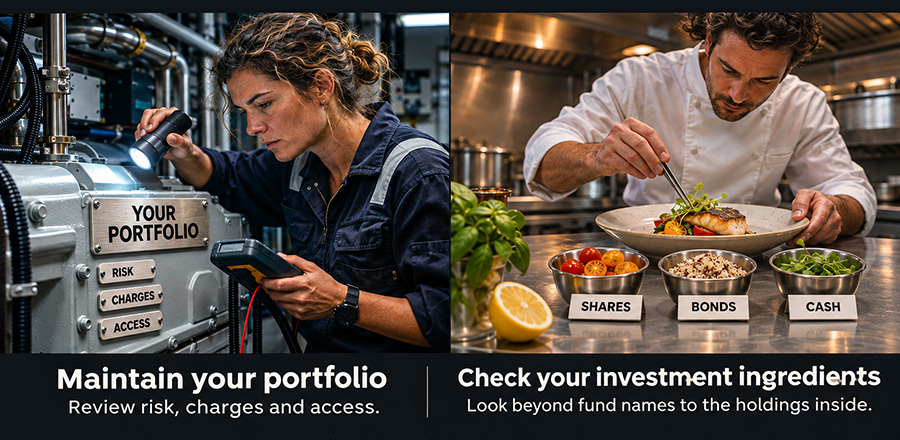
Have a look in the engine room
A polished exterior does not tell you what is happening below decks.
Likewise, a strong investment return tells you only part of the story. I want to understand the holdings, the risks, the charges and any restrictions on accessing the money.
You would not assess an engine solely by its horsepower. Nor would you judge a chef entirely by the photograph of one dessert.
Although, to be fair, a well-positioned chocolate fondant can distract people from quite a lot.
The important questions concern how the investment works and whether it suits the job you need it to do.
Check the ingredients
Owning several funds does not necessarily mean your investments are well diversified.
If they all hold many of the same companies, you may have ordered five dishes containing essentially the same ingredients.
Different garnish. Same chicken.
I want to look through the labels and understand where the risks actually sit. Diversification can spread those risks, although it cannot prevent every loss.
A balanced menu also has to suit the person eating it. The chef’s favourite dish is irrelevant if the guest cannot eat it. An adviser’s enthusiasm for an investment is equally irrelevant if it does not fit the client’s needs.
Imagine a crew member saving for three things: time between contracts, a property deposit and eventual retirement.
Those savings have different jobs.
Money needed soon should not depend on markets being favourable when the bill arrives. Longer-term investments may have more time to recover from falls, provided the risks are appropriate.
The chef would not put tonight’s dinner somewhere it cannot be accessed for five years, even if the storage company offered an impressive projected return.
Accessible reserves matter particularly when leaving a yacht also means losing accommodation and meals. Suddenly, rent, supermarket shopping and electricity become your department.
The first full food shop ashore can be an educational experience. Apparently, the crew fridge was not replenishing itself through maritime magic.
Regular reviews should check progress, costs, risk and changes in your circumstances.
They should not become an excuse to change everything whenever markets wobble.
An engineer does not dismantle a functioning generator because another engineer mentioned a newer one over a beer. A chef does not rewrite the entire menu every time someone posts a photograph of a fashionable potato.
Sometimes an adjustment is sensible. Sometimes leaving a suitable plan alone is the disciplined decision.
A promotion, property purchase, new child or move ashore may be a better reason for a review than today’s dramatic headline.
I also want clients to understand insurance provided through their employment: what it covers, what it excludes and what happens when they leave.
“Probably covered” is an uncomfortable phrase to discover in an emergency.
The captain monitors the passage. The engineer maintains the systems. The chef manages ingredients, timing and resources.
Your finances need that same combination of direction and attention.
Ideally before the warning light comes on. And certainly before somebody suggests putting a piece of tape over it.