
Anyone with a family member who has a disability or complex care needs understands the stress and anxiety involved in meeting their daily requirements, navigating routine life, and simply making it through to tomorrow. It is incredibly challenging, filled with both good days and bad days. Another concern hovering in the back of every carer’s mind is what will happen when they are no longer able to care for their relative.
Viewing posts categorised under: France
Providing for an Adult Child with Complex Needs in France
By Katriona Murray-Platon
This article is published on: 6th November 2026
06.11.26
Every situation is unique. Anyone with a disabled relative knows that their circumstances rarely fit neatly into a specific label, category or list of symptoms. Each individual is unique in their personality and abilities, which may evolve over time. Furthermore, many conditions have only been identified in recent decades, making it difficult to predict how a situation might develop over a lifetime.
Alongside day-to-day care, establishing financial security as early as possible is essential.
The first question to resolve is the relative’s place of residence: are they remaining in your home country while you reside in France? Should something happen to their primary carer or relative, would they want—or be able—to move to or stay in France, given that significant life changes can be particularly difficult for individuals with complex needs to process?
Assuming the disabled individual is a French tax resident, they may be eligible for a disability benefit called the Allocation aux Adultes Handicapés (AAH). This benefit is means-tested. The maximum rate for a single adult with no other resources is currently around €1,000 per month (adjusted periodically). If the individual receives other income, such as a pension or annuity, the AAH payment is reduced accordingly.
Under French tax law, any beneficiary with a qualifying disability—regardless of their relationship to the donor or deceased—is entitled to a specific inheritance and gift tax allowance (abattement handicapé) of €159,325. This tax-free allowance applies to gifts made every 15 years as well as to inheritances.
To qualify, the individual must be unable to engage in remunerated work under normal conditions due to a physical or mental disability (or, if under 18, be unable to receive standard education or vocational training). Unlike certain other state benefits, there is no requirement to prove a specific percentage of disability; however, the condition must exist at the time of the gift or inheritance and be substantiated by an official medical certificate or documentation from a specialist institution.
This €159,325 allowance is cumulative with standard tax-free allowances. For instance, a parent gifting to a disabled child can combine it with the standard parent-child allowance of €100,000, plus the tax-free gift allowance of €31,865 for cash transfers (donations de sommes d’argent), provided the relevant age criteria are met.
Where a relative with a disability is able to work and live independently, that autonomy is a wonderful milestone. However, where independent living is not feasible, French law provides several structured ways to ensure long-term care and residence within the family framework:
- Tutelle: A strict legal protection measure ordered by the courts for individuals whose mental or physical capacities are substantially impaired. The adult is represented by a tuteur (guardian), who oversees the protection of the person, their assets, or both. An application is submitted to the Juge des contentieux de la protection des tutelles at the local court (Tribunal judiciaire), accompanied by a detailed medical report from an approved specialist doctor. The judge conducts a hearing, listening to the vulnerable adult (where medically authorised) as well as the proposed guardian, family members, and attending doctors. The court generally has up to one year to issue a decision.
- Curatelle: An assistance measure designed for adults who require guidance in day-to-day management and major legal acts without completely depriving them of their rights. The curateur assists rather than completely replaces the individual. It is used when a lighter measure, such as sauvegarde de justice, is insufficient.
- Sauvegarde de Justice: A temporary or emergency legal protection measure. It applies when an adult requires immediate protection or representation due to a sudden or short-term decline in their physical or mental faculties (whether from illness, accident, or age). It safeguards the individual against reckless financial expenditure or exploitation until a longer-term measure (such as tutelle or curatelle) can be put in place.
- Habilitation Familiale: A legal measure allowing a designated family member to represent or assist a relative who cannot express their wishes or manage daily tasks. It can be ordered only when needed and where other measures do not provide sufficient protection. It can be general or limited to specific acts.
Until a child reaches 18, parents act as their legal representatives. Once the child turns 18, parents or family members must apply to the court to put one of these protection measures in place. Parents are usually appointed as guardians, but arranging an appropriate framework (such as habilitation familiale) for the long term is essential to avoid court disruption later.
Trusts do not exist within the French legal system. However, French tax and legal authorities recognise foreign trusts, provided the necessary annual tax filings and disclosures are made. If a settlor, trustee, or beneficiary of a foreign trust resides in France, strict annual reporting obligations apply.
Because French real estate cannot be placed directly into a trust, alternative tools are required to secure housing and income for a relative with complex needs:
- Assurance-Vie with Split Ownership (Démembrement): An assurance-vie policy can be structured with a démembrement de la clause bénéficiaire. This allows the disabled individual to receive income (usufruct) during their lifetime, while the bare ownership (nue-propriété) of the underlying capital is held by a designated trustee or family member.
- Inalienability Clauses (Clause d’inaliénabilité): You can stipulate in a will or deed of gift that property passed to a vulnerable relative cannot be sold, mortgaged, or transferred during their lifetime, ensuring they maintain secure accommodation.
- Right of Return (Droit de retour conventionnel): When gifting property to a child during your lifetime, a clause can ensure that if the child predeceases the parents without issue, the asset reverts directly to the parents rather than passing into their estate.
Inheritance planning is important for every family, but when supporting a child or relative with complex care needs, early professional advice is essential. Combining French legal protection measures, tax allowances, and tailored financial solutions ensures your relative continues to receive the emotional, practical, and financial security they need throughout their life.
Financial update France – November 2026
By Katriona Murray-Platon
This article is published on: 4th November 2026
04.11.26
As the end of the year approaches, potential tax changes for 2027 have taken centre stage following both the UK Autumn Budget and the publication of the French Draft Finance Law (Projet de Loi de Finances) in October.
Whilst most of the UK Autumn Budget proposals do not directly impact French-resident British nationals, the confirmation that UK pensions will be included in estate values for UK Inheritance Tax (IHT) purposes from April 2027 remains significant. This proposal has prompted those with larger pension pots to assess whether it is more advantageous to leave their pensions untouched or to draw down funds under France’s favourable 7.5% lump-sum pension tax regime (prelevement forfaitaire libératoire).
Additionally, the abolition of the restrictive two-year rule—under which pension death benefits were subject to extra tax—has been widely welcomed, given the expected administrative complexity of managing estates containing pensions after April 2027.
Geopolitical uncertainty and global economic pressures continue to influence inflation levels worldwide. While the French government originally intended to freeze income tax brackets last year before increasing them by 0.9%, the new Draft Finance Law proposes indexing tax bands by 2.1% for income earned in 2026 (taxed in 2027) to align with inflation. Taxpayers whose income has remained unchanged over the past year should see a slight reduction in their tax liability.
The proposed tax bands for 2026 income are as follows:
| Income | Tax Rate |
| Under €11,844 | 0% |
| Between €11,845 and €30,200 | 11% |
| Between €30,201 and €86,353 | 30% |
| Between €86,354 and €185,737 | 41% |
| Over €185,737 | 45% |
Pensioners may face higher taxation next year. The 10% tax abatement ceiling on pension income is set to be reduced from €4,439 to €3,000. Under these changes, households receiving more than €2,500 of pension income per month will find themselves subject to income tax. Child support payments and disability benefits will remain unaffected by this amendment.
The Draft Finance Law proposes a temporary increase in the tax-free gift allowance for parents under 80 gifting to adult children, grandchildren, great-grandchildren, nieces, or nephews. Between 1 January 2027 and 30 June 2027, the usual tax-free allowance of €31,865 will be raised to €50,000. Amounts above this allowance up to €100,000 would benefit from a reduced tax rate of just 6%. It remains to be seen which of these proposals will make it into the final Finance Law for 2027.
The deadline to amend your 2025 tax return online is 30 November. In previous years, the online correction portal remained open until the end of the calendar year, but the tax authorities have brought the cutoff date forward to the end of November.
If you hold French bank deposit accounts, savings accounts (excluding tax-free accounts like the Livret A, LDDS, or Livret Jeune), or bonds, and your Taxable Income (Revenu Fiscal de Référence – RFR) for 2024 was under €25,000 (single) or €50,000 (couple), you have until 30 November 2026 to notify your bank. Doing so prevents them from automatically withholding the 12.8% advance income tax on your interest in 2027.
For dividend income from investment accounts (compte-titres), the 2024 RFR thresholds are higher: €50,000 for single taxpayers and €75,000 for couples. Opting out of upfront withholding is particularly beneficial if your overall income falls into the 0% or 11% tax brackets. You can use the official French tax administration model letter here.
Global equity markets continue to demonstrate resilience despite softer sentiment surrounding artificial intelligence (AI) valuations. While political events such as the US mid-term elections may generate short-term volatility, fundamental drivers—including economic growth, corporate earnings, underlying AI capital expenditure, inflation trends, and central bank interest rate policies—remain the dominant market catalysts.With colder weather arriving and more time spent indoors, now is an ideal time to review your financial strategy. Please feel free to get in touch to discuss your wealth planning, tax strategies, and priorities for the year ahead.
French financial update October 2026
By Katriona Murray-Platon
This article is published on: 5th October 2026
05.10.26
After a very long and hot Summer, it looks like Autumn is finally here. With businesses in full swing after the summer, there have been some interesting financial developments.
One of the products we advise our clients to invest in when moving to France is an assurance vie. Its popularity is clear and the amount invested in assurance vies has steadily increased since they were created 40 years ago, reaching € 2162 billion in June 2026 (a 6% increase from last year).
By the end of 2025, over half of French household savings were invested in assurance vies – far more than in savings accounts such as the Livret A or LDDS.
This is hardly surprising given the strict limits of these accounts on both the capital (€22,950 for a Livret A and €12,000 for a LDDS) and the fact that savers can only have one of these accounts each, whereas there is no limit to the number of assurance vies a person can have or on the amount invested. If the assurance vie is set up before age 70, the IHT allowance is €152,500 per beneficiary per policy holder (having multiple assurance vies does not increase this amount). According to a 2025 report from the federation France Assureurs, 46% of savers chose this investment for inheritance planning and 44% as their preferred method of saving money.
Average mortgage rates in France have increased since September, currently sitting at around 3.5% depending on the length of the loan. This is due to the fact that the French state’s 10-year borrowing rate has reached 4.2%, its highest level since 2004, and the rise in inflation which increased to 2.4% in August, from 2.1% in July, and 1.8% in June.
The European Central Bank also increased its rates by 0.25 points on 10th September with more increases expected by the end of the year.
Furnished rental property owners using Airbnb under the micro-BIC regime face tighter margins. For “non classé” properties it will be more difficult to remain under the €15,000 threshold. Under the Le Meur law (and contrary to the other thresholds for other types of rental), this threshold has not been adjusted to take into consideration the rise in inflation. Furthermore, from 13th October AirBnB’s pricing policy will change such that the rate of 15% will be paid by the host (rather than being split with the guest). For example, for a rental at €100 per night, instead of receiving €97, the host will only receive €84,50 whereas the guest will pay €100 instead of €115. AirBnB hosts should therefore adjust their prices ahead of this deadline and be aware of the likely impact on their taxable income. This will not affect those that are already under the ‘reel’ or costs-based system.
The Taxe Foncière must be paid by 15th October (20th October for online payments). If you pay your Taxe Foncière in one go in October, it will be taken automatically on 15th October.
If you already pay monthly then the payment on 15th October will be the same as the previous payments and the payment on 15th November will be the balance due for any increases.
Taxe Foncière must be paid by the owner of the property as at 1st January. If you have purchased a property during the year, the notaire will have split the amount pro-rata with the seller meaning that the Taxe Foncière bill won’t appear in your account until next year. If you sold a property in 2026, this will be the last time you pay Taxe Foncière for that property.
On a brighter economic note, both the US and Eurozone economies are performing well. In the US the flash composite Purchasing Managers’ Index (PMI) hit 58.4 this month (up from 56.0 in August)—the fastest pace of expansion since 2015 outside of the post-lockdown reopening surge, with both manufacturing and services performing strongly. In Europe, S&P Global’s composite PMI rose to 53.1 in September 2026 (up from 52.0 in August), marking three consecutive months of accelerating business activity and reaching a three-and-a-half-year high. Notably, Germany expanded for a third straight month, and France returned to economic growth for the first time in 10 months. While new orders and employment are rising, inflationary pressures have intensified slightly (with input and output prices rising at their fastest rates in four months), and business confidence remains relatively subdued.
After a quieter summer, it has been wonderful to reconnect with clients and contacts I spoke with earlier in the year. If you would like to discuss your personal financial situation or planning goals, please get in touch to arrange a meeting.
The Trust Recession
By Peter Brooke
This article is published on: 14th September 2026
14.09.26
My wife, Chris, and I were having one of those meandering conversations recently— when she said something that’s been sitting with me ever since: “Do you think we’re in a trust recession?” She’s right, and once you start looking for it, you can’t stop seeing it.
Politicians treating inconvenient facts as just another opinion to argue with. Long-standing science backed issues dismissed despite the evidence of one climate shock after another. Deadly measles cases back to record levels just as trust in real data and expertise has quietly worn away.
Algorithms that don’t show you the truth, but more of whatever you already believe, until “the world is flat” starts to feel like a reasonable position to the person living inside that feed. None of this is exactly hidden any more. It’s just out in the open, and it’s exhausting.
I recently wrote, in The Intelligence Question, about why a human still needs to be in the loop even as AI reshapes financial planning.
It assumed something I want to go back and examine further:
“That you know which human to trust with that loop in the first place.”
Because this “trust recession” isn’t stopping at politics and social media. It’s already sitting inside financial services, quietly, and I’ve watched it play out over the years with clients — smart, successful, careful people who trusted very well-known financial institutions simply because they were well known, and found out later that “well known” isn’t the same as “on your side.”
So this isn’t really a piece about who you trust with your money. It’s about who you trust with your future.
Trust isn’t just a feeling, it’s an equation
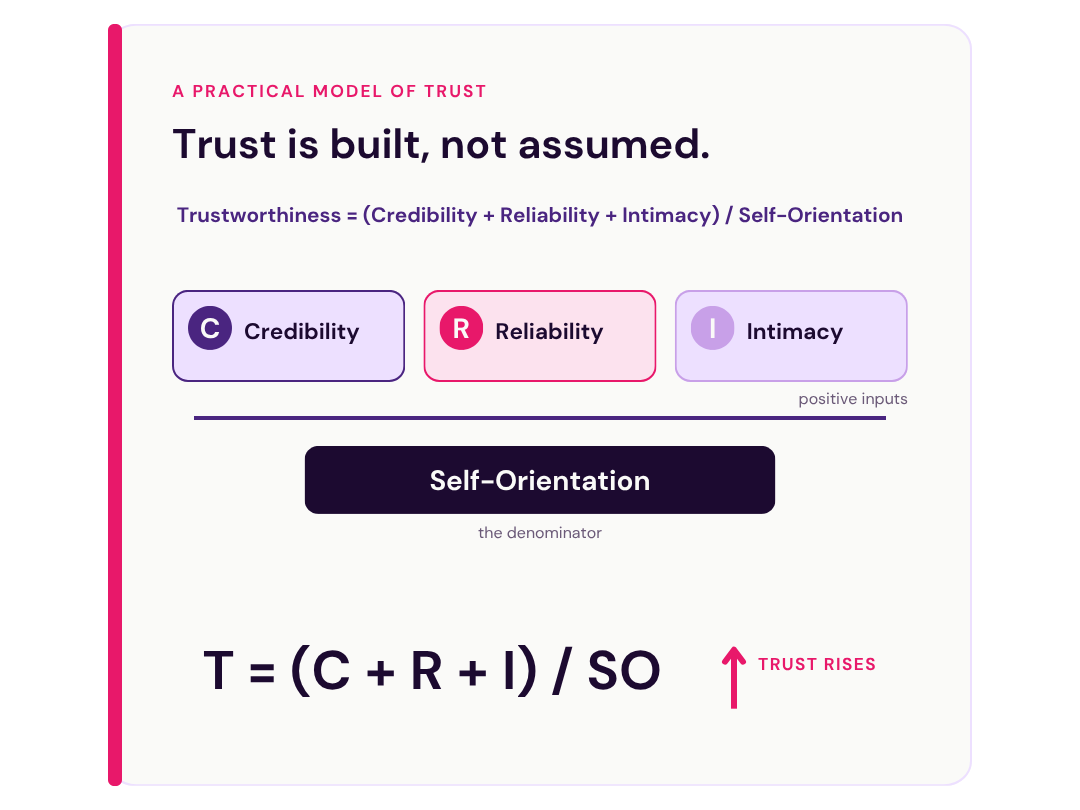
In 2000, in a book called The Trusted Advisor, Charles H. Green and his co-authors put a number on something that usually just feels like instinct. Their formula, still the cornerstone of Trusted Advisor Associates’ work is this:
-
Credibility: can I be believed — do I actually know what I’m talking about?
-
Reliability: do I do what I say I’ll do, when I say I’ll do it?
-
Intimacy: are you comfortable being honest with me, even about the things you don’t tell anyone else?
-
Self-orientation — the one that quietly challenges the other three — is whether I’m doing this for you, or for me.
It’s worth taking that last one seriously: the largest meta-analysis of human trust ever conducted — more than 300 studies, pulled together in 2023 — found transparency to be one of the strongest single predictors of whether someone is seen as trustworthy at all.
At Spectrum, we run this test too, by the way, before any fund manager, platform or provider gets anywhere near your money — regulation, transparency, track record, process!
Same four principles, just pointed at the people and companies we choose to work with.
Credibility: the one where questions matter more than answers
Anyone can claim to be credible — that’s exactly the trouble with a trust recession, self-declared expertise is cheap.
What actually proves it is different: whether you catch the thing nobody thought to ask about. A couple I was introduced to came to me with what looked like a straightforward question about selling a UK property one of them had owned for decades. Buried in the conversation was a detail neither thought was relevant: they’d married in France the year before the sale — which changed which country had the right to tax it, and by how much, eventually worth a six-figure sum in tax savings. Nobody asked me that question; I saw the connection because I’ve spent over twenty years looking out for exactly this kind of thing. That’s not something you can prompt your way into with AI.
Credibility isn’t just about any one story like this — it’s whether that pattern holds up, case after case, including the times I tell you plainly that I don’t know something and need to go and find out.
Reliability: the one I’m still working on
Reliability isn’t glamorous, and if I’m honest, it’s the one of these four I’d most like to get better at. I’m a human, not a system — I can’t promise to be perfect at it and when I do make mistakes I will endeavour to “own them” and put things right as efficiently as possible.
Reliability is the admin done properly and on time: fund switches processed without you having to chase them, withdrawal requests that don’t sit in a drawer, anti-money-laundering checks completed without three reminder emails. No drama, just doing the job properly, every time — and it’s precisely where I’m starting to use things like AI to try and stay on top of an ever-growing to-do list, rather than pretending it doesn’t grow.
What this technology hasn’t reached, and I don’t think it will any time soon, is the human part: knowing that a French wedding mattered to a British tax bill, or simply being the one who picks up the phone.
Intimacy: the one where you tell me things you don’t tell anyone else
I am flattered that clients continue to share things with me — plans, worries, numbers — some they wouldn’t necessarily volunteer to anyone else. I hold to an old adage here: seek first to understand before being understood, a principle I stand by completely. There’s no point building you a plan without the whole picture, and getting there depends on you trusting me enough to hand it over.
It’s also not only about how comfortable someone feels with me personally — it’s whether the systems gathering that information can be trusted too. I use tools like Cash Calc partly because of how seriously they take data security and GDPR, not just because they’re convenient. Trustworthy channels matter as much as a trustworthy person.
Self-orientation: the one where it’s fine to ask if I’m worth it
I run a business — and, happily, I get paid for the work, the same as any other professional you’d trust with something this important. What actually matters isn’t whether I’m paid, it’s how.
What matters is whether it’s transparent and fair on both sides: an explicit commission you’ve signed for, and a fixed annual charge you’ve agreed to, not something buried in small print, or hidden entirely. It’s why we changed our business model to explicit upfront commissions and a fixed annual charge instead: if your pot grows, my income grows with it, and if it doesn’t, so does the pressure on me to fix that. That’s alignment we’re both genuinely invested in, together.
Here’s the part worth sitting with, though: if you don’t actually know how your adviser is paid, that isn’t a neutral score in this equation. It’s close to the worst score. Opacity is exactly where self-interest hides. The client who’s never had a conversation about charges with their adviser or bank hasn’t found a low self-orientation ‘score’ — they’ve simply never been shown the real one.
How it all adds up
None of this means size, track record or reputation don’t matter — they do. Assets under management, years of experience, qualifications, regulatory status: all real, all worth checking. The mistake is treating any one of them as a shortcut — proof enough on its own that you don’t need to look any further. A recognisable name and a marble lobby are just one more thing to weigh, alongside credibility, reliability, intimacy and self-orientation, not a replacement for discounting them.
Here’s the test I actually use, on myself as much as anyone: would I let my grandma be advised by these people? Not are they big enough, not do they look the part — would I trust them with someone I love, and be comfortable with whatever came of it?
That’s not a size question. It’s a transparency question. The institutions and advisers worth your trust are the ones happy to have every part of that looked at closely. The ones that aren’t tend to hide behind the brand instead.
So, where do I score?
I’d genuinely like to know. I’ve put together a short, honest set of questions built around this same equation — follow this link and have a play with it, a couple of minutes at most. Answer anonymously if you’d rather, or put your name to it and be as open as you like — whichever gets you being honest is the right choice.
If you already work with me, I want to know where you’d score me, including anywhere I’m falling short. If you’re not yet a client, use it to think about whoever currently holds that role in your life.
If the answer comes back high, a referral to someone I might be able to help, is always the best compliment you can pay me — though I’d rather earn it than ask for it outright. If it comes back low, I’d rather hear that directly too.
Either way, get in touch — that’s how this actually works.
Financial update France September 2026
By Katriona Murray-Platon
This article is published on: 9th September 2026

09.09.26
It’s September so it is back to school and back to work in France. It has been a very long and hot summer and for many people, it hasn’t been very restful. Many of you would have seen the news about were the major wildfires along the south-west coast which forced numerous residents to evacuate due to the smoke.
Fortunately, our town wasn’t evacuated, though the neighbouring town was not so lucky. Whilst most people have been able to return to their homes, the long process of rebuilding has only just begun for those who tragically lost their properties.
Over the summer, you should have received your tax statements either by post or on the impots.gouv.fr website. If you have less tax to pay than last year, this amount should have already been reimbursed to you in August. If, however, you have more tax to pay then your monthly payments (those that are made around the middle of the month) will increase as from the middle of September and any additional tax will be taken over four equal instalments at the end of September, October, November and December. If you don’t pay your tax automatically through your bank, you must pay the amount owed by 15th September. If you owe less than €300 of excess tax and you pay by direct debit, the amount will be taken on 25th September.
On 25th August 2026 the Prudential Assurance Company (PAC) board reviewed the Prufund Expected Growth Rates (EGR) as part of the Prufund regular quarterly review. The Prufund aims to grow their customers’ investments over the medium to long term (5 to 10 years) whilst buffering investors against short-term market volatility, using the unique established smoothing process.The Expected Growth Rate (EGR), the forward-looking element of the Prufund smoothing mechanism, remains unchanged this quarter. As regards the Unit Price Adjustment (UPA), the backward-looking part of the Prufund smoothing process, which is formulaic and non-discretionary, there was an upward UPA for the Prufund Cautious USD Dollar fund of 2.04%. Prufund is designed for the delivery of consistent returns over the medium to long term and although Prufund may lag behind a rapidly rising market, it protects in a falling market, demonstrating the consistency and robustness of Prufund in an ever more volatile world.
Despite troubling news headlines, August proved to be a surprisingly strong month for financial markets and balanced portfolios.
While geopolitical uncertainty and interest rate trajectories remain key concerns, second-quarter corporate earnings and Purchasing Managers’ Index (PMI) surveys indicate that the global economy continues to show resilience.
Notably, robust second-quarter results from US chipmaker Nvidia helped reassure investors following recent anxiety around the tech and AI sectors.
August’s performance reinforces the timeless investment wisdom: “time in the market” consistently beats “timing the market,” and maintaining a well-diversified portfolio remains the most effective strategy for managing volatility.
On 1st August the interest rates on the Livret A and LDDS savings accounts increased slightly from 1.5% to 1.7% to take into account the increase in inflation. The LEP account rate—available to households meeting specific income criteria – remains at 2.5%.
If you are planning energy-efficiency improvements for your property and wish to access government funding, you will need to consult the updated MaPrimeRénov’ guidelines, as the list of qualifying renovations was recently revised.
As we head into the final quarter of the year, it is an ideal time to consider your existing financial arrangements and your objectives for the months ahead. If you have any financial matters you would like to explore, please feel free to get in touch to arrange a review of your personal situation.
The Intelligence Question
By Peter Brooke
This article is published on: 16th June 2026
16.06.26
If you’ve been paying attention to investment markets over the last couple of years, you’ll already know that AI is one of the most significant forces reshaping the global economy. The returns from semiconductor companies, cloud infrastructure, and the businesses building and running AI systems have been remarkable — and the broader implications are only just beginning to play out.
I was in London recently for an industry conference, and the keynote session on AI was arguably the most discussed moment of the whole event. Not because the topic was new to anyone in the room — we’ve all been watching this unfold — but because of how quickly it’s now moving inside financial planning firms specifically. The framing that stuck with me: this isn’t just another software upgrade. It’s closer to an industrial revolution. The shift from paper-based advice to digital systems in the 1990s took a decade. What’s happening now is moving at a fraction of that pace.
I came away thinking a lot about what this means for how I work — and for you.
“Technology won’t replace advisers — but advisers who use technology will replace those who don’t.“
The most important point first
Before I get into the practical detail, I want to make something clear, because I think it’s the most important idea in this whole conversation.
AI is extraordinarily capable at processing information, finding patterns, drafting content, and summarising complexity.
But it lacks something that turns out to be rather crucial: judgement.
Here’s a simple example. If you ask ChatGPT, “I need to go to the car wash — it’s 200 metres away. Should I walk or drive?”, it will very sensibly tell you to walk. It’s close, after all. What it misses, of course, is that the entire point of going to the car wash is to wash the car. That’s not a failure of intelligence. It’s a failure of context, of understanding the bigger picture, of asking the right question in the first place.
That’s what human advisers do. Not just answer the question in front of us — but understand why you’re asking it, what’s really going on underneath it, and what the right question actually is.
What this looks like for me
I’ve been using AI tools actively for some time now, and recently completed an AI bootcamp with my productivity coach— deliberately, and with a specific intention.
My clients shouldn’t have to worry about keeping up with all of this (unless they want to); That’s my job. The more fluent I am in how these tools actually work, the better placed I am to use them well to benefit us all, and to recognise where the limits are.
Here’s what it actually changes — and what it doesn’t.
One of the most practical shifts is in how I handle meeting notes. If we speak by video call, I record and transcribe the conversation using a secure, multi-factor authenticated application. This means I can be fully present and listening, rather than split between the conversation and a notepad. Afterwards, the transcription lets me extract the key points accurately — compliance notes, commitments I’ve made to you, things you’ve agreed to send me, follow-up tasks from switches, withdrawals, or other issues we’ve discussed. That all goes into my task management system so nothing gets missed or delayed. The recording itself is deleted from the app immediately once I’ve taken what I need.
If we’re meeting face to face, I’ll simply ask your permission to record it, in the same way as for a video meeting and for the same reasons — in my experience, most people are very comfortable with it once they understand why.
Beyond meeting notes
AI is also helping me with research, drafting communications, analysing documents, and building better workflows across my business. The goal is that you should start to notice an improvement in follow-up — things like investment switches, withdrawal requests, or outstanding actions getting picked up more reliably and more quickly. Less ‘falling through the cracks’. The real goal is higher quality time on the things that actually matter — thinking through your situation properly, having the conversations that need to happen, and ideally spending more of that time with you face to face rather than behind my desk.
If you’re one of my existing clients and not already using the CashCalc Client Portal for document sharing and secure messaging, do get in touch and I’ll set you up. It’s a much safer option than email for anything sensitive, and is straightforward to use. See the short explainer video below if you haven’t seen it. And if you’ve ever wanted to book a call without the back-and-forth of scheduling, Calendly has been running quietly in the background for a while now — it’s saved all of us rather a lot of emails.
A word on security
I want to say something here without alarming you unnecessarily, because the picture is genuinely nuanced.
Email is convenient, and we all use it constantly. But it is also the most common point of vulnerability when fraud occurs. As AI tools become more sophisticated, so do the people misusing them.
At Spectrum, we’ve updated our processes accordingly. Any withdrawal or surrender request that arrives by email, I will always speak to you directly — by video call — before anything moves forward. No exceptions. In some cases, particularly if a new bank account is involved, I will also ask you to show me a bank statement, either by holding it up to the camera or screen-sharing. It sounds simple, because it is — but that kind of direct human verification is exactly what stops fraud in its tracks.
On that note: AI can now be used to create convincing video overlays in real time. If you ever receive a video call from someone claiming to be me and something feels off, ask them to wave their hand in front of their face. It breaks the overlay. I’ll always do it happily. If someone won’t — end the call.
Looking forward with judgement
“42” but what’s the question?
In Douglas Adams’ The Hitchhiker’s Guide to the Galaxy, a vast supercomputer called Deep Thought is asked to find the answer to ‘life, the universe, and everything’. After millions of years of calculation, it delivers its answer: 42.
The problem, it turns out, is that nobody had thought to ask for the question.
They then had to build another supercomputer — the Earth — just to work out what the question was supposed to be.
In a roundabout way, this is a fairly good description of where we are with AI right now.
One of my AI bootcamp coaches put it well recently: we’re moving from a knowledge economy to a judgement economy. Every answer is now theoretically available to everyone. What remains scarce — and genuinely valuable — is the ability to know which question to ask, to understand context, to see the bigger picture, and to make a call when the situation doesn’t fit neatly into any formula.
That’s what twenty-plus years of working with clients in France, navigating genuinely complex financial and tax environments, actually builds. AI will help me do more with that experience.
It won’t replace me.
I find this genuinely exciting. I hope you do too, and if you don’t I am here to help.
French financial update June 2026
By Katriona Murray-Platon
This article is published on: 4th June 2026
04.06.26
June marks the official beginning of summer – although the heatwave at the end of May gave us an early taste of the season. For French businesses, this is the final month to conclude key transactions and projects before the traditional slowdown in July and August. For French resident tax payers there are also a few matters to address before the summer really starts.
Most people will have by now submitted their tax return – those living in departments numbered over 55 have until 4th June and those who have engaged an accountant to do their tax returns will also be granted additional time to file. The tax statements will be available online from 24th to 31st July. For those receiving paper statements, these will arrive by post between 23rd July and 28th August.
The 15th June is the deadline for trustees of trusts where a trustee, settlor or beneficiary is fiscally resident in France, to complete the declaration 2181-TRUST2, declaring the value of the assets in the trust as at 1st January. The issue of trusts in France is one I’m often asked about. Are trust illegal in France? No. Trusts do not exist under French law, however French case law (jurisprudence) has long accepted that Trusts set up in other countries can have effect in France provided that they were created in accordance with the law of the country in which they were created, and that they do not contain any provisions which are contrary to French public policy (ordre public) especially as regards forced heirship (reserve héreditaire) – Paris Court of Appeal decision, 10th January 1970, Époux Courtois et autres consorts de Ganay. If you are the beneficiary, trustee or settlor of a Trust and this is the first time you have heard about the requirement to declare the trust, you need to first declare the existence of the trust using the form 2181-TRUST1 as well as the value as at 1st January.
Property owners have until 30th June to update the information on the buildings on their property and the occupants of those buildings on the impots.gouv.fr website if their situation has changed between 2nd January 2025 and 1st January 2026. If your property portfolio remains unchanged since the last declaration, no action is required. Only one declaration is necessary for a building and adjacent structures (e.g. garages, swimming pools etc) if they are occupied by the same person(s). Furthermore, as the review of rental values has been pushed back 3 years, landlords do not have to declare the amount of their rent received, unless they choose to do so.
On 26th May 2026, the Prudential Assurance Company (PAC) Board conducted its quarterly review of the Prufund Expected Growth Rates (EGR). The EGRs—which represent the forward-looking component of Prufund’s unique smoothing mechanism—remain unchanged for this quarter. Additionally, there were no Unit Price Adjustments (UPAs). The UPA is the backward-looking element of the smoothing mechanism; it is entirely formulaic, non-discretionary, and designed to protect investors from short-term market volatility.
The first half of 2026 has been defined by two dominant issues:
The geopolitical situation which has had a broad impact on financial markets, and AI – the significance of which is arguably still underappreciated by the broader market.
While the ongoing tensions in the Middle East show sporadic signs of diplomatic progress, it is still unclear whether we are any nearer a deal between Iran, Israel and the US.
After reports that a deal had been reached last week, oil prices dropped to $92 but have now risen to $96.28 the barrel on 1st June.
While we do not understate the human and political seriousness of these events, such conflicts are a regrettably familiar feature of the global landscape. Historically, long-term investors have been well-served by avoiding overreacting to short-term geopolitical shocks.
Inflation data published last week confirms that energy price pressures are increasingly filtering through to core economies. May data revealed inflation hitting 2.8% in France, 3.3% in Italy, and 3.6% in Spain. The European Central Bank (ECB) is expected to raise interest rates at its June meeting, despite visible signs of economic deceleration across the Eurozone. The composite Purchasing Managers’ Index (PMI)—a reliable metric for broader business activity—slumped to a 31-month low in May, following a contraction in the French economy during Q1 2026. Meanwhile, US forecasters now project inflation to end the year at 3.6%, marking yet another period where inflation sits stubbornly above the Federal Reserve’s 2% target.
In contrast to geopolitical events, the rise of AI represents a profound paradigm shift that will permanently alter the structure of the global economy.
The early part of 2026 saw a move away from software and information services businesses, as investors adopted a “sell first, ask questions later” approach. Time will tell as to which business models will become obsolete from the use of AI and which will see their productivity enhanced by these extraordinary breakthroughs.
Our fund managers are therefore focusing on asset allocation and portfolio construction whilst avoiding complacency.
Remaining open-minded to a changing economic landscape is key as well as allowing for flexibility in investment portfolios.
Even within a rapidly evolving global economy, the fundamental advantage of long-term investing remains entirely unchanged.
For the vast majority of portfolios, maintaining a disciplined, long-horizon stance—what could be termed deliberate “inaction”—remains the soundest strategy.
Despite the pervasive negative sentiment in the financial media, all major equity indices remain in positive territory for 2026 – a vital reminder for us all to keep focused on corporate and economic fundamentals, rather than market emotion.
The coming, more relaxed, summer weeks, are a perfect time to get in touch to arrange a free, no obligations, meeting with me to discuss your personal financial situation.
Tax considerations for Chateau owners in France
By Katriona Murray-Platon
This article is published on: 11th May 2026
11.05.26
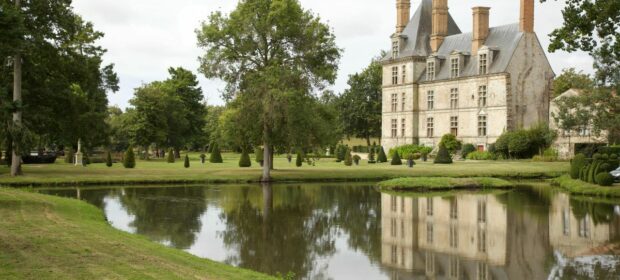
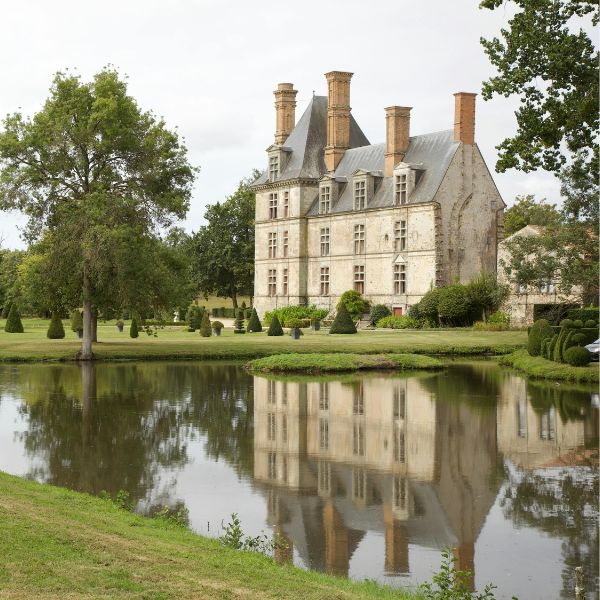
In April 2026, I had the pleasure of addressing a select group of prospective buyers at an event hosted by a prestigious estate agency. The setting was a magnificent French château—the perfect backdrop to discuss the fiscal and legal complexities of acquiring such historic assets. While the focus was on the “Château lifestyle,” these insights are equally pertinent to any high-value property acquisition in France.
The first question is whether to buy as a private individual or to set up a private property company called a Société Civile Immobilière (SCI). France has strict inheritance rules which dictate that the children inherit the majority of the estate leaving the surviving spouse with only the beneficial ownership (or ‘usufruit’) of the property. Whilst some Notaries advise inserting a clause in the deed of sale known as a “Tontine” clause to circumvent this, the inheritance aspects of this clause are often not fully explained. The effect of the Tontine is that the surviving spouse or partner is deemed to have owned the property solely from the outset. This can mean that the deceased spouses’ children are therefore disinherited.
An SCI is a legal entity through which several people, family members or investment partners, can own a property jointly. Shares can be gifted to children every 15 years utilising the €100,000 tax-free allowance per parent, per child. Non-residents can also, depending on their national law, leave their shares to their heirs thus avoiding French ‘forced heirship’ inheritance rules. The shareholders own the shares of the SCI company and the SCI owns the property. However if a shareholder wants to live in the property as their main residence in France, the SCI can lose some of its benefits. Also as a private company, the SCI needs to be created and maintained with albeit very basic (but necessary) book keeping, annual shareholders meetings and company registers.
The purpose of an SCI is to own property and receive the rental income, it cannot carry out any other business. So if the owner wants to carry out private events, chambre d’hote or sell produce, they need to set up a separate private limited company (S.A.R.L). For this they will need the advice of an accountant.
If the property is worth over €1.3million the owner(s) may be liable for Wealth Tax (‘IFI’). Non-residents only pay Wealth Tax on their French assets over this threshold. French tax residents, are liable for Wealth Tax on their worldwide properties after their 5th year of residence. The Wealth Tax declaration is done online with the income tax declaration. The tax is calculated on a sliding scale starting at 0.5% (for assets between €800,000 and €1.3 million) and rising to a maximum of 1.5% on assets over €10 million. Cash buyers may want to consider taking out a mortgage since it can reduce the net taxable value of the property. SCI shareholders are not necessarily liable for Wealth Tax even if the value of the asset is over €1.3 million since their loans to the SCI can be deducted. Additionally, primary residences benefit from a 30% valuation reduction, which may help keep the estate below the threshold.
France rewards those who own their property for a long time through tapered relief on Capital Gains Tax (CGT). CGT does not apply to the main residence. On secondary residences, there is full exemption from income tax (19%) after 22 years and from social charges (17.2%) after 30 years. After just five years of ownership, the purchase price is increased by a set 15% for improvement works and 7.5% for costs, without the need to justify these costs. However, if the cost of improvement works has already been deducted from rental income, it cannot deducted again to reduce the capital capital gains. For more substantial renovations, common with older properties, it is important to keep the receipts and records of all costs.
Lots of property owners rent out all or part of their properties either all year or seasonally. There are two categories of rental income, furnished rental and unfurnished rental. All rental income is taxed in France. Furnished rentals are treated as business income. Obtaining the “meublé de tourisme” classification is recommended since this allows for an abatement of 50% on the gross income before it is subject to tax (compared with the standard 30% abatement). This classification also allows a business to earn up to €83,600 under the simpler Micro-entreprise or only €15,000 if unclassified. Over these thresholds the business would be under the “régime reel” and would need to the assistance of an accountant. An accountant would also be able to advise on the LMNP (‘Loueur en Meublé Non-Professionnel’) status, whereby the value of the property can be depreciated. It is a good idea to ask the current owners of the property how they have structured their rentals or business.
France remains one of the world’s most desirable locations for luxury real estate. Before committing to a purchase, consult with experts who understand the cross-border nuances of the French system. At The Spectrum IFA Group, we provide bespoke financial advice and coordinate with a trusted network of estate agents, notaries, and accountants to ensure your investments are both protected and optimised.Together we can make your French dream come true!
French Financial update May 2026
By Katriona Murray-Platon
This article is published on: 6th May 2026
06.05.26
Life is never dull in France and when it comes to taxes, the French tax authorities like to keep things interesting by making changes to the online tax system every year.
If you haven’t already, now is the time to make a start on your tax return or check with your tax adviser that they have all the documents and information that they need to complete your return for you. The deadlines for submitting the returns are as follows:
| Paper returns | 19th May 2026 |
| Department 01 to 19 | 21st May 2026 |
| Department 20 to 54 | 28th May 2026 |
| Department 55 to 974 and 976 | 4th June 2026 |
The returns must be submitted before midnight on these dates, if not a 10% late penalty payment could be added to your tax bill. The paper returns must be put in the post box by midnight on 19th May.Whilst you can download our free Spectrum guide on your tax returns HERE, here are some tips that I have about doing the tax return given the recent changes to the system:
- Have all your figures ready and written down before you start (from bank statements, December 2025 payslips, UK tax statements etc). Stating the obvious here but this is a bit like baking a cake and realising that you don’t have the necessary ingredients. It is also a good idea to look at the boxes that you put your income in last year.
- If you have foreign income, do the 2047 form first. You need to go into “Annexes” and tick the 2047 box since it won’t be ticked from last year, then when you are in the 2047 form tick the boxes for your income. UK rental income and government pensions need to be put into Section 6 to be carried into box 8TK on the 2042. Other boxes will not be carried over automatically so you need to re-enter these amounts on the main tax form.
- Your bank accounts are already listed and the good news is that this year you don’t have to find the separate 3916 form. However, if you have an assurance vie, the figure given as the amount as at 1st January 2025 will not be correct and will be the figure entered last year, so you need to update this. The other information regarding your other accounts, should be the same so there is nothing to do there.
- This year you can choose whether your investment income is to be taxed at your marginal rate or at the flat tax rate. If you are either not taxable or only taxable in the 11% rate, then you should choose to have your investment income taxed at your marginal rate. However, if you are a higher tax payer, the flat tax may be more beneficial.
- Don’t forget your tax credits. If you have home help (gardeners, cleaners etc) you get a tax credit of 50% of the amount even if you have no tax to pay. This may have been taken at source through CESU for example but if not, you need to declare the amounts on the tax certificates you received from these organisations. There are extra boxes this year where you need to state the name of the organisation, type of organisation, type of service provided etc as well as the amount.
- Did you make any charitable donations in 2025? If so, you need to find the amounts and proof of these donations for your files. Charitable donations only give you a tax reduction, not a tax credit so if you are under the tax threshold you can declare the donations but it won’t affect your tax liability.
- If you have paid into a PER in 2025 the figure will appear on the form but you need to reenter it in the box below.
- If you have children in high school, sixth form or university you need to put the number of children in each category to get a small tax deduction. Cost of care for children under 6 can give rise to a tax credit of half of the amount.
Every year in France people either engage a tax specialist to do their taxes or they attempt to do the form themselves. In the latter case it can cause some stress and worry but also a rewarding feeling once it is done. There are many things that can stress me out but taxes isn’t one of them. So if you have any questions or concerns about your French taxes or financial matters, please do get in touch.
French Tax Returns 2026
By Peter Brooke
This article is published on: 22nd April 2026
22.04.26
What to Check Before You Submit
It’s that time of year again.
For most people in France, the tax return is a rinse-and-repeat process — but when you have income, assets, or accounts across multiple countries, it’s very easy to miss something.
Below is a practical checklist to help you stay organised, avoid common oversights, and submit your return with confidence.
Note: This is a guide, not an exhaustive list. You remain responsible for your own tax return and for ensuring the information you submit is complete and accurate.
Get organised first
Before you start, get everything in one place.
Checklist:
- Gather all income documents (pensions, salaries, rental income, investments)
- Collect bank statements and tax certificates
- Ensure all income reflects actual amounts received between 1 Jan and 31 Dec
- Note exchange rates (daily or annual average — but be consistent)
- Keep last year’s tax return open as a reference
- Keep a simple digital “tax file” and download certificates/emails as you receive them
Currency tip:
- For one-off payments, use the exchange rate on the date received
- For regular payments (e.g. monthly pensions/salary), an annual average can be used
- Apply a consistent approach — you can’t choose a more favourable rate
What you must declare
The key rule in France is simple: Everything is declarable, not everything is taxable.
Checklist:
- All worldwide income
- UK pensions (state, private, government
- Rental income (any country)
- Investment income (interest, dividends, gains)
- Withdrawals from investment products (including Assurance Vie, ISAs, Investment accounts.
- Other income types (e.g. salaries, self-employed income, foreign earnings, return of capital where applicable)
Important:
Even where income has already been taxed elsewhere (for example UK government pensions), it still needs to be declared in France
In most cases, you will receive a tax credit in France for tax already paid, assuming a double taxation treaty applies
Ensure your figures are accurate and based on the correct exchange rates at the time income was received
Key forms and expat “flags”
For expats, much of the complexity is about putting things in the right place.
Checklist:
- Main income declared on Form 2042
- Foreign income declared on Form 2047
- Foreign accounts declared on Form 3916
- Additional sections via 2042 C / 2042 RICI where relevant
Key things to check:
- All foreign accounts correctly declared
- Assurance Vie policies (Luxembourg / Dublin, etc.) included
- Correct boxes selected to trigger required declaration forms
- If you hold an S1, ensure the relevant box is completed on Form 2042 C
Healthcare and social charges
Your healthcare position can affect how social charges are applied.
Checklist:
- If you hold an S1, ensure the relevant box is completed on Form 2042 C
- Check social charges are applied at the correct rate
- Review how investment income is treated
Guide to rates (simplified):
- Pension income: up to 9.1%
- Assurance Vie gains: typically 17.2%
- Interest, dividends, capital gains: 18.6%
Important:
If you are covered by another EU system (e.g. S1), you may qualify for reduced rates. In some cases, charges may be applied initially and then adjusted or reclaimed later.
Assurance Vie — what to check (important for expats)
This is one of the areas where most mistakes happen. There are three separate checks:
1. The policy itself
- All non-French Assurance Vie policies (Luxembourg / Dublin) declared on Form 3916
- Full policy details included
2. The value of the policy
- Surrender value declared (usually at 1 January, in euros)
- Value taken from the provider’s annual statement
3. Withdrawals (where tax applies)
- Confirm if any withdrawals (rachats) were made
- Identify the gain element (not the full withdrawal)
Simple decision guide:
- If tax has already been applied → declare as income already taxed
- If not → declare so it can be taxed correctly in France
Important nuance:
Tax treatment can depend on whether premiums were paid before or after 2017 (PFL vs PFU). This is often shown on provider statements, but not always — so it’s worth checking.
Commonly missed items
- All non-French accounts declared on Form 3916 (including bank accounts, investment accounts, Foreign Assurance Vie, PayPal, etc.)
- Assurance Vie values and withdrawals correctly included
- Charitable donations declared (keep certificates in case of query)
- Children and household situation updated
- Any changes in income or assets reflected
Tax credits and useful extras
- Home help (cleaner, gardener, etc.)
- Childcare costs
- Children in school (primaire, collège, lycée — small credits may apply)
- Any eligible household services
- Any tax certificates received
Note:
Some income and tax credits are pre-filled on the return. It’s worth checking these against your own records (e.g. December payslips or provider statements) and correcting if needed
Final checks before you submit
- All income sources included
- All foreign accounts declared
- Figures are consistent
- Exchange rates applied consistently
- No obvious omissions
Practical tips
- Don’t leave it until the last minute
- Use last year’s return as your template
- The right to make an error is recognised in French law — once the system reopens, you can go back and make corrections
- Use the online messaging system if needed
- You can also visit your local tax office — they are often very helpful
Useful resources
To make this easier, I’ve included a couple of practical tools at the following links, which I hope you find useful:
Tax Return Preparation Spreadsheet