
AI has moved from research lab to the centre of global capital allocation faster than almost any technology before it. Goldman Sachs Research projects worldwide AI-related investment will exceed $1 trillion in 2026, with about $581 billion of that in the US alone. At 2-5% of GDP, this peak intensity is comparable to prior general-purpose technology buildouts — railways, electrification, the internet — though compressed into a far shorter timeframe.
Viewing posts categorised under: Mondaq
Artificial Intelligence: Opportunity, Risk, and a Question Bigger Than Markets
By Andrew Lawford
This article is published on: 16th September 2026
16.09.26
Where the opportunity lies
The clearest opportunity is infrastructure: chipmakers, power and grid companies, and data-centre suppliers behind AI’s physical build-out. A second lies in software and services companies genuinely embedding AI and showing measurable productivity gains, rather than simply attaching the label. A third is second-order: healthcare, logistics, and financial services benefiting from AI-driven efficiency without being “AI plays” themselves. For cross-border clients, diversified thematic exposure, rather than concentrated single-stock bets on US mega-caps, is usually the more sensible route in.
Where the risk lies
The most immediate risk is circularity: a meaningful share of AI capex is financed by the same handful of companies that supply and buy from one another, so returns are more sensitive than headline growth suggests to any slowdown in adoption or rise in the cost of capital.
Concentration compounds this — a small number of companies drive a disproportionate share of both AI capex and recent index gains, so even diversified portfolios may carry more AI-specific risk than clients realise. And the return on this capital is genuinely uncertain: even Goldman’s own analysis calls AI spending a “key source of uncertainty for macro markets,” without forecasting whether it will pay off.
The existential question
Clients increasingly ask directly: could AI pose a genuine risk to humanity? Honesty about uncertainty matters more here than a confident answer either way, because expert opinion is genuinely split. A recent academic survey found two coherent camps — those viewing advanced AI as a powerful but controllable tool, and those viewing sufficiently autonomous systems as a harder-to-control risk. Disagreement correlated less with general AI expertise than with familiarity with specific technical concepts, such as the tendency of highly capable, goal-directed systems to develop self-preservation sub-goals; researchers less familiar with such ideas were markedly less concerned. Still, 78% of surveyed experts agreed that technical AI researchers should be concerned about catastrophic risks — real agreement on direction, even amid disagreement on scale and timing, which most estimates place in decades rather than years.
A balanced conclusion
AI will likely remain a defining investment theme this decade, and exposure to it is reasonable. But the same technology is the subject of genuine, unresolved expert disagreement about its longer-term risks to society. The sensible approach: disciplined, diversified exposure to the theme, awareness of concentration already embedded in portfolios, and honest acknowledgment that both AI’s financial and societal trajectory remain more uncertain than its loudest advocates or critics currently claim.
Perhaps it will come as no surprise (or perhaps I’m just hoping that readers recognised the above for what it was!) when I say that everything written before this current paragraph was generated by AI (Claude in this case), based on the following prompt I had given it (please note that Claude knows what work I do and that I am based in Italy):
“I need you to write me an article that I will distribute to my clients. The topic is AI and its opportunities and risks from an investment standpoint, as well as a balanced discussion of whether or not there are existential risks to humanity over the medium to long term. Max 1000 words”
It took about 2 minutes to generate the response, which I subsequently asked it to shorten to no more than 500 words and which I have not edited at all. To me it seems like a competent, if somewhat uninspiring commentary on the current AI debate and its consequences for investors. I’m not sure that it has really given me any great insights beyond what one would glean from reading a modest amount of financial journalism and from being generally interested in the subject. In fact, I find myself wondering if these sorts of AI-generated documents “are simply the copy of one thousand summaries” (solo la copia di mille riassunti) as Samuele Bersani put it in his song Giudizi Universali.
Needless to say that the topic of AI must be taken into consideration when investing, yet we must acknowledge the limits of our understanding in terms of how all of this plays out. I think it is wise to exclude the potential for an existential crisis of humanity from our calculations, mainly because if that scenario does unfold, rather like a global nuclear war, we will have more important things to worry about than the value of our investment accounts. On a more moderate view, there will be beneficiaries and victims of AI that we cannot even begin to imagine, and we must maintain a fully diversified approach and understand how much exposure we have to certain types of investment.
One of the first things I do when evaluating a portfolio is try to get an understanding of the underlying investment exposures in order to make it clear what risks clients are exposed to: it remains a useful discussion to have before contemplating any investment changes, above all considering the concentration in a small number of companies that certain stock indices have (these points are well-made by Claude above).
Finally, should I just forget about AI in my day-to-day work?
That seems foolish, rather like the accountant I remember stories of from my youth who forbade the use of calculators in his practice because he was convinced that his employees’ brains would atrophy as a result. AI is enormously helpful in analysis and presentation, in making calculations and especially in investigating and flagging potential errors. Yet it is imperitive to understand any AI output before adding my own evaluation and conclusions, and the exacting task of finding the correct investment structures and navigating the potentially difficult topics of estate planning and tax efficiency seem, at least for the moment, to be beyond what AI can competently deal with. So, welcome to the era of the AI-enabled adviser. Believe me when I say that I am highly motivated to be one, because otherwise I may find myself facing that most uncomfortable of questions: what exactly do you need me for?
I have Moved to Spain – What Should I Do With My UK Pension?
By Matthew Green
This article is published on: 15th September 2026
15.09.26
Moving to Spain is exciting. Your pension, however, probably wasn’t designed with the move in mind.
For many people, a UK pension is one of their largest assets. So, after becoming resident in Spain, it is natural to ask whether the pension should now be transferred to a Spanish or international arrangement.
But there is an important question to ask first:
Does it actually need to move?
The answer isn’t necessarily yes.
Do I need to transfer my UK pension?
Moving to Spain does not automatically mean that your UK pension needs to be transferred overseas.
Depending on your circumstances, you may be able to leave your pension in the UK and continue to manage it from Spain. In some cases, that may be the most appropriate option.
Before considering a transfer, it is important to understand what you already have, including:
- The type and value of your pension
- The investments and charges
- Any guarantees or valuable benefits
- When you can access the pension
- How you expect to use it in retirement
- Whether you may eventually return to the UK
A transfer should therefore be a financial planning decision, rather than simply a consequence of moving country.
What happens to the tax?
Becoming Spanish tax resident can change the way your pension income is treated.
The UK and Spain have a double taxation agreement, and the precise treatment depends on the type of pension and your circumstances. Private pensions and government-service pensions can also be treated differently.
This is why simply looking at where your pension provider is based isn’t enough.
Your tax residency, the type of pension and how you intend to take the benefits all need to be considered together.
What about my UK State Pension?
Your UK State Pension can generally continue to be paid while you live in Spain, subject to the relevant rules.
But your State Pension is only one part of your retirement income.
Your wider retirement plan might also include workplace pensions, personal pensions, SIPPs, investments, property or cash savings.
The important question is therefore not just:
“What will my pension pay me?”
but:
“How will all my sources of retirement income work together?”
Should I transfer my pension overseas?
This is where it is particularly important not to rush.
Certain overseas pension transfers can be subject to a 25% overseas transfer charge, depending on the circumstances, although exemptions and allowances can apply.
There can also be valuable benefits or guarantees attached to an existing pension that could be lost following a transfer.
So rather than asking:
“Can I transfer my pension?”
the better question is:
“What would I gain by transferring, and what could I potentially lose?”
What should I review?
Even if you decide not to transfer your pension, moving to Spain is a good reason to review your overall retirement arrangements.
Consider:
- Is the investment strategy still appropriate?
- Are the charges reasonable?
- Is the level of risk suitable?
- How will the pension provide the income you need?
- How does it fit with your other investments?
- What happens if you eventually return to the UK?
- Have your retirement plans changed since moving to Spain?
These questions become particularly important as you approach retirement.
So, what should I do?
If you’ve recently moved to Spain with a UK pension, I wouldn’t start by asking which provider you should transfer to.
I’d start by understanding what you already have and how it fits into your new life in Spain.
For some people, the best decision may be to leave their UK pension exactly where it is. For others, a review may identify opportunities to improve the investment strategy, charges, flexibility or overall retirement plan.
Moving to Spain doesn’t automatically mean your pension needs to move. But your financial plan probably deserves to move with you.
Have you reviewed your pension since moving to Spain?
If you’ve recently become resident in Spain and haven’t reviewed your UK pension and wider retirement planning, I would be happy to have an initial conversation with you.
At The Spectrum IFA Group, I work with expatriates living in Spain to review their pensions, investments and retirement plans, taking into account their circumstances in both the UK and Spain.
If you’re unsure whether your existing pension arrangements are still right for you, get in touch and we can discuss your situation and whether a review would be worthwhile.
The Trust Recession
By Peter Brooke
This article is published on: 14th September 2026
14.09.26
My wife, Chris, and I were having one of those meandering conversations recently— when she said something that’s been sitting with me ever since: “Do you think we’re in a trust recession?” She’s right, and once you start looking for it, you can’t stop seeing it.
Politicians treating inconvenient facts as just another opinion to argue with. Long-standing science backed issues dismissed despite the evidence of one climate shock after another. Deadly measles cases back to record levels just as trust in real data and expertise has quietly worn away.
Algorithms that don’t show you the truth, but more of whatever you already believe, until “the world is flat” starts to feel like a reasonable position to the person living inside that feed. None of this is exactly hidden any more. It’s just out in the open, and it’s exhausting.
I recently wrote, in The Intelligence Question, about why a human still needs to be in the loop even as AI reshapes financial planning.
It assumed something I want to go back and examine further:
“That you know which human to trust with that loop in the first place.”
Because this “trust recession” isn’t stopping at politics and social media. It’s already sitting inside financial services, quietly, and I’ve watched it play out over the years with clients — smart, successful, careful people who trusted very well-known financial institutions simply because they were well known, and found out later that “well known” isn’t the same as “on your side.”
So this isn’t really a piece about who you trust with your money. It’s about who you trust with your future.
Trust isn’t just a feeling, it’s an equation
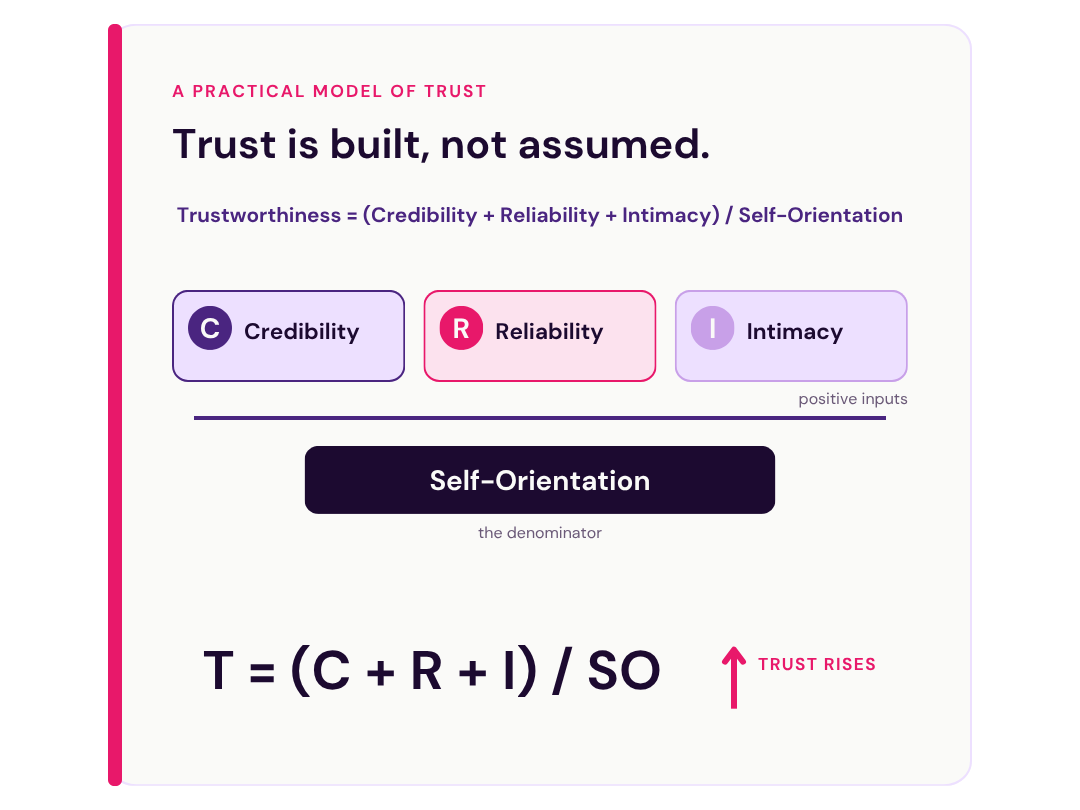
In 2000, in a book called The Trusted Advisor, Charles H. Green and his co-authors put a number on something that usually just feels like instinct. Their formula, still the cornerstone of Trusted Advisor Associates’ work is this:
-
Credibility: can I be believed — do I actually know what I’m talking about?
-
Reliability: do I do what I say I’ll do, when I say I’ll do it?
-
Intimacy: are you comfortable being honest with me, even about the things you don’t tell anyone else?
-
Self-orientation — the one that quietly challenges the other three — is whether I’m doing this for you, or for me.
It’s worth taking that last one seriously: the largest meta-analysis of human trust ever conducted — more than 300 studies, pulled together in 2023 — found transparency to be one of the strongest single predictors of whether someone is seen as trustworthy at all.
At Spectrum, we run this test too, by the way, before any fund manager, platform or provider gets anywhere near your money — regulation, transparency, track record, process!
Same four principles, just pointed at the people and companies we choose to work with.
Credibility: the one where questions matter more than answers
Anyone can claim to be credible — that’s exactly the trouble with a trust recession, self-declared expertise is cheap.
What actually proves it is different: whether you catch the thing nobody thought to ask about. A couple I was introduced to came to me with what looked like a straightforward question about selling a UK property one of them had owned for decades. Buried in the conversation was a detail neither thought was relevant: they’d married in France the year before the sale — which changed which country had the right to tax it, and by how much, eventually worth a six-figure sum in tax savings. Nobody asked me that question; I saw the connection because I’ve spent over twenty years looking out for exactly this kind of thing. That’s not something you can prompt your way into with AI.
Credibility isn’t just about any one story like this — it’s whether that pattern holds up, case after case, including the times I tell you plainly that I don’t know something and need to go and find out.
Reliability: the one I’m still working on
Reliability isn’t glamorous, and if I’m honest, it’s the one of these four I’d most like to get better at. I’m a human, not a system — I can’t promise to be perfect at it and when I do make mistakes I will endeavour to “own them” and put things right as efficiently as possible.
Reliability is the admin done properly and on time: fund switches processed without you having to chase them, withdrawal requests that don’t sit in a drawer, anti-money-laundering checks completed without three reminder emails. No drama, just doing the job properly, every time — and it’s precisely where I’m starting to use things like AI to try and stay on top of an ever-growing to-do list, rather than pretending it doesn’t grow.
What this technology hasn’t reached, and I don’t think it will any time soon, is the human part: knowing that a French wedding mattered to a British tax bill, or simply being the one who picks up the phone.
Intimacy: the one where you tell me things you don’t tell anyone else
I am flattered that clients continue to share things with me — plans, worries, numbers — some they wouldn’t necessarily volunteer to anyone else. I hold to an old adage here: seek first to understand before being understood, a principle I stand by completely. There’s no point building you a plan without the whole picture, and getting there depends on you trusting me enough to hand it over.
It’s also not only about how comfortable someone feels with me personally — it’s whether the systems gathering that information can be trusted too. I use tools like Cash Calc partly because of how seriously they take data security and GDPR, not just because they’re convenient. Trustworthy channels matter as much as a trustworthy person.
Self-orientation: the one where it’s fine to ask if I’m worth it
I run a business — and, happily, I get paid for the work, the same as any other professional you’d trust with something this important. What actually matters isn’t whether I’m paid, it’s how.
What matters is whether it’s transparent and fair on both sides: an explicit commission you’ve signed for, and a fixed annual charge you’ve agreed to, not something buried in small print, or hidden entirely. It’s why we changed our business model to explicit upfront commissions and a fixed annual charge instead: if your pot grows, my income grows with it, and if it doesn’t, so does the pressure on me to fix that. That’s alignment we’re both genuinely invested in, together.
Here’s the part worth sitting with, though: if you don’t actually know how your adviser is paid, that isn’t a neutral score in this equation. It’s close to the worst score. Opacity is exactly where self-interest hides. The client who’s never had a conversation about charges with their adviser or bank hasn’t found a low self-orientation ‘score’ — they’ve simply never been shown the real one.
How it all adds up
None of this means size, track record or reputation don’t matter — they do. Assets under management, years of experience, qualifications, regulatory status: all real, all worth checking. The mistake is treating any one of them as a shortcut — proof enough on its own that you don’t need to look any further. A recognisable name and a marble lobby are just one more thing to weigh, alongside credibility, reliability, intimacy and self-orientation, not a replacement for discounting them.
Here’s the test I actually use, on myself as much as anyone: would I let my grandma be advised by these people? Not are they big enough, not do they look the part — would I trust them with someone I love, and be comfortable with whatever came of it?
That’s not a size question. It’s a transparency question. The institutions and advisers worth your trust are the ones happy to have every part of that looked at closely. The ones that aren’t tend to hide behind the brand instead.
So, where do I score?
I’d genuinely like to know. I’ve put together a short, honest set of questions built around this same equation — follow this link and have a play with it, a couple of minutes at most. Answer anonymously if you’d rather, or put your name to it and be as open as you like — whichever gets you being honest is the right choice.
If you already work with me, I want to know where you’d score me, including anywhere I’m falling short. If you’re not yet a client, use it to think about whoever currently holds that role in your life.
If the answer comes back high, a referral to someone I might be able to help, is always the best compliment you can pay me — though I’d rather earn it than ask for it outright. If it comes back low, I’d rather hear that directly too.
Either way, get in touch — that’s how this actually works.
Why you should change adviser when you move to Italy.
By Gareth Horsfall
This article is published on: 11th September 2026
11.09.26
More and more UK clients are choosing to live, work or retire overseas. Italy has always been and continues to be a popular destination, and is attracting not just retirees but internationally mobile professionals, entrepreneurs and families.
If you have been working with a UK financial adviser, this could present a big challenge. You may have valued and trusted their advice for many years, but becoming resident in Italy can fundamentally change your financial planning requirements.
A different tax system, regulatory framework, pension rules and investment restrictions apply in Italy. Arrangements that might have been suitable for you when you when you were in the UK will need to be reassessed, once you move to Italy. The tax treatment of your pensions and investments will change, while local reporting requirements, succession laws and inheritance tax rules will introduce further complexity.
Without appropriate planning, you can face unexpected tax liabilities, unsuitable financial arrangements or difficulties accessing ongoing advice. Your adviser should have local financial and tax knowledge and consider your life in the future.
The importance of local knowledge
Planning across borders requires more than just a general understanding of international finance. It requires knowledge of the rules for residents of Italy and your country of origin.
The treatment of UK pensions, investment accounts, insurance-based arrangements and other assets differs considerably between the UK and Italy. A product that is tax-efficient in the UK, such as an ISA, does not receive the same tax treatment in Italy. You may also find that certain investment funds or financial institutions are unable or unwilling to retain you as a client when you change your residency to Italy.
Regulatory permissions are equally important. A UK adviser will no longer hold the permissions required to provide regulated advice once you become resident in Italy. Even if they promise continuing service by offering ‘management but not advice’, (which is not a viable solution) without local knowledge or access to appropriate solutions they can be inadvertently creating more problems for you in the future.
Advisers naturally want to protect your longstanding relationship, but they must also recognise the limits of their permissions and expertise. All advisers should operate in your best interests. Finding a regulated adviser in Italy and working on a plan with your UK adviser, together, to transition you over is the best solution.
A UK adviser should feel comfortable that they can introduce you to a company like The Spectrum IFA Group whom they can work collaboratively with. You gain access to relevant international and local expertise, while your relationship with your UK adviser is recognised and respected.
Your financial life does not stop at the UK border, but the rules governing your pensions, investments, taxation and estate planning can change considerably when you move overseas.
A UK based adviser may have spent many years earning your trust, and the relationship should not be placed at risk simply because you relocate.
As an adviser and the manager of The Spectrum IFA Group, I have over 20 years of relevant international and local Italian financial planning knowledge and created a list of trusted professionals that I can refer you to.
Planning before your move
The most effective time to consider the financial implications of your relocation to Italy is before you change residence.
Decisions made in the months leading up to a move can have a lasting effect on how your income, investments, pensions and estate are treated.
Early engagement gives us time to plan and utilise any tax benefits in your home country, any tax and time planning opportunities in the year of your move and then any possible Italian tax incentives after your move.
Addressing these matters if you have already become resident in Italy becomes harder or more expensive to resolve, but not impossible.
Supporting you in your move
Cross-border planning is rarely a one-off exercise. Your circumstances will evolve as you move to Italy, develop businesses, sell assets, receive inheritances or approach retirement.
You may decide to remain in Italy long-term, or decide to move back to the UK, or divide your time between different countries. Your financial arrangements must therefore remain flexible enough to respond to further changes in residence, regulation and personal objectives.
Regular reviews are essential. This allows us to consider whether arrangements remain appropriate, whether legislative developments have altered your position and whether your longer-term goals have changed.
Retirement Isn’t the Finish Line
By Matthew Green
This article is published on: 10th September 2026
10.09.26
It’s When the Financial Decisions Get Harder
For years, retirement is the destination.
You work. You save. You invest. You build your pension.
Then you retire.
Job done? Not quite.
In fact, retirement is often when the financial decisions become more important.
While you are working, your salary provides a regular income. If markets fall or you overspend, you have time to recover.
Once you retire, the equation changes.
Your investments may need to provide your income, potentially for 20, 30 or even 40 years.
So the question isn’t simply:
“How much money have I accumulated?”
It is:
“Will it be enough to support the life I want?”
What happens when things don’t go to plan?
Markets fall.
Inflation rises.
Unexpected expenses appear.
You live longer than expected.
Or one spouse dies before the other.
A retirement plan built around everything going perfectly isn’t really a plan.
This is why understanding your future cash flow can be just as important as choosing your investments.
Rather than simply looking at what you have today, you can model different scenarios:
- What if investment returns are lower?
- What if inflation remains high?
- What if you live to 95 or 100?
- What if you need a large amount of capital unexpectedly?
- What happens to your spouse if you die first?
You can’t predict the future. But you can prepare for different versions of it.

Your retirement isn’t a number
Someone with €500,000 may be financially comfortable.
Someone with €1.5 million may not be.
It depends on their income, spending, investments, tax position and the lifestyle they want to maintain.
That’s why retirement planning shouldn’t stop when you retire.
It’s when your wealth needs to start doing the job your salary used to do.
Is your retirement plan built around a number – or a lifestyle?
If you’re approaching retirement or already retired in Spain, don’t leave the answer to chance.
A personalised cashflow forecast can bring your financial future to life. It can show how your income, spending, investments and capital could develop over time—and, importantly, what happens if things don’t go exactly as planned.
You don’t need to predict the future. You need to understand it.
Are you receiving the advice you should be?
There are also many people who already have pensions, investments or other financial arrangements in place but haven’t had a meaningful review of their circumstances for some time.
Perhaps your adviser has retired or moved on. Perhaps you’ve been passed between advisers. Or perhaps you simply aren’t receiving the regular contact and ongoing advice you expected.
If that sounds familiar, you don’t necessarily need to start again.
A fresh review can help you understand what you currently hold, whether it remains appropriate for your circumstances and whether your financial arrangements are still aligned with your goals.
Your financial circumstances don’t stand still—and your financial plan shouldn’t either.
Whether you’re approaching retirement, already retired, or simply feel that your existing arrangements aren’t receiving the attention they deserve, a review can be a useful first step.
There is no obligation to change your existing investments or make any immediate decisions.
The starting point is simply a conversation about where you are today, what you want your money to achieve and whether your current arrangements are still working for you.
If you haven’t received retirement or pension planning advice in the past 12 months, it may be time to review where you stand. Get in touch to arrange an initial conversation and let’s look at whether your current arrangements are still working for you.
Because the earlier you identify a potential problem, the more options you have to do something about it.
Financial update France September 2026
By Katriona Murray-Platon
This article is published on: 9th September 2026

09.09.26
It’s September so it is back to school and back to work in France. It has been a very long and hot summer and for many people, it hasn’t been very restful. Many of you would have seen the news about were the major wildfires along the south-west coast which forced numerous residents to evacuate due to the smoke.
Fortunately, our town wasn’t evacuated, though the neighbouring town was not so lucky. Whilst most people have been able to return to their homes, the long process of rebuilding has only just begun for those who tragically lost their properties.
Over the summer, you should have received your tax statements either by post or on the impots.gouv.fr website. If you have less tax to pay than last year, this amount should have already been reimbursed to you in August. If, however, you have more tax to pay then your monthly payments (those that are made around the middle of the month) will increase as from the middle of September and any additional tax will be taken over four equal instalments at the end of September, October, November and December. If you don’t pay your tax automatically through your bank, you must pay the amount owed by 15th September. If you owe less than €300 of excess tax and you pay by direct debit, the amount will be taken on 25th September.
On 25th August 2026 the Prudential Assurance Company (PAC) board reviewed the Prufund Expected Growth Rates (EGR) as part of the Prufund regular quarterly review. The Prufund aims to grow their customers’ investments over the medium to long term (5 to 10 years) whilst buffering investors against short-term market volatility, using the unique established smoothing process.The Expected Growth Rate (EGR), the forward-looking element of the Prufund smoothing mechanism, remains unchanged this quarter. As regards the Unit Price Adjustment (UPA), the backward-looking part of the Prufund smoothing process, which is formulaic and non-discretionary, there was an upward UPA for the Prufund Cautious USD Dollar fund of 2.04%. Prufund is designed for the delivery of consistent returns over the medium to long term and although Prufund may lag behind a rapidly rising market, it protects in a falling market, demonstrating the consistency and robustness of Prufund in an ever more volatile world.
Despite troubling news headlines, August proved to be a surprisingly strong month for financial markets and balanced portfolios.
While geopolitical uncertainty and interest rate trajectories remain key concerns, second-quarter corporate earnings and Purchasing Managers’ Index (PMI) surveys indicate that the global economy continues to show resilience.
Notably, robust second-quarter results from US chipmaker Nvidia helped reassure investors following recent anxiety around the tech and AI sectors.
August’s performance reinforces the timeless investment wisdom: “time in the market” consistently beats “timing the market,” and maintaining a well-diversified portfolio remains the most effective strategy for managing volatility.
On 1st August the interest rates on the Livret A and LDDS savings accounts increased slightly from 1.5% to 1.7% to take into account the increase in inflation. The LEP account rate—available to households meeting specific income criteria – remains at 2.5%.
If you are planning energy-efficiency improvements for your property and wish to access government funding, you will need to consult the updated MaPrimeRénov’ guidelines, as the list of qualifying renovations was recently revised.
As we head into the final quarter of the year, it is an ideal time to consider your existing financial arrangements and your objectives for the months ahead. If you have any financial matters you would like to explore, please feel free to get in touch to arrange a review of your personal situation.
The Italian flat tax regime for HNW and the UK pension opportunity
By Gareth Horsfall
This article is published on: 7th September 2026
07.09.26
By now, the Italian flat tax regime for High Net Worth individuals has been running since 2017 but has probably seen more of an uptake in recent years. It has become more interesting for many HNW individuals to establish residency in Italy, even if you have business interests elsewhere and also when the flat tax rate has increased from €100000 in 2017 to €200,000 and from the 1st Jan 2026 increased to €300,000.
It is commonly thought that once accepted onto this tax regime that there is little financial planning to be done and you can largely leave your financial affairs untouched. This might well be the case, but it leaves a hugely unexplored financial planning opportunity by most advisers and accountants alike – liberation from UK pensions.
In the case of a UK pension (or most other country pensions), if you remain a resident in Italy after the end of the 15 years period, and you are over the age at which you can access your UK pension then any lump sums and / or income drawdowns from this pension will likely be subject to your progressive marginal income tax rates.
A lot depends on where you might be resident at the time of taking your retirement scheme benefits, but in most European countries, for example, the income from your UK pension will be taxed in Italy at the following rates: 23% rising to 35% and 43%)
On the other hand, if you were to generate income from a portfolio of assets or a highly tax efficient Investment Bond, you would only be charged capital gains and / or non-earned income tax (26% flat rate in Italy) on the assets and not on the whole income drawdown.
Therefore, if it were possible to convert your UK pension pot into a standard investment portfolio you could potentially free yourself of future income tax liabilities.
The good news is that it is possible with careful planning. Firstly, you would need to consider your future residency arrangements when taking benefits from the pension pot and assuming you are already above the UK pension access age (55 or 57 from 6th April 2028), then you could encash your UK pension and invest the proceeds in an investment portfolio, and in the process have created a much more tax efficient future income stream for yourself.
If you are on the HNW flat tax regime, you have established residency outside the UK and therefore under the double taxation treaty between the UK and Italy you only need to pay tax on UK pension income in your country of residence.
However, any encashment should be exercised with caution.
As a result of establishing residency outside the UK, the UK government will automatically apply a progressive emergency tax code to your encashment (20%, 40% and 45%) and assuming the UK pension pot is of sizeable value then this could mean an equally sizeable HMRC tax bill.
But, because you can prove residency outside the UK, you are covered by the UK /Italy double taxation treaty, and any tax will be refunded by HMRC on request of an NT (non-taxable) code.
However, there is a way to avoid paying tax to HMRC altogether, with a little careful planning.
If you think that might be of interest to you, please feel free to get in touch on
gareth.horsfall@spectrum-ifa.com or message me on +39 333 649 2356
Finance event Italy September 2026
By Gareth Horsfall
This article is published on: 2nd September 2026
02.09.26
FINANCIAL TALK, TAX PLANNING AND RAPHAEL IN UMBRIA – 24TH SEPTEMBER 2026
BOOK YOUR PLACE ON THE INVESTMENT, FINANCIAL PLANNING AND RAPHAEL IN UMBRIA TALK ON THE 24TH SEPTEMBER IN THE HEART OF THE NICCONE VALLEY.
If you haven’t registered, I would like to extend the invite to the event I will be hosting in the Niccone valley, Umbria on the 24th September.
On the 24th September in the gardens of the amazing Casa Nova, https://casanovaumbria.eu/, Niccone Valley, near Umbertide, I will be hosting an investment talk presented by Christopher Saunders from New Horizon Asset Management (Watch his video here on why we could be living through World War 3…) followed by some Italian financial and tax planning talk, and Q&A, from myself and to finish a wonderful talk from Dr Tom Henry on the life of Raphael in Umbria. All this within the stunning Niccole valley backdrop.
Will you make these Spanish tax mistakes in the next four months?
By Barry Davys
This article is published on: 31st August 2026
31.08.26
It is important to remember that the Spanish tax year runs from 1 January to 31 December.
As we approach the end of the Spanish tax year, I often see people making decisions that inadvertently increase their tax bill for the current year. If you do not want to pay more tax than necessary, here are some guidelines to help you reduce your tax bill.
What can increase your tax bill?
Sales and certain transfers of assets before 31 December may be taxed in the current tax year.
Sales
Some taxes are cumulative. If you continue selling assets that have increased in value, the tax rate will be based on your total gains for the whole year.
The tax rate will also depend on which Autonomous Community you are resident in. For example, the top rate of tax on gains in Catalonia is 30%.
If you think your savings, or perhaps that second property, have performed well, the result can look very different once the tax bill is taken into account.
Selling a second property, or selling your main residence if you are under 65 at the point of sale, can create a significant tax bill.
If you have only one property to sell but have already made significant gains from other sales this year, should you consider completing the property sale in the new tax year instead?
The profit from the sale of vested shares received through share option schemes can result in either income tax or capital gains tax. The constitution and terms of the share option scheme will determine which tax treatment applies.
We regularly see shares being sold soon after they have vested. If you have share options vesting, you can reply to this email to find out more and discuss whether you should sell in this tax year or the next.
Transfers
Making transfers of assets between people before the end of the year can also increase your tax bill. These transfers can include:
- Gifts to individuals who are tax resident in Spain
- Gifts to non-resident individuals involving assets located in Spain
- Transfers of non-EU pensions (for example, UK pensions) into European-based pension schemes
A pension transfer can potentially be taxed on the whole transfer value by adding it to all your other income. The result can be a very significant tax bill — potentially tens of thousands of pounds on a relatively modest pension.
Get specialist advice before you act
To ensure you receive the best possible support and advice, we can also call upon lawyers, who we have worked with 14 years, as needed.
What you should do in relation to a sale or transfer will depend on your personal circumstances. There is no one-size-fits-all answer.
To avoid making costly mistakes, you are welcome to book a call at a time that is convenient for you using my online booking system. You can tell me about your personal circumstances, and we can then advise you on what you should consider doing.
The right course of action will follow from there.
What If Spain Doesn’t Work Out?
By Matthew Green
This article is published on: 28th August 2026
28.08.26
Moving to Spain can feel like the final destination.
For many expats, the plan is simple: sell up, move abroad, enjoy the lifestyle and build a new life in the sun.
But what happens if, somewhere down the line, Spain isn’t quite what you expected?
Perhaps your circumstances change. Your children move elsewhere. Your priorities change. You decide you want to be closer to family. Or maybe you simply discover that another country, or even your home country, suits you better.
It is something few people consider when they first move abroad.
Your financial life needs to be flexible too
When you move countries, your financial affairs can become increasingly complicated.
You may have pensions in one country, investments in another, property in Spain and bank accounts spread across several jurisdictions.
Then, if you decide to move again, the questions start to appear:
What happens to my investments?
What happens to my pension?
Will I still be able to hold the same investments if I leave Spain?
What happens to my tax position?
Will moving again create unexpected tax consequences?
These aren’t necessarily reasons not to move — they are reasons to think beyond the move itself.
Don’t build a financial plan that only works in Spain
One of the biggest mistakes can be assuming that today’s circumstances will remain unchanged for the next 20 or 30 years.
A good financial plan should consider not only where you live today, but the possibilities that could affect you tomorrow.
That might mean understanding how your investments could be affected if you become tax resident somewhere else, ensuring your pension arrangements remain appropriate, or simply keeping enough flexibility in your finances to give you choices later.
Because ultimately, financial planning isn’t just about making your money work for you in your current circumstances.
It’s about making sure your money doesn’t prevent you from changing those circumstances.
The freedom to change your mind
Nobody moves to Spain expecting it not to work out.
But having a plan for the unexpected doesn’t mean you are expecting the worst.
It means giving yourself options.
Perhaps Spain will be your home for the rest of your life.
Perhaps it will be the place you spend the next ten years.
Or perhaps, one day, you’ll decide it’s time for another change.
The best financial plan isn’t necessarily the one designed around one particular destination.
It is the one that gives you the freedom to choose where your life takes you next.
Is your financial plan flexible enough?
If you live in Spain, it can be useful to step back and consider whether your current financial arrangements would still work if your circumstances or country of residence changed.
I help expats in Spain look at the bigger picture — from investments and pensions to tax planning, inheritance and long-term cashflow.
If you’d like to understand how flexible your financial plan really is, get in touch for an initial conversation.