
My wife, Chris, and I were having one of those meandering conversations recently— when she said something that’s been sitting with me ever since: “Do you think we’re in a trust recession?” She’s right, and once you start looking for it, you can’t stop seeing it.
Viewing posts categorised under: Mondaq
The Trust Recession
By Peter Brooke
This article is published on: 14th September 2026
14.09.26
Politicians treating inconvenient facts as just another opinion to argue with. Long-standing science backed issues dismissed despite the evidence of one climate shock after another. Deadly measles cases back to record levels just as trust in real data and expertise has quietly worn away.
Algorithms that don’t show you the truth, but more of whatever you already believe, until “the world is flat” starts to feel like a reasonable position to the person living inside that feed. None of this is exactly hidden any more. It’s just out in the open, and it’s exhausting.
I recently wrote, in The Intelligence Question, about why a human still needs to be in the loop even as AI reshapes financial planning.
It assumed something I want to go back and examine further:
“That you know which human to trust with that loop in the first place.”
Because this “trust recession” isn’t stopping at politics and social media. It’s already sitting inside financial services, quietly, and I’ve watched it play out over the years with clients — smart, successful, careful people who trusted very well-known financial institutions simply because they were well known, and found out later that “well known” isn’t the same as “on your side.”
So this isn’t really a piece about who you trust with your money. It’s about who you trust with your future.
Trust isn’t just a feeling, it’s an equation
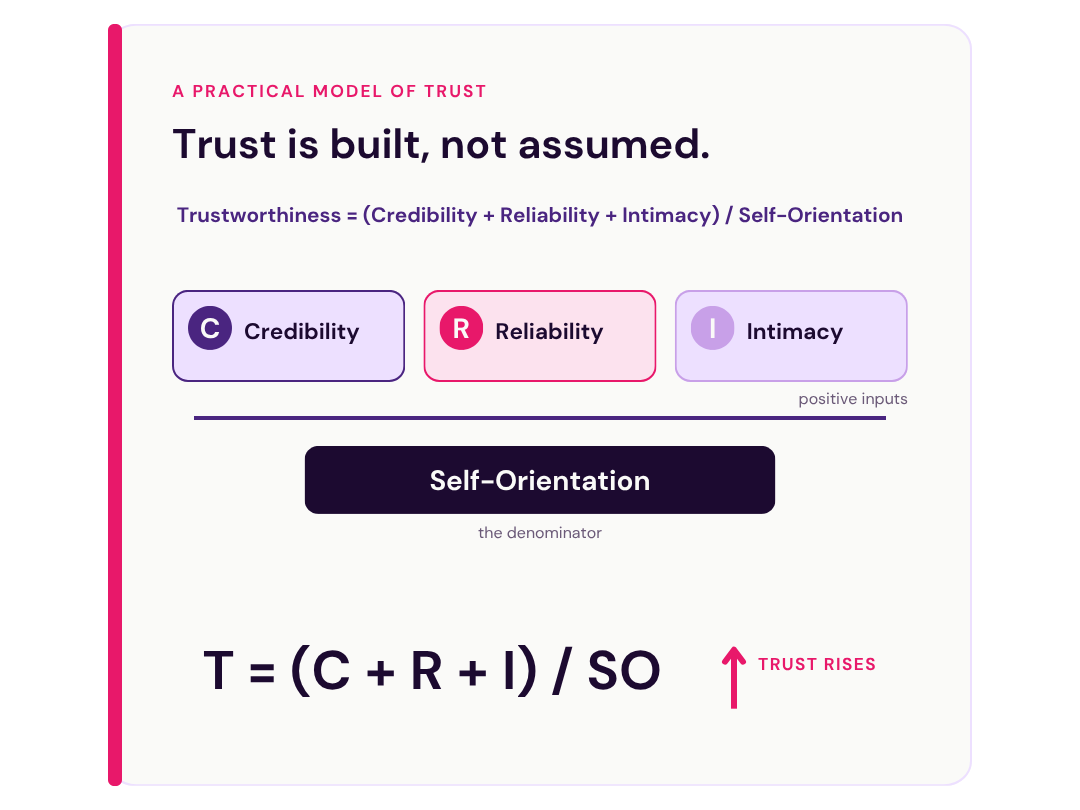
In 2000, in a book called The Trusted Advisor, Charles H. Green and his co-authors put a number on something that usually just feels like instinct. Their formula, still the cornerstone of Trusted Advisor Associates’ work is this:
-
Credibility: can I be believed — do I actually know what I’m talking about?
-
Reliability: do I do what I say I’ll do, when I say I’ll do it?
-
Intimacy: are you comfortable being honest with me, even about the things you don’t tell anyone else?
-
Self-orientation — the one that quietly challenges the other three — is whether I’m doing this for you, or for me.
It’s worth taking that last one seriously: the largest meta-analysis of human trust ever conducted — more than 300 studies, pulled together in 2023 — found transparency to be one of the strongest single predictors of whether someone is seen as trustworthy at all.
At Spectrum, we run this test too, by the way, before any fund manager, platform or provider gets anywhere near your money — regulation, transparency, track record, process!
Same four principles, just pointed at the people and companies we choose to work with.
Credibility: the one where questions matter more than answers
Anyone can claim to be credible — that’s exactly the trouble with a trust recession, self-declared expertise is cheap.
What actually proves it is different: whether you catch the thing nobody thought to ask about. A couple I was introduced to came to me with what looked like a straightforward question about selling a UK property one of them had owned for decades. Buried in the conversation was a detail neither thought was relevant: they’d married in France the year before the sale — which changed which country had the right to tax it, and by how much, eventually worth a six-figure sum in tax savings. Nobody asked me that question; I saw the connection because I’ve spent over twenty years looking out for exactly this kind of thing. That’s not something you can prompt your way into with AI.
Credibility isn’t just about any one story like this — it’s whether that pattern holds up, case after case, including the times I tell you plainly that I don’t know something and need to go and find out.
Reliability: the one I’m still working on
Reliability isn’t glamorous, and if I’m honest, it’s the one of these four I’d most like to get better at. I’m a human, not a system — I can’t promise to be perfect at it and when I do make mistakes I will endeavour to “own them” and put things right as efficiently as possible.
Reliability is the admin done properly and on time: fund switches processed without you having to chase them, withdrawal requests that don’t sit in a drawer, anti-money-laundering checks completed without three reminder emails. No drama, just doing the job properly, every time — and it’s precisely where I’m starting to use things like AI to try and stay on top of an ever-growing to-do list, rather than pretending it doesn’t grow.
What this technology hasn’t reached, and I don’t think it will any time soon, is the human part: knowing that a French wedding mattered to a British tax bill, or simply being the one who picks up the phone.
Intimacy: the one where you tell me things you don’t tell anyone else
I am flattered that clients continue to share things with me — plans, worries, numbers — some they wouldn’t necessarily volunteer to anyone else. I hold to an old adage here: seek first to understand before being understood, a principle I stand by completely. There’s no point building you a plan without the whole picture, and getting there depends on you trusting me enough to hand it over.
It’s also not only about how comfortable someone feels with me personally — it’s whether the systems gathering that information can be trusted too. I use tools like Cash Calc partly because of how seriously they take data security and GDPR, not just because they’re convenient. Trustworthy channels matter as much as a trustworthy person.
Self-orientation: the one where it’s fine to ask if I’m worth it
I run a business — and, happily, I get paid for the work, the same as any other professional you’d trust with something this important. What actually matters isn’t whether I’m paid, it’s how.
What matters is whether it’s transparent and fair on both sides: an explicit commission you’ve signed for, and a fixed annual charge you’ve agreed to, not something buried in small print, or hidden entirely. It’s why we changed our business model to explicit upfront commissions and a fixed annual charge instead: if your pot grows, my income grows with it, and if it doesn’t, so does the pressure on me to fix that. That’s alignment we’re both genuinely invested in, together.
Here’s the part worth sitting with, though: if you don’t actually know how your adviser is paid, that isn’t a neutral score in this equation. It’s close to the worst score. Opacity is exactly where self-interest hides. The client who’s never had a conversation about charges with their adviser or bank hasn’t found a low self-orientation ‘score’ — they’ve simply never been shown the real one.
How it all adds up
None of this means size, track record or reputation don’t matter — they do. Assets under management, years of experience, qualifications, regulatory status: all real, all worth checking. The mistake is treating any one of them as a shortcut — proof enough on its own that you don’t need to look any further. A recognisable name and a marble lobby are just one more thing to weigh, alongside credibility, reliability, intimacy and self-orientation, not a replacement for discounting them.
Here’s the test I actually use, on myself as much as anyone: would I let my grandma be advised by these people? Not are they big enough, not do they look the part — would I trust them with someone I love, and be comfortable with whatever came of it?
That’s not a size question. It’s a transparency question. The institutions and advisers worth your trust are the ones happy to have every part of that looked at closely. The ones that aren’t tend to hide behind the brand instead.
So, where do I score?
I’d genuinely like to know. I’ve put together a short, honest set of questions built around this same equation — follow this link and have a play with it, a couple of minutes at most. Answer anonymously if you’d rather, or put your name to it and be as open as you like — whichever gets you being honest is the right choice.
If you already work with me, I want to know where you’d score me, including anywhere I’m falling short. If you’re not yet a client, use it to think about whoever currently holds that role in your life.
If the answer comes back high, a referral to someone I might be able to help, is always the best compliment you can pay me — though I’d rather earn it than ask for it outright. If it comes back low, I’d rather hear that directly too.
Either way, get in touch — that’s how this actually works.
Why you should change adviser when you move to Italy.
By Gareth Horsfall
This article is published on: 11th September 2026
11.09.26
More and more UK clients are choosing to live, work or retire overseas. Italy has always been and continues to be a popular destination, and is attracting not just retirees but internationally mobile professionals, entrepreneurs and families.
If you have been working with a UK financial adviser, this could present a big challenge. You may have valued and trusted their advice for many years, but becoming resident in Italy can fundamentally change your financial planning requirements.
A different tax system, regulatory framework, pension rules and investment restrictions apply in Italy. Arrangements that might have been suitable for you when you when you were in the UK will need to be reassessed, once you move to Italy. The tax treatment of your pensions and investments will change, while local reporting requirements, succession laws and inheritance tax rules will introduce further complexity.
Without appropriate planning, you can face unexpected tax liabilities, unsuitable financial arrangements or difficulties accessing ongoing advice. Your adviser should have local financial and tax knowledge and consider your life in the future.
The importance of local knowledge
Planning across borders requires more than just a general understanding of international finance. It requires knowledge of the rules for residents of Italy and your country of origin.
The treatment of UK pensions, investment accounts, insurance-based arrangements and other assets differs considerably between the UK and Italy. A product that is tax-efficient in the UK, such as an ISA, does not receive the same tax treatment in Italy. You may also find that certain investment funds or financial institutions are unable or unwilling to retain you as a client when you change your residency to Italy.
Regulatory permissions are equally important. A UK adviser will no longer hold the permissions required to provide regulated advice once you become resident in Italy. Even if they promise continuing service by offering ‘management but not advice’, (which is not a viable solution) without local knowledge or access to appropriate solutions they can be inadvertently creating more problems for you in the future.
Advisers naturally want to protect your longstanding relationship, but they must also recognise the limits of their permissions and expertise. All advisers should operate in your best interests. Finding a regulated adviser in Italy and working on a plan with your UK adviser, together, to transition you over is the best solution.
A UK adviser should feel comfortable that they can introduce you to a company like The Spectrum IFA Group whom they can work collaboratively with. You gain access to relevant international and local expertise, while your relationship with your UK adviser is recognised and respected.
Your financial life does not stop at the UK border, but the rules governing your pensions, investments, taxation and estate planning can change considerably when you move overseas.
A UK based adviser may have spent many years earning your trust, and the relationship should not be placed at risk simply because you relocate.
As an adviser and the manager of The Spectrum IFA Group, I have over 20 years of relevant international and local Italian financial planning knowledge and created a list of trusted professionals that I can refer you to.
Planning before your move
The most effective time to consider the financial implications of your relocation to Italy is before you change residence.
Decisions made in the months leading up to a move can have a lasting effect on how your income, investments, pensions and estate are treated.
Early engagement gives us time to plan and utilise any tax benefits in your home country, any tax and time planning opportunities in the year of your move and then any possible Italian tax incentives after your move.
Addressing these matters if you have already become resident in Italy becomes harder or more expensive to resolve, but not impossible.
Supporting you in your move
Cross-border planning is rarely a one-off exercise. Your circumstances will evolve as you move to Italy, develop businesses, sell assets, receive inheritances or approach retirement.
You may decide to remain in Italy long-term, or decide to move back to the UK, or divide your time between different countries. Your financial arrangements must therefore remain flexible enough to respond to further changes in residence, regulation and personal objectives.
Regular reviews are essential. This allows us to consider whether arrangements remain appropriate, whether legislative developments have altered your position and whether your longer-term goals have changed.
Retirement Isn’t the Finish Line
By Matthew Green
This article is published on: 10th September 2026
10.09.26
It’s When the Financial Decisions Get Harder
For years, retirement is the destination.
You work. You save. You invest. You build your pension.
Then you retire.
Job done? Not quite.
In fact, retirement is often when the financial decisions become more important.
While you are working, your salary provides a regular income. If markets fall or you overspend, you have time to recover.
Once you retire, the equation changes.
Your investments may need to provide your income, potentially for 20, 30 or even 40 years.
So the question isn’t simply:
“How much money have I accumulated?”
It is:
“Will it be enough to support the life I want?”
What happens when things don’t go to plan?
Markets fall.
Inflation rises.
Unexpected expenses appear.
You live longer than expected.
Or one spouse dies before the other.
A retirement plan built around everything going perfectly isn’t really a plan.
This is why understanding your future cash flow can be just as important as choosing your investments.
Rather than simply looking at what you have today, you can model different scenarios:
- What if investment returns are lower?
- What if inflation remains high?
- What if you live to 95 or 100?
- What if you need a large amount of capital unexpectedly?
- What happens to your spouse if you die first?
You can’t predict the future. But you can prepare for different versions of it.

Your retirement isn’t a number
Someone with €500,000 may be financially comfortable.
Someone with €1.5 million may not be.
It depends on their income, spending, investments, tax position and the lifestyle they want to maintain.
That’s why retirement planning shouldn’t stop when you retire.
It’s when your wealth needs to start doing the job your salary used to do.
Is your retirement plan built around a number – or a lifestyle?
If you’re approaching retirement or already retired in Spain, don’t leave the answer to chance.
A personalised cashflow forecast can bring your financial future to life. It can show how your income, spending, investments and capital could develop over time—and, importantly, what happens if things don’t go exactly as planned.
You don’t need to predict the future. You need to understand it.
Are you receiving the advice you should be?
There are also many people who already have pensions, investments or other financial arrangements in place but haven’t had a meaningful review of their circumstances for some time.
Perhaps your adviser has retired or moved on. Perhaps you’ve been passed between advisers. Or perhaps you simply aren’t receiving the regular contact and ongoing advice you expected.
If that sounds familiar, you don’t necessarily need to start again.
A fresh review can help you understand what you currently hold, whether it remains appropriate for your circumstances and whether your financial arrangements are still aligned with your goals.
Your financial circumstances don’t stand still—and your financial plan shouldn’t either.
Whether you’re approaching retirement, already retired, or simply feel that your existing arrangements aren’t receiving the attention they deserve, a review can be a useful first step.
There is no obligation to change your existing investments or make any immediate decisions.
The starting point is simply a conversation about where you are today, what you want your money to achieve and whether your current arrangements are still working for you.
If you haven’t received retirement or pension planning advice in the past 12 months, it may be time to review where you stand. Get in touch to arrange an initial conversation and let’s look at whether your current arrangements are still working for you.
Because the earlier you identify a potential problem, the more options you have to do something about it.
Financial update France September 2026
By Katriona Murray-Platon
This article is published on: 9th September 2026

09.09.26
It’s September so it is back to school and back to work in France. It has been a very long and hot summer and for many people, it hasn’t been very restful. Many of you would have seen the news about were the major wildfires along the south-west coast which forced numerous residents to evacuate due to the smoke.
Fortunately, our town wasn’t evacuated, though the neighbouring town was not so lucky. Whilst most people have been able to return to their homes, the long process of rebuilding has only just begun for those who tragically lost their properties.
Over the summer, you should have received your tax statements either by post or on the impots.gouv.fr website. If you have less tax to pay than last year, this amount should have already been reimbursed to you in August. If, however, you have more tax to pay then your monthly payments (those that are made around the middle of the month) will increase as from the middle of September and any additional tax will be taken over four equal instalments at the end of September, October, November and December. If you don’t pay your tax automatically through your bank, you must pay the amount owed by 15th September. If you owe less than €300 of excess tax and you pay by direct debit, the amount will be taken on 25th September.
On 25th August 2026 the Prudential Assurance Company (PAC) board reviewed the Prufund Expected Growth Rates (EGR) as part of the Prufund regular quarterly review. The Prufund aims to grow their customers’ investments over the medium to long term (5 to 10 years) whilst buffering investors against short-term market volatility, using the unique established smoothing process.The Expected Growth Rate (EGR), the forward-looking element of the Prufund smoothing mechanism, remains unchanged this quarter. As regards the Unit Price Adjustment (UPA), the backward-looking part of the Prufund smoothing process, which is formulaic and non-discretionary, there was an upward UPA for the Prufund Cautious USD Dollar fund of 2.04%. Prufund is designed for the delivery of consistent returns over the medium to long term and although Prufund may lag behind a rapidly rising market, it protects in a falling market, demonstrating the consistency and robustness of Prufund in an ever more volatile world.
Despite troubling news headlines, August proved to be a surprisingly strong month for financial markets and balanced portfolios.
While geopolitical uncertainty and interest rate trajectories remain key concerns, second-quarter corporate earnings and Purchasing Managers’ Index (PMI) surveys indicate that the global economy continues to show resilience.
Notably, robust second-quarter results from US chipmaker Nvidia helped reassure investors following recent anxiety around the tech and AI sectors.
August’s performance reinforces the timeless investment wisdom: “time in the market” consistently beats “timing the market,” and maintaining a well-diversified portfolio remains the most effective strategy for managing volatility.
On 1st August the interest rates on the Livret A and LDDS savings accounts increased slightly from 1.5% to 1.7% to take into account the increase in inflation. The LEP account rate—available to households meeting specific income criteria – remains at 2.5%.
If you are planning energy-efficiency improvements for your property and wish to access government funding, you will need to consult the updated MaPrimeRénov’ guidelines, as the list of qualifying renovations was recently revised.
As we head into the final quarter of the year, it is an ideal time to consider your existing financial arrangements and your objectives for the months ahead. If you have any financial matters you would like to explore, please feel free to get in touch to arrange a review of your personal situation.
The Italian flat tax regime for HNW and the UK pension opportunity
By Gareth Horsfall
This article is published on: 7th September 2026
07.09.26
By now, the Italian flat tax regime for High Net Worth individuals has been running since 2017 but has probably seen more of an uptake in recent years. It has become more interesting for many HNW individuals to establish residency in Italy, even if you have business interests elsewhere and also when the flat tax rate has increased from €100000 in 2017 to €200,000 and from the 1st Jan 2026 increased to €300,000.
It is commonly thought that once accepted onto this tax regime that there is little financial planning to be done and you can largely leave your financial affairs untouched. This might well be the case, but it leaves a hugely unexplored financial planning opportunity by most advisers and accountants alike – liberation from UK pensions.
In the case of a UK pension (or most other country pensions), if you remain a resident in Italy after the end of the 15 years period, and you are over the age at which you can access your UK pension then any lump sums and / or income drawdowns from this pension will likely be subject to your progressive marginal income tax rates.
A lot depends on where you might be resident at the time of taking your retirement scheme benefits, but in most European countries, for example, the income from your UK pension will be taxed in Italy at the following rates: 23% rising to 35% and 43%)
On the other hand, if you were to generate income from a portfolio of assets or a highly tax efficient Investment Bond, you would only be charged capital gains and / or non-earned income tax (26% flat rate in Italy) on the assets and not on the whole income drawdown.
Therefore, if it were possible to convert your UK pension pot into a standard investment portfolio you could potentially free yourself of future income tax liabilities.
The good news is that it is possible with careful planning. Firstly, you would need to consider your future residency arrangements when taking benefits from the pension pot and assuming you are already above the UK pension access age (55 or 57 from 6th April 2028), then you could encash your UK pension and invest the proceeds in an investment portfolio, and in the process have created a much more tax efficient future income stream for yourself.
If you are on the HNW flat tax regime, you have established residency outside the UK and therefore under the double taxation treaty between the UK and Italy you only need to pay tax on UK pension income in your country of residence.
However, any encashment should be exercised with caution.
As a result of establishing residency outside the UK, the UK government will automatically apply a progressive emergency tax code to your encashment (20%, 40% and 45%) and assuming the UK pension pot is of sizeable value then this could mean an equally sizeable HMRC tax bill.
But, because you can prove residency outside the UK, you are covered by the UK /Italy double taxation treaty, and any tax will be refunded by HMRC on request of an NT (non-taxable) code.
However, there is a way to avoid paying tax to HMRC altogether, with a little careful planning.
If you think that might be of interest to you, please feel free to get in touch on
gareth.horsfall@spectrum-ifa.com or message me on +39 333 649 2356
Finance event Italy September 2026
By Gareth Horsfall
This article is published on: 2nd September 2026
02.09.26
FINANCIAL TALK, TAX PLANNING AND RAPHAEL IN UMBRIA – 24TH SEPTEMBER 2026
BOOK YOUR PLACE ON THE INVESTMENT, FINANCIAL PLANNING AND RAPHAEL IN UMBRIA TALK ON THE 24TH SEPTEMBER IN THE HEART OF THE NICCONE VALLEY.
If you haven’t registered, I would like to extend the invite to the event I will be hosting in the Niccone valley, Umbria on the 24th September.
On the 24th September in the gardens of the amazing Casa Nova, https://casanovaumbria.eu/, Niccone Valley, near Umbertide, I will be hosting an investment talk presented by Christopher Saunders from New Horizon Asset Management (Watch his video here on why we could be living through World War 3…) followed by some Italian financial and tax planning talk, and Q&A, from myself and to finish a wonderful talk from Dr Tom Henry on the life of Raphael in Umbria. All this within the stunning Niccole valley backdrop.
Will you make these Spanish tax mistakes in the next four months?
By Barry Davys
This article is published on: 31st August 2026
31.08.26
It is important to remember that the Spanish tax year runs from 1 January to 31 December.
As we approach the end of the Spanish tax year, I often see people making decisions that inadvertently increase their tax bill for the current year. If you do not want to pay more tax than necessary, here are some guidelines to help you reduce your tax bill.
What can increase your tax bill?
Sales and certain transfers of assets before 31 December may be taxed in the current tax year.
Sales
Some taxes are cumulative. If you continue selling assets that have increased in value, the tax rate will be based on your total gains for the whole year.
The tax rate will also depend on which Autonomous Community you are resident in. For example, the top rate of tax on gains in Catalonia is 30%.
If you think your savings, or perhaps that second property, have performed well, the result can look very different once the tax bill is taken into account.
Selling a second property, or selling your main residence if you are under 65 at the point of sale, can create a significant tax bill.
If you have only one property to sell but have already made significant gains from other sales this year, should you consider completing the property sale in the new tax year instead?
The profit from the sale of vested shares received through share option schemes can result in either income tax or capital gains tax. The constitution and terms of the share option scheme will determine which tax treatment applies.
We regularly see shares being sold soon after they have vested. If you have share options vesting, you can reply to this email to find out more and discuss whether you should sell in this tax year or the next.
Transfers
Making transfers of assets between people before the end of the year can also increase your tax bill. These transfers can include:
- Gifts to individuals who are tax resident in Spain
- Gifts to non-resident individuals involving assets located in Spain
- Transfers of non-EU pensions (for example, UK pensions) into European-based pension schemes
A pension transfer can potentially be taxed on the whole transfer value by adding it to all your other income. The result can be a very significant tax bill — potentially tens of thousands of pounds on a relatively modest pension.
Get specialist advice before you act
To ensure you receive the best possible support and advice, we can also call upon lawyers, who we have worked with 14 years, as needed.
What you should do in relation to a sale or transfer will depend on your personal circumstances. There is no one-size-fits-all answer.
To avoid making costly mistakes, you are welcome to book a call at a time that is convenient for you using my online booking system. You can tell me about your personal circumstances, and we can then advise you on what you should consider doing.
The right course of action will follow from there.
What If Spain Doesn’t Work Out?
By Matthew Green
This article is published on: 28th August 2026
28.08.26
Moving to Spain can feel like the final destination.
For many expats, the plan is simple: sell up, move abroad, enjoy the lifestyle and build a new life in the sun.
But what happens if, somewhere down the line, Spain isn’t quite what you expected?
Perhaps your circumstances change. Your children move elsewhere. Your priorities change. You decide you want to be closer to family. Or maybe you simply discover that another country, or even your home country, suits you better.
It is something few people consider when they first move abroad.
Your financial life needs to be flexible too
When you move countries, your financial affairs can become increasingly complicated.
You may have pensions in one country, investments in another, property in Spain and bank accounts spread across several jurisdictions.
Then, if you decide to move again, the questions start to appear:
What happens to my investments?
What happens to my pension?
Will I still be able to hold the same investments if I leave Spain?
What happens to my tax position?
Will moving again create unexpected tax consequences?
These aren’t necessarily reasons not to move — they are reasons to think beyond the move itself.
Don’t build a financial plan that only works in Spain
One of the biggest mistakes can be assuming that today’s circumstances will remain unchanged for the next 20 or 30 years.
A good financial plan should consider not only where you live today, but the possibilities that could affect you tomorrow.
That might mean understanding how your investments could be affected if you become tax resident somewhere else, ensuring your pension arrangements remain appropriate, or simply keeping enough flexibility in your finances to give you choices later.
Because ultimately, financial planning isn’t just about making your money work for you in your current circumstances.
It’s about making sure your money doesn’t prevent you from changing those circumstances.
The freedom to change your mind
Nobody moves to Spain expecting it not to work out.
But having a plan for the unexpected doesn’t mean you are expecting the worst.
It means giving yourself options.
Perhaps Spain will be your home for the rest of your life.
Perhaps it will be the place you spend the next ten years.
Or perhaps, one day, you’ll decide it’s time for another change.
The best financial plan isn’t necessarily the one designed around one particular destination.
It is the one that gives you the freedom to choose where your life takes you next.
Is your financial plan flexible enough?
If you live in Spain, it can be useful to step back and consider whether your current financial arrangements would still work if your circumstances or country of residence changed.
I help expats in Spain look at the bigger picture — from investments and pensions to tax planning, inheritance and long-term cashflow.
If you’d like to understand how flexible your financial plan really is, get in touch for an initial conversation.
Valencian community declares more tax cuts for residents
By Robin Beven
This article is published on: 27th August 2026
27.08.26
If you live in or are thinking of moving to Valencia, Alicante, or Castellón, there’s good news: the regional government has approved fresh tax cuts that could save you money.
Building on last year’s changes, the new rules (set out in Law 5/2026) trim income tax, double the wealth tax exemption, and make inheritance and gift tax more generous.
Income Tax Going Down
In Spain, your income tax bill combines a national rate and a regional rate. The Valencian government has cut its portion, which means lower overall rates for residents.
What’s changing?
The lowest rate drops from 18.5% to 18.3% in 2026, then to 18.2% in 2027
The top rate falls from 54% to 53.85% in 2026, then to 53.75% in 2027
Most bands in between will see similar small reductions
These cuts apply to wages, pensions, and rental income. Savings and investment income rates are set nationally and haven’t changed.
Valencian Income Tax Rates (Combined State + Regional)
| Income Band | Previous Rate | New 2026 Rate | 2027 Rate |
| Up to €12,000 | 18.5% | 18.3% | 18.2% |
| €12,000 – €12,450 | 21.5% | 21.2% | 21.1% |
| €12,450 – €20,200 | 24% | 23.7% | 23.6% |
| €20,200 – €22,000 | 27% | 26.7% | 26.6% |
| €22,000 – €32,000 | 30% | 29.6% | 29.5% |
| €32,000 – €35,200 | 32.5% | 32% | 31.9% |
| €35,200 – €42,000 | 36% | 35.5% | 35.4% |
| €42,000 – €52,000 | 38.5% | 37.9% | 37.8% |
| €52,000 – €60,000 | 41% | 40.4% | 40.3% |
| €60,000 – €62,000 | 45% | 44.4% | 44.3% |
| €62,000 – €72,000 | 47.5% | 46.9% | 46.8% |
| €72,000 – €100,000 | 49% | 48.6% | 48.5% |
| €100,000 – €150,000 | 50% | 49.85% | 49.75% |
| €150,000 – €200,000 | 51% | 50.85% | 50.75% |
| €200,000 – €300,000 | 52% | 51.85% | 51.75% |
| Over €300,000 | 54% | 53.85% | 53.75% |
Rates shown are combined state and Valencian regional rates
Wealth tax allowance doubles
This is the big one for wealthier residents. The Valencian wealth tax exemption is jumping from €1 million to €2 million per person starting 31st December 2026.
What does this means?
A couple could shield €4 million combined through personal allowances
Plus up to €600,000 extra for their main home (€300,000 each if jointly owned)
That’s potentially €4.6 million protected from wealth tax
One catch: Spain’s national “Solidarity Tax on Large Fortunes” still kicks in if your net assets top €4 million, so very wealthy individuals may still face some wealth-related taxes.
Inheritance and Gift Tax improvements
The rules for passing assets to family members are getting more flexible:
Family business relief expanded
The 99% tax relief for family businesses now covers more relatives
Previously limited to direct family; now extends to collateral relatives up to fourth degree (including first cousins)
This helps keep family businesses intact across generations
New tax credits for wider family
25% credit on inheritances and gifts between siblings, aunts, uncles, nephews, and nieces
Rising to 50% from June 2027
Bottom Line
The Valencian Community is becoming increasingly tax-friendly, especially for wealthier residents and families planning to pass on assets.
That said, lower rates don’t automatically mean a lower tax bill. If you’re a UK national living in Spain, you still need to navigate:
- Spanish income, wealth, and inheritance taxes
- UK Inheritance Tax (IHT)
- Cross-border UK pension and investment rules
- Property ownership in multiple jurisdictions
Tax rules in both Spain and the UK are forever changing – it’s worth reviewing your arrangements to make sure you’re not paying more than necessary.
Key dates to remember!
Income tax cuts: January 1, 2026 (with further cuts 1st January, 2027)
Wealth tax exemption increase: 31st December, 2026
(applies to 2026 tax returns filed in 2027)
Inheritance tax credit increase: June 2027
The future of financial markets, AI, continuing wars and financial and tax planning your life in Italy
By Gareth Horsfall
This article is published on: 22nd August 2026
22.08.26
FINANCE – ART – GARDENS
A TALK IN THE NICCONE VALLEY, UMBERTIDE
24th September 2026
10.30am to 14pm.
Morning beverages and lunch included.
During my time spent trying to keep cool, my mind turned once again to upcoming events this year. Conversations with clients are almost always lurching around all the current potetial threats – from AI, continuing wars, the US midterms and a future which seems more uncertain than ever. I can almost feel everyone’s anxiety, and so I thought, let’s talk about them in person and try and put our minds at ease, before the winter period sets in.
So, I decided to set up an in-person talk like no other.
A talk on the future of financial markets, AI, continuing wars and financial and tax planning your life in Italy
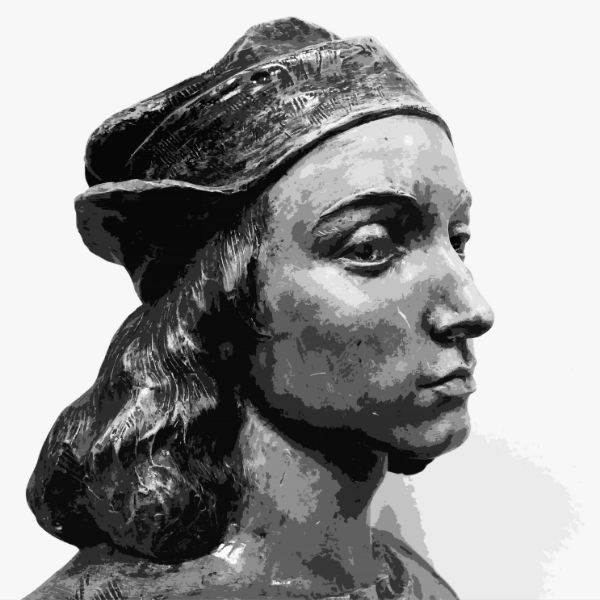
All this mixed with a more ‘soothing’ art history talk on the renaissance artist Raphael and his life in Umbria, presented by Dr Tom Henry – Emeritus Professor of Art History at the University of Kent on the artist Raphael in Umbria.
All this, in a stunning hillside location, Casa Nova (www.casanovaumbria.eu) nestled in the Niccone Valley, Umbria.
First up with be a financial markets talk with Chris Saunders of New Horizon Asset Management
AI, War & Markets: Investing in a Divided World
You can watch a very interesting 2 minute video by clicking on the link below👇, of Chris explaining why we are very likely living through World War 3. Not a world war as we know it historically, but one which may be taking place right before our eyes.
**WHY WE COULD BE LIVING THROUGH WORLD WAR 3**
New Horizon Co-Founder Chris, will discuss:
- The global AI race and the opportunities it may create
- Why volatility is likely to remain a feature of investing
- Where the winners and losers may emerge
We celebrate 15 years of The Spectrum IFA Group in Italy in 2026.
In my time since I set up the branch in Italy, I have learned a few Italian financial planning tips and tricks along the way.
I will make a short talk and then throw questions over to you in a Q&A.
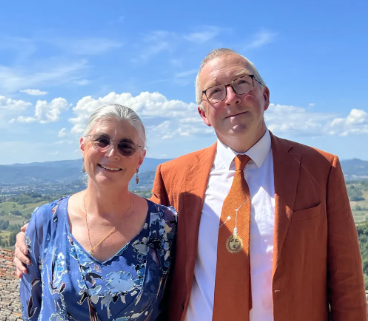
Dr Tom Henry and his wife, Patricia Robertson
And finally, to eradicate any anxieties about the future, there will the talk by Dr Tom Henry – Emeritus Professor of Art History at the University of Kent on the artist Raphael in Umbria.
Formerly Professor of History of Art at the University of Kent and now Emeritus Professor; Lecturer in Art History at John Cabot University. Cavaliere dell’Ordine della Stella d’Italia. He was Director of the University of Kent’s School of Classical and Renaissance Studies in Rome, and is a curator and expert on Raphael, Signorelli and Central Italian painting, with extensive experience of working in Italy. He speaks regularly at conferences in Italy (including at Villa I Tatti and British Institute, Florence; Accademia di San Luca, Rome; Bibliotheca Hertziana, Rome; Villa Wolkonsky, Rome; Museo di Capodimonte, Napoli; and in the Vatican Museums) as well as abroad (Albertina, Vienna; Courtauld Institute of Art, London; Cleveland Museum of Art; National Museum of Western Art, Tokyo; Musée du Louvre, Paris; Metropolitan Museum of Art, New York; National Gallery of Art, Washington).
And you get to see all this in the amazing country hillside garden setting in the Niccone valley, curated by Trish, Tom’s wife, a passionate gardener and lover of nature, and who also cultivates and sells irises.
Trish will also be avaialble for any gardening questions you might have!
Due to the nature of the event, I only have space for a maximum of 30 participants, so if you are interested in attending and blocking your place then please let me know as soon as possible.
Please contact my assistant, Silvia Loi on silvia.loi@spectrum-ifa.com and book your place.
Let’s get out and get some fresh autumnal air after a seemingly endless hot summer!