Tel: +34 93 665 8596 | info@spectrum-ifa.com | LinkedIn Facebook

Viewing posts categorised under: Spain

Inherited a UK pension while living in Spain?

By Chris Burke
This article is published on: 29th October 2026

29.10.26

Why a Beneficiary SIPP could save you a very large tax bill

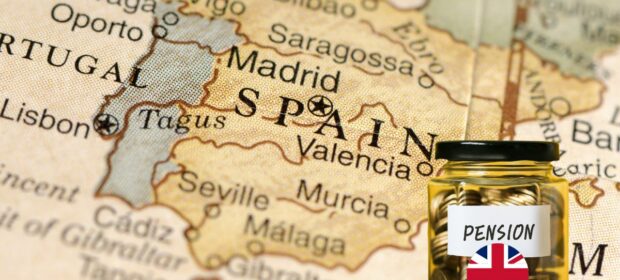
When a loved one passes away, dealing with their pension is rarely the first thing on your mind. For British expats in Spain, though, the decision you make about an inherited UK pension can be one of the most financially significant you will ever face. Receive this the wrong way and you could hand a large share of it to the Spanish tax authorities; handle it well and it can keep working for you, and for your family, for decades.

What is a beneficiary SIPP?

A beneficiary SIPP is a pension account that lets you keep an inherited UK private pension invested ‘as a pension’, instead of ‘cashing it in’. Depending on the provider, it can also be called beneficiary drawdown, inherited drawdown or a beneficiary’s flexi-access drawdown plan.

Once the pot is in your name as beneficiary, you can:

  • Leave it invested as a pension, where gains are not taxable until accessed
  • Choose your own investments/strategy alongside financial advice
  • Take income or lump sums as and when you wish, rather than all at once
  • Nominate your own beneficiaries, so that the pot can be passed on again (successor drawdown)
  • ONLY a non-UK regulated financial adviser can help you set this up if you are a Non-UK tax resident

You are not forced to take the money; you choose when and how much to take. Most importantly, there is normally no income tax to pay on receiving the inherited pension this way.

inheritance

The trap: taking the inheritance as a lump sum

Many beneficiaries living in Spain cash in the beneficiary pension and take the entire amount as a ‘lump sum’. It feels simple and final. But Spain taxes residents on their worldwide income, and a large lump sum arriving in a single tax year can be taxed in Spain as income. It is added to your other income and taxed at progressive rates that, at the top end, reach 47% nationally, and higher in some regions once regional rates are applied.

Because you are in essence receiving this money ‘all at once’, the whole sum lands in one tax year, pushing you up into the highest tax bands. On a six-figure pension pot, the difference between the top rates and a carefully managed alternative can run to tens of thousands of euros.

Depending on the inheritance tax the ‘Estate’ paid in the UK (a deceased person’s estate, not the individual, is taxed in the UK) and the inheritance tax rules in Spain, there may already have been a substantial amount of tax to pay on inheriting the pension. By paying even more tax on receiving this as a one-off lump sum payment, rather than setting up a ‘beneficiary pension’, the percentage of tax paid could end up being the majority of the pension amount you inherited. See the example below for an inherited UK pension for a Spanish tax resident (not regionally adjusted):

Comparison Income tax paid Spain Net received
A: Taking as a lump sum £78,947* £121,053*
B: Setting up as a beneficiary pension, taking the money over a 10-year period with no growth £26,430* £173,570*
C: Setting up as a beneficiary pension, taking the money over a 10-year period with 4% growth £39,084*  £207,497*

On top of all this, if you are a non-UK tax resident and you haven’t paid any tax in the UK for a while, you will most likely be taxed on this money through an ‘emergency’ tax code by HMRC at a rate of 40%, to make matters even worse.

Why a beneficiary SIPP can be so much more efficient

  1. You control the timing. Leaving the pot as a pension means no lump sum triggers a large Spanish tax charge in one year. You can draw down gradually, in amounts that keep you in lower tax bands, and plan around other income, retirement or a move.
  2. Tax-free growth inside the pension. While the money stays invested, any gains within the pension are not taxed. You are not paying annual tax on dividends, interest or gains on the pot while it grows.
  3. Potentially no UK tax on the way out. Where the pension holder died before age 75, withdrawals from an inherited UK pension are generally free of UK income tax, provided the payment is within the available limits (the Lump Sum and Death Benefit Allowance, currently £1,073,100). Where death occurred at 75 or over, withdrawals are taxed in the UK at the beneficiary’s marginal rate, which is another reason to take advice before you act.
  4. Flexibility for the next generation. Unused funds can often be passed on again, although the relevant inheritance tax in your Spanish region will also need to be taken into account.

The right outcome for you depends on your circumstances, your region of residence, and the Spanish tax treatment of the death benefit itself, which we would always confirm with specialist Spanish tax input before any decision.

The April 2027 UK pensions inheritance tax change you need to know about

From 6 April 2027, the UK is bringing most unused pension funds and death benefits into the scope of inheritance tax. The change is confirmed in the Finance Act 2026. In some cases, beneficiaries could face inheritance tax on the pot and income tax on withdrawals. Where the pension holder dies after that date, the structure and timing of what you inherit matters even more. If you are a pension holder yourself, it is also a good moment to review your own death benefit nominations.

Why speak to a specialist?

Cross-border pensions sit where two tax systems meet, and getting it wrong is expensive. Before you do anything with an inherited UK pension, you should consider:

  • The age of the deceased at death, and what this means for UK tax
  • Whether the pension is a UK scheme, and which provider and type of plan holds it
  • Your Spanish tax residency and region
  • How to draw income in a way that is tax efficient in Spain
  • Your own estate planning, on both sides of the border

I work with British expats across Spain on exactly these questions, from International SIPPs to Spanish tax compliance and inheritance planning. If you have inherited a UK pension, or expect to, please get in touch before you request a payment from the provider. Once a lump sum has been paid out, it cannot be undone.

* Tax calculations are estimates and intended for general guidance only.

Living in Spain with US (United States) Assets/Ties?

By Chris Burke
This article is published on: 13th October 2026

13.10.26

Since 2010, I have worked with Americans who have built their lives in Spain: US citizens, passport holders and green card holders, many with decades of savings in brokerage accounts, IRAs (Individual Retirement Accounts) and 401(k)s (employer-sponsored retirement plans, named after section 401(k) of the US Internal Revenue Code). The same pattern comes up in almost every first meeting. The portfolio is sound, but the structure around it was designed for someone living in Ohio or Texas, not Barcelona or Valencia.

If your investable assets are $1.3 million or more, that gap deserves attention. The problem is rarely performance. It is usually tax drag, compliance risk and an advisory relationship that no longer fits your circumstances.

The US Person's Problem: Two Tax Systems, One Portfolio

The US Person’s Problem: Two Tax Systems, One Portfolio

As a US person, you remain subject to US tax on your worldwide income wherever you live. Once you are Spanish tax resident, Spain taxes you on your worldwide income as well.

The US-Spain tax treaty and the foreign tax credit system are designed to prevent genuine double taxation, but they do not remove the complexity. They simply mean every decision must be tested against both regimes.

Some of the most common issues I see:

  • US custodians that cannot, or will not, serve you. Many US brokerages restrict or close accounts once a client’s address moves to Spain. Clients are then left with orphaned accounts or a patchwork of unsuitable alternatives.
  • The wrong funds in the wrong place. Most European-domiciled funds and ETFs (Exchange-Traded Funds) are treated by the IRS (Internal Revenue Service, the US tax authority) as Passive Foreign Investment Companies (PFICs), with punitive tax treatment and onerous reporting on Form 8621. Many US persons in Spain hold exactly these products without realising.
  • Mismatched gains. Spain calculates gains in euros and the US in dollars. Currency movements can create a taxable gain in one country and a loss, or nothing at all, in the other. Portfolio turnover that looks harmless on a US statement can produce unwelcome Spanish tax bills.
  • Retirement accounts that Spain does not treat as the US does. IRAs, 401(k)s and Roth accounts (retirement accounts funded with after-tax money) each need individual analysis. Contribution, growth and withdrawal treatment can differ between the two countries, and getting the sequence of withdrawals wrong can be expensive.
Reporting: Where Good Portfolios Get into Trouble

Reporting: Where Good Portfolios Get into Trouble

Compliance is the area where the stakes are highest, because errors can attract penalties well beyond any investment loss.

As a US person resident in Spain, you may need to deal with some or all of the following:

  • FBAR (Report of Foreign Bank and Financial Accounts; FinCEN 114, where FinCEN is the Financial Crimes Enforcement Network): required if the combined value of your non-US financial accounts exceeded $10,000 at any point in the year.
  • FATCA (Foreign Account Tax Compliance Act) Form 8938: for US persons living abroad, reporting thresholds are higher than for those at home, but still easily exceeded at this level of wealth.
  • Form 8621: for each PFIC (Passive Foreign Investment Company) holding, if you have any.
  • Your annual US return (Form 1040) with foreign tax credit claims, alongside your Spanish return (Modelo 100).
  • Modelo 720: Spain’s declaration of overseas assets above €50,000 per category. Your US accounts count as foreign assets from the Spanish perspective, so a US brokerage account or IRA can bring this obligation into play.
  • Spanish Wealth Tax: depending on your region and the size of your estate, this can apply and needs to be considered with your reporting.

The two countries do not use the same forms, deadlines or definitions. A portfolio that is reportable in one place and invisible in the other is a common cause of problems. My role is to make sure your investments are structured so that reporting is straightforward, accurate and repeatable, working alongside your tax preparer rather than replacing them.

A Disciplined, Cross-Border-Aware Investment Approach

For clients at this level, I work with a US wealth manager whose process is built around long-term capital preservation and growth rather than short-term market activity. The philosophy behind the approach is one I find well suited to expatriate families:
• Goals first. The portfolio is designed around what the money has to do: fund your Spanish lifestyle, provide for your spouse, and pass wealth to the next generation. Benchmarks come second.
• Genuine diversification. Portfolios are spread across global markets, asset classes and strategies, with an emphasis on quality and resilience through varying market conditions.
• A long-term, patient mindset. The manager takes a multi-generational view of wealth, which suits clients who think in decades.
• Discretionary, professional management. Day-to-day decisions are made by an experienced investment team within an agreed framework, and you are not left to react to headlines.
• Tax-aware implementation. Holdings are selected and managed with the realities of dual US-Spanish taxation in mind, including fund selection, realisation of gains and currency effects.
• Clear, consistent reporting. You receive transparent statements that support your US and Spanish filings, so your accountant is not reconstructing figures each spring.

My own role is to sit between you, the investment team and your tax advisers. I deal with the Spanish side of the planning, coordinate the compliance workflow, and review your position regularly as your life, the markets and the legislation change.

Question

Is This for You?

My approach is best suited to people who:

  • are US citizens, passport holders or green card holders living in Spain,
  • hold $1.3 million or more across investment accounts, IRAs and 401(k)s,
  • want a single, coordinated strategy rather than a collection of accounts that do not speak to each other, and
  • value careful compliance as highly as investment returns.

The First Step

I offer an initial, no-obligation conversation to review your current holdings, your reporting position and your objectives. In most cases I can tell you quickly whether your present arrangements are working well, and where they may be costing you more than you realise.

Click here to read independent reviews on Chris and his advice HERE

You can arrange an initial consultation at a time convenient to you, and to explore your situation click HERE to view my diary.

If you would like any more information regarding any of the above, or to talk through your situation initially and receive expert, fact-based advice, don’t hesitate to get in touch with Chris.

Your retirement journey shouldn’t be a bumpy ride

By Tom Worthington
This article is published on: 12th October 2026

12.10.26

Why consistency matters when your investments pay the bills

If you are approaching retirement, or already using your investments to top up your retirement income, the returns you receive serve a critically important purpose – helping to provide financial security for the rest of your life.

That might mean the weekly shop, flights to see family or the freedom to say yes to a holiday without worrying about what it does to next year’s income. This is the reader I have in mind: someone who has worked hard to build savings and now wants to understand how to make them last.

My career has taken me from advising expatriates to working in investment management, and back to personal advice here in Mallorca. Those roles look at the same money from different angles. A manager considers how a portfolio is invested; an adviser also has to consider what happens when its owner needs to spend it.

For me, that connection is the important part. A good investment on paper still has to fit the person living with it. If the income is needed for everyday expenses, the bumps along the way deserve as much attention as the headline return.

disciplined fund manager

Why a higher average can leave you with less

Suppose you invest €300,000 for ten years and take nothing out. One hypothetical investment earns 7% every year. Another alternates between gaining 20% and losing 5%, giving it a simple average annual return of 7.5%.

The second sounds better. Yet the steady 7% finishes at roughly €590,145, while the alternating returns produce about €577,624. The supposedly lower return leaves you approximately €12,521 better off.

The reason is that each year’s gain or loss applies to a different balance. A 20% gain followed by a 5% fall turns €100 into €114, not €115. Repeat that pattern and the difference builds up.

This is a mathematical illustration, not an investment offer. No market-based fund can promise 7% every year. The figures exclude fees and taxes, and neither percentage is a forecast.

There is also a distinction worth keeping in mind: a published compound annual return already allows for those ups and downs.

If one investment genuinely compounded at 9% and another at 6% over the same period, with nothing paid in or withdrawn, the 9% investment of course grows more. My point is to look carefully at what the quoted number actually measures.

What changes when you start taking income

Now imagine a couple retiring to Mallorca with €300,000 in savings. Their pension income covers most of the essentials, but they want another €15,000 a year from savings for the rest. This is a hypothetical situation, rather than a client case study, but consider this important point.

They might see €15,000 additional annual income as €1,250 a month towards enjoying retirement. Their investment portfolio, however, has to support these payments through difficult years as well as good ones. Their living expenses will not reduce just because markets have fallen.

Using the same €300,000 starting balance, suppose €15,000 is withdrawn at the end of each year. If the investment falls 20% in year one and gains 30% in year two, €277,500 remains after both withdrawals. Reverse those returns, with the gain first, and €285,000 remains.

That is a €7,500 difference despite identical percentage returns and the same €30,000 taken out. Without withdrawals, both would finish at €312,000.

The technical name for this exposure to uncertainty is sequence-of-returns risk. In everyday language, taking money out after a market fall leaves less invested to benefit from the recovery. The timing of bad years can therefore matter a great deal once your savings are being used to pay the bills.

For our hypothetical couple, I would want to explore how much of that €15,000 they really need, what could be reduced temporarily, and what other accessible savings they have. Those answers help shape a withdrawal plan that is more practical and valuable than an unrealistically optimistic approach to retirement.

Reliability

What I mean by consistent management

I am not looking for a manager who claims markets will never fall. I want an approach I understand and can explain: what the portfolio owns, why it owns it, how risk is managed and what it costs.

Consistency means sticking to a sensible investment process through difficult conditions. It includes spreading investments appropriately, keeping enough liquidity to meet withdrawals and avoiding risks that do not fit the client’s circumstances. It does not mean avoiding every loss or guaranteeing an income.

For clients of mine, the question I want an investment plan to answer is whether it supports the life they want to lead. Someone investing for twenty years without needing the money has different choices from someone drawing on it next month. The same fund could suit one and be inappropriate for the other.

That is also why I would not select a manager on last year’s performance alone. I want to understand how the strategy performed in difficult periods, whether the risk/reward balance is appropriate, and what the investor keeps after charges.

A monthly payment is not necessarily a profit

A regular payment into your bank account can feel reassuring. But receiving 5% a year does not necessarily mean your investment has earned 5%. Some of the payment may be your own capital coming back to you.

There is nothing automatically wrong with spending capital in retirement. You may have saved it for exactly that purpose. What matters is understanding the effect on the money remaining and how long it may need to last.

I think of it like a wine rack: taking out a bottle every Friday becomes a routine, but it does not mean the rack is producing wine.

With investments, that distinction can be less obvious. I want you to understand where your income comes from, how charges affect it and what happens if returns disappoint. A withdrawal plan also needs reviewing as your spending pattern, health or family circumstances change.

planning for retirement

A plan you can live with

Living in Mallorca gives me a personal connection to the practical side of advice for people abroad. The plan has to work where you live and in the currency you spend. If your pension arrives in pounds but your bills are in euros, exchange rates will affect how far your income goes.

There is a human side to investment risk too. It is easy to say you are comfortable with a fall when markets are rising. It may feel different when the valuation drops and you still need to pay your bills next month.

I would rather explore that before the difficult year arrives. How would a fall affect your spending? Would you feel pressure to sell investments? Could accessible reserves give you breathing space? The answers matter more than a reassuring label on a questionnaire.

Being too cautious has its own cost. Cash can provide useful security for nearer-term spending, but inflation reduces what it buys over time. Retirement may last decades, so the plan needs to balance today’s comfort with the growth that may be needed later.

Bringing it back to your retirement

The first question I ask is what you need your money to do. Cover essential bills? Fund travel? Help children? Leave something behind? Each answer affects how much uncertainty you can afford and how the investments should be managed.

From there, we can consider suitable investments, costs, accessible reserves and a realistic withdrawal level. Those pieces need to work together, with room to adjust when life changes. The €15,000 in the illustration is not a recommendation that everyone can safely withdraw 5%.

You do not need to become an investment specialist to have that conversation. You should be able to understand the plan, the risks involved and why it suits you.

That is what I want personal advice to achieve. You worked hard to build your savings. The aim is to help you use them with greater confidence, leaving more time to enjoy the life you have worked towards.

Should I Move My Investments Before Moving to Spain?

By Matthew Green
This article is published on: 6th October 2026

06.10.26

You are planning to move to Spain.

You have investments, savings and perhaps pensions that you’ve built up over many years.

So a question often comes up:

Should I change everything before I move?

Should you sell your investments? Move your money? Restructure your portfolio? Close old accounts? Or simply leave everything as it is?

There isn’t one answer that works for everyone.

But there is one important point: the timing of some financial decisions can matter when you are changing tax residence.

Don’t assume everything needs to change

One of the biggest mistakes people can make when moving countries is assuming that all their existing financial arrangements need to be changed immediately.

They don’t.

You may have investments held in the UK, US, Europe or elsewhere and continue to hold them after moving to Spain.

The important question isn’t simply:

“Where is my money?”

It is:

“How will my existing arrangements work once I become resident in Spain?”

That can depend on the type of investment, where it is held, your tax residence, your future plans and how you intend to use the money.

What happens

Should I sell my investments before moving?

This is where things can become complicated.

Imagine you have built up a substantial investment portfolio over many years and it has significant unrealised gains.

You could sell everything before moving and start again once you are resident in Spain.

But selling may itself create tax consequences, transaction costs and investment risks.

You may also end up sitting in cash while you decide what to do next.

On the other hand, there may be circumstances where reviewing or restructuring investments before a move makes sense.

The important point is that selling everything simply because you are moving country isn’t automatically the right answer.

The timing should be considered as part of a wider financial plan.

What happens if I leave my investments where they are?

Moving to Spain doesn’t necessarily mean your investments have to be physically moved to Spain.

However, becoming Spanish tax resident can change how your worldwide assets and investment income are treated.

For example, income and gains from investments held outside Spain may still need to be considered under Spanish tax rules, and certain foreign assets can also create reporting obligations depending on the circumstances.

This is why it is important to understand the position before becoming resident rather than discovering the consequences afterwards.

The investment may not need to move.

But your understanding of it probably does.

Additional tax traps and planning points

What about pensions and tax-efficient accounts?

This is another area where people can make decisions too quickly.

You may have accumulated pensions, ISAs, 401(k)s or other tax-efficient arrangements in the country you are leaving.

Their treatment doesn’t necessarily remain the same simply because they were tax-efficient where you previously lived.

That doesn’t mean they should automatically be closed, transferred or sold.

It means you need to understand how they fit into your new circumstances.

In some cases, doing nothing may be perfectly reasonable.

In others, the move may be a good opportunity to review the arrangement.

What about currency?

Currency is another consideration that can easily be overlooked.

If your future life is going to be based in euros, but much of your wealth remains invested in pounds, dollars or another currency, you are potentially introducing currency exposure into your financial plan.

That isn’t necessarily a bad thing.

If you have future income or expenditure in another currency, holding assets in that currency may be perfectly sensible.

But it should be intentional rather than accidental.

A move to Spain is therefore a good opportunity to ask:

What currency will I actually need my money in over the next 5, 10 or 20 years?

moving to Spain

What should I review before moving?

Rather than asking whether you should move your investments, I think there are better questions to ask.

Your investments

Are they still suitable for your objectives, timeframe and attitude to risk?

Tax

How could becoming Spanish tax resident affect your investment income and gains?

Existing arrangements

Can your current providers continue to service you once you are resident in Spain?

Currency

Do your investments and future spending requirements match the currencies you will actually use?

Pensions

How do your pensions fit alongside your other investments and future retirement income?

Estate planning

Will your existing arrangements still make sense if you die while living in Spain?

Future plans

Are you planning to stay in Spain permanently, or could you eventually return to your previous country?

Liquidity

How much money will you actually need for the move, property purchase, lifestyle and unexpected costs?

These questions can be far more useful than simply deciding whether to “move” your investments.

risk

The danger of making decisions too early

There is another side to this.

People sometimes make major financial changes because they have heard that something “should” be done before becoming resident in Spain.

But a decision that is appropriate for one person may be completely inappropriate for another.

Selling investments, transferring pensions or restructuring a portfolio can have consequences.

So can doing nothing.

The objective shouldn’t be to make as many changes as possible.

It should be to make the right changes at the right time.

A better way to approach the move

If you’re planning to move to Spain, I would start the financial review before you become resident.

Make a list of your:

  • Investments
  • Pensions
  • Savings
  • Property
  • Existing tax-efficient arrangements
  • Income sources
  • Currencies
  • Estate-planning arrangements

Then consider how they will work together once your life is based in Spain.

You may decide that some things should change.

You may decide that others are better left exactly where they are.

Either way, you will be making the decision because it fits your circumstances — not simply because you’ve moved country.

Moving to Spain doesn’t mean starting again

Moving abroad is a major life decision.

Your financial arrangements don’t necessarily need to be rebuilt from scratch just because your address has changed.

But changing tax residence can be an important financial planning event, and it is worth understanding the consequences before making irreversible decisions.

Don’t move your investments simply because you’re moving to Spain. But don’t wait until after you’ve moved to discover that the timing of a financial decision mattered.

If you’re planning to move to Spain and are unsure whether your existing investments, pensions and wider financial arrangements are still appropriate, I would be happy to have an initial conversation with you.

At The Spectrum IFA Group, I work with expatriates and internationally mobile individuals moving to or living in Spain, helping them review their investments, pensions and wider financial planning in the context of their new circumstances.

Sometimes the best financial decision is to change something.

Sometimes it is to leave it alone.

The important thing is knowing which applies to you.

I’ve Become Tax Resident in Spain — What Happens to My Investments?

By Matthew Green
This article is published on: 23rd September 2026

23.09.26

You haven’t sold your investments.

You haven’t moved your investment account.

You may not even have changed anything about the way your money is invested.

So why should becoming tax resident in Spain make any difference?

For many people moving to Spain, this is one of the questions that gets overlooked.

Your investments may still be held in the country you came from, but your tax position may have changed. For Spanish tax residents, Spain generally taxes worldwide income, subject to the specific rules that apply to the individual and any relevant tax treaty.

That means becoming resident in Spain can be a good time to step back and review your investments as a whole.

Does my investment have to move to Spain?

Not necessarily.

Becoming resident in Spain does not automatically mean that every investment you own needs to be transferred to a Spanish bank or investment provider.

You may have investments, savings or other financial assets held in another country and continue to hold them there.

The more important questions are:

  • How will the investment be treated for Spanish tax purposes?
  • Are there any reporting requirements?
  • Can your existing provider continue to service you as a Spanish resident?
  • Are the investments still appropriate for your circumstances?
  • Are the charges competitive?
  • Does the investment fit with your longer-term plans?

The location of an investment and your tax residence are two different things.

investments

What about investments from my home country?

This is where things can become more complicated.

Someone moving to Spain might arrive with a mixture of investments accumulated over many years. They could have shares, investment funds, savings accounts, bonds, pensions or other financial arrangements.

The country in which those assets are held does not necessarily determine how Spain will treat them.

There can also be reporting obligations relating to certain assets held outside Spain. For example, Spain’s Modelo 720 is an information return covering certain foreign accounts, securities, rights, insurance and other assets, subject to the applicable rules and thresholds.

This is one reason why simply leaving everything exactly as it was before moving may not always be the best approach.

Should I sell my investments before becoming Spanish resident?

This is a question I hear regularly.

The temptation can be to think:

“Perhaps I should sell everything before I become resident in Spain and start again.”

But selling investments simply because you are moving country can create its own consequences.

You need to consider the investment itself, potential gains, timing, taxation, transaction costs and what you intend to do with the money afterwards.

There is no universal answer.

For some people, restructuring before or after a move may be worth considering. For others, selling investments could create unnecessary costs or tax consequences.

The important thing is to understand the position before making a major decision.

What about ISAs and other tax-efficient arrangements?

People arriving in Spain often have financial arrangements that were designed around the tax system of their previous country.

An ISA is a good example for someone coming from the UK, but the broader principle applies to people from many different countries.

A tax-efficient investment in one country does not automatically receive the same treatment in another.

That doesn’t necessarily mean it should be closed or sold.

It means its treatment should be understood before making a decision.

What should I review after becoming a Spanish resident?

Rather than looking at each investment separately, I think it is more useful to look at the bigger picture.

For example:

Investments
Are your investments still appropriate for your objectives, timeframe and attitude to risk?

Tax
How are your different sources of investment income and gains treated in Spain?

Currency
If you hold assets in several currencies, does that still make sense now that your life is based in Spain?

Charges
Are you paying for services or investment arrangements that are no longer suitable?

Reporting
Do you have any Spanish reporting requirements relating to assets held overseas?

Retirement
How do your investments fit alongside your pension and other retirement income?

Estate planning
Would your current arrangements still make sense if you died while resident in Spain?

Future plans
Do you intend to remain in Spain permanently, or might you eventually return to your previous country?

These questions can be much more important than simply asking where an investment is held.

Moving country doesn’t necessarily mean moving your investments

One of the biggest mistakes people can make after moving to Spain is assuming that everything needs to be changed immediately.

Sometimes it does.

Sometimes it doesn’t.

The better approach is to understand what you already have, how it is treated now that you are resident in Spain, and whether it still fits the life you are building here.

Your investments may not need to move.

But your financial plan probably deserves to move with you.

If you’ve recently become tax resident in Spain and haven’t reviewed your investments and wider financial arrangements since your move, it may be worth taking a fresh look.

At The Spectrum IFA Group, I work with expatriates and internationally mobile individuals living in Spain, helping them review pensions, investments and wider financial planning in the context of their circumstances in Spain.

If you’re unsure whether your existing investments are still appropriate now that you live in Spain, get in touch and we can discuss your circumstances and whether a review would be worthwhile.
Retiring to the Costa Del Sol

By Jeremy Ferguson
This article is published on: 22nd September 2026

22.09.26

Every year, thousands of Britons make the decision to swap grey skies for blue horizons and build a new life on Spain’s Costa del Sol, and it is for much more than just the sunshine.

It’s also about the quality of life, financial freedom, family life, health, and making retirement the best chapter of life rather than simply the last. Recent research continues to show Spain is comfortably the number one destination for British retirees, attracting more than twice the interest of Portugal, and significantly more than France or Italy.

When I am dealing with clients and their plans to move here, I have noticed something interesting, in that people rarely move because of one particular reason, but often when asked, the overriding reason tends to be because everything simply ‘feels much better’.

retirement Spain

Better weather tends to equal a better lifestyle, and with that fact in mind the Costa del Sol enjoys over 320 days of sunshine every year, meaning more mornings on the golf course, walks along the beach, outdoor cafés throughout winter, and a lifestyle that naturally encourages people to simply spend more time outside.

As a result of this it is easy to see why people say they feel their heath has improved since they moved here. People tend to walk more, socialise more, relax more, all of which tend to lead to feeling generally less stressed. All of this combined typically means people finally slow down enough to fully enjoy the wealth they’ve spent decades creating.

For many British retirees, the financial benefits are just as attractive as the climate, with recent comparisons showing that overall living costs in Spain are around 32% lower than the UK, equating to almost £400 per month less spent. Groceries, household costs, restaurants and leisure activities are all significantly cheaper.

This doesn’t simply mean spending less, it often means living better, eating out more frequently, a healthier diet, swimming in the pool you didn’t have before, all of which define quality of life.

It’s not all plain sailing though, as moving countries also creates one of the biggest financial transitions many people will ever make, with a different tax system to adjust to, pension rules changing, Investment tax changing, as well as inheritance planning being different. Therefore the strategies that worked perfectly in Britain, can often become inefficient, or even expensive, once you’re a Spanish tax resident.

Question

I get asked all sorts of questions, is my UK pension in the right place? am I paying unnecessary tax on my investments? do I need a Spanish will? how should I pass wealth to my children? should I keep my UK bank accounts?  These are all very typical.

With none of these decisions being sensibly made in isolation, I have experienced all of these questions. With many client scenarios being very similar, explaining real life examples can go a long way to helping clients understand and become comfortable with what they need to do.

The whole point of a move to Spain is achieve a better quality life, with less stress, so if I can help you achieve some of that, then you know where I am.


I have Moved to Spain – What Should I Do With My UK Pension?

By Matthew Green
This article is published on: 15th September 2026

15.09.26

Moving to Spain is exciting. Your pension, however, probably wasn’t designed with the move in mind.

For many people, a UK pension is one of their largest assets. So, after becoming resident in Spain, it is natural to ask whether the pension should now be transferred to a Spanish or international arrangement.

But there is an important question to ask first:

Does it actually need to move?

The answer isn’t necessarily yes.

Do I need to transfer my UK pension?

Moving to Spain does not automatically mean that your UK pension needs to be transferred overseas.

Depending on your circumstances, you may be able to leave your pension in the UK and continue to manage it from Spain. In some cases, that may be the most appropriate option.

Before considering a transfer, it is important to understand what you already have, including:

  • The type and value of your pension
  • The investments and charges
  • Any guarantees or valuable benefits
  • When you can access the pension
  • How you expect to use it in retirement
  • Whether you may eventually return to the UK

A transfer should therefore be a financial planning decision, rather than simply a consequence of moving country.

Tax in Spain

What happens to the tax?

Becoming Spanish tax resident can change the way your pension income is treated.

The UK and Spain have a double taxation agreement, and the precise treatment depends on the type of pension and your circumstances. Private pensions and government-service pensions can also be treated differently.

This is why simply looking at where your pension provider is based isn’t enough.

Your tax residency, the type of pension and how you intend to take the benefits all need to be considered together.

What about my UK State Pension?

Your UK State Pension can generally continue to be paid while you live in Spain, subject to the relevant rules.

But your State Pension is only one part of your retirement income.

Your wider retirement plan might also include workplace pensions, personal pensions, SIPPs, investments, property or cash savings.

The important question is therefore not just:

“What will my pension pay me?”

but:

“How will all my sources of retirement income work together?”

Should I transfer my pension overseas?

This is where it is particularly important not to rush.

Certain overseas pension transfers can be subject to a 25% overseas transfer charge, depending on the circumstances, although exemptions and allowances can apply.

There can also be valuable benefits or guarantees attached to an existing pension that could be lost following a transfer.

So rather than asking:

“Can I transfer my pension?”

the better question is:

“What would I gain by transferring, and what could I potentially lose?”

The Financial Review Process

What should I review?

Even if you decide not to transfer your pension, moving to Spain is a good reason to review your overall retirement arrangements.

Consider:

  • Is the investment strategy still appropriate?
  • Are the charges reasonable?
  • Is the level of risk suitable?
  • How will the pension provide the income you need?
  • How does it fit with your other investments?
  • What happens if you eventually return to the UK?
  • Have your retirement plans changed since moving to Spain?

These questions become particularly important as you approach retirement.

So, what should I do?

If you’ve recently moved to Spain with a UK pension, I wouldn’t start by asking which provider you should transfer to.

I’d start by understanding what you already have and how it fits into your new life in Spain.

For some people, the best decision may be to leave their UK pension exactly where it is. For others, a review may identify opportunities to improve the investment strategy, charges, flexibility or overall retirement plan.

Moving to Spain doesn’t automatically mean your pension needs to move. But your financial plan probably deserves to move with you.

Have you reviewed your pension since moving to Spain?

If you’ve recently become resident in Spain and haven’t reviewed your UK pension and wider retirement planning, I would be happy to have an initial conversation with you.

At The Spectrum IFA Group, I work with expatriates living in Spain to review their pensions, investments and retirement plans, taking into account their circumstances in both the UK and Spain.

If you’re unsure whether your existing pension arrangements are still right for you, get in touch and we can discuss your situation and whether a review would be worthwhile.
Retirement Isn’t the Finish Line

By Matthew Green
This article is published on: 10th September 2026

10.09.26

It’s When the Financial Decisions Get Harder

For years, retirement is the destination.

You work. You save. You invest. You build your pension.

Then you retire.

Job done? Not quite.

In fact, retirement is often when the financial decisions become more important.

While you are working, your salary provides a regular income. If markets fall or you overspend, you have time to recover.

Once you retire, the equation changes.

Your investments may need to provide your income, potentially for 20, 30 or even 40 years.

So the question isn’t simply:

“How much money have I accumulated?”

It is:

“Will it be enough to support the life I want?”

What happens when things don’t go to plan?

Markets fall.

Inflation rises.

Unexpected expenses appear.

You live longer than expected.

Or one spouse dies before the other.

A retirement plan built around everything going perfectly isn’t really a plan.

This is why understanding your future cash flow can be just as important as choosing your investments.

Rather than simply looking at what you have today, you can model different scenarios:

  • What if investment returns are lower?
  • What if inflation remains high?
  • What if you live to 95 or 100?
  • What if you need a large amount of capital unexpectedly?
  • What happens to your spouse if you die first?

You can’t predict the future. But you can prepare for different versions of it.

Your retirement isn’t a number

Someone with €500,000 may be financially comfortable.

Someone with €1.5 million may not be.

It depends on their income, spending, investments, tax position and the lifestyle they want to maintain.

That’s why retirement planning shouldn’t stop when you retire.

It’s when your wealth needs to start doing the job your salary used to do.

Is your retirement plan built around a number – or a lifestyle?

If you’re approaching retirement or already retired in Spain, don’t leave the answer to chance.

A personalised cashflow forecast can bring your financial future to life. It can show how your income, spending, investments and capital could develop over time—and, importantly, what happens if things don’t go exactly as planned.

You don’t need to predict the future. You need to understand it.

Are you receiving the advice you should be?

There are also many people who already have pensions, investments or other financial arrangements in place but haven’t had a meaningful review of their circumstances for some time.

Perhaps your adviser has retired or moved on. Perhaps you’ve been passed between advisers. Or perhaps you simply aren’t receiving the regular contact and ongoing advice you expected.

If that sounds familiar, you don’t necessarily need to start again.

A fresh review can help you understand what you currently hold, whether it remains appropriate for your circumstances and whether your financial arrangements are still aligned with your goals.

Your financial circumstances don’t stand still—and your financial plan shouldn’t either.

Whether you’re approaching retirement, already retired, or simply feel that your existing arrangements aren’t receiving the attention they deserve, a review can be a useful first step.

There is no obligation to change your existing investments or make any immediate decisions.

The starting point is simply a conversation about where you are today, what you want your money to achieve and whether your current arrangements are still working for you.

If you haven’t received retirement or pension planning advice in the past 12 months, it may be time to review where you stand. Get in touch to arrange an initial conversation and let’s look at whether your current arrangements are still working for you.

Because the earlier you identify a potential problem, the more options you have to do something about it.

Will you make these Spanish tax mistakes in the next four months?

By Barry Davys
This article is published on: 31st August 2026

31.08.26
It is important to remember that the Spanish tax year runs from 1 January to 31 December.
As we approach the end of the Spanish tax year, I often see people making decisions that inadvertently increase their tax bill for the current year. If you do not want to pay more tax than necessary, here are some guidelines to help you reduce your tax bill.

What can increase your tax bill?

Sales and certain transfers of assets before 31 December may be taxed in the current tax year.

Sales

Some taxes are cumulative. If you continue selling assets that have increased in value, the tax rate will be based on your total gains for the whole year.

The tax rate will also depend on which Autonomous Community you are resident in. For example, the top rate of tax on gains in Catalonia is 30%.

If you think your savings, or perhaps that second property, have performed well, the result can look very different once the tax bill is taken into account.

Selling a second property, or selling your main residence if you are under 65 at the point of sale, can create a significant tax bill.

If you have only one property to sell but have already made significant gains from other sales this year, should you consider completing the property sale in the new tax year instead?

The profit from the sale of vested shares received through share option schemes can result in either income tax or capital gains tax. The constitution and terms of the share option scheme will determine which tax treatment applies.

We regularly see shares being sold soon after they have vested. If you have share options vesting, you can reply to this email to find out more and discuss whether you should sell in this tax year or the next.

Transfers

Making transfers of assets between people before the end of the year can also increase your tax bill. These transfers can include:

  • Gifts to individuals who are tax resident in Spain
  • Gifts to non-resident individuals involving assets located in Spain
  • Transfers of non-EU pensions (for example, UK pensions) into European-based pension schemes

A pension transfer can potentially be taxed on the whole transfer value by adding it to all your other income. The result can be a very significant tax bill — potentially tens of thousands of pounds on a relatively modest pension.

Get specialist advice before you act

To ensure you receive the best possible support and advice, we can also call upon lawyers, who we have worked with 14 years, as needed.

What you should do in relation to a sale or transfer will depend on your personal circumstances. There is no one-size-fits-all answer.

To avoid making costly mistakes, you are welcome to book a call at a time that is convenient for you using my online booking system. You can tell me about your personal circumstances, and we can then advise you on what you should consider doing.

The right course of action will follow from there.


What If Spain Doesn’t Work Out?

By Matthew Green
This article is published on: 28th August 2026

28.08.26

Moving to Spain can feel like the final destination.

For many expats, the plan is simple: sell up, move abroad, enjoy the lifestyle and build a new life in the sun.

But what happens if, somewhere down the line, Spain isn’t quite what you expected?

Perhaps your circumstances change. Your children move elsewhere. Your priorities change. You decide you want to be closer to family. Or maybe you simply discover that another country, or even your home country, suits you better.

It is something few people consider when they first move abroad.

Your financial life needs to be flexible too

When you move countries, your financial affairs can become increasingly complicated.

You may have pensions in one country, investments in another, property in Spain and bank accounts spread across several jurisdictions.

Then, if you decide to move again, the questions start to appear:

What happens

What happens to my investments?

What happens to my pension?

Will I still be able to hold the same investments if I leave Spain?

What happens to my tax position?

Will moving again create unexpected tax consequences?

These aren’t necessarily reasons not to move — they are reasons to think beyond the move itself.

Don’t build a financial plan that only works in Spain

One of the biggest mistakes can be assuming that today’s circumstances will remain unchanged for the next 20 or 30 years.

A good financial plan should consider not only where you live today, but the possibilities that could affect you tomorrow.

That might mean understanding how your investments could be affected if you become tax resident somewhere else, ensuring your pension arrangements remain appropriate, or simply keeping enough flexibility in your finances to give you choices later.

Because ultimately, financial planning isn’t just about making your money work for you in your current circumstances.

It’s about making sure your money doesn’t prevent you from changing those circumstances.

The freedom to change your mind

Nobody moves to Spain expecting it not to work out.

But having a plan for the unexpected doesn’t mean you are expecting the worst.

It means giving yourself options.

Perhaps Spain will be your home for the rest of your life.

Perhaps it will be the place you spend the next ten years.

Or perhaps, one day, you’ll decide it’s time for another change.

The best financial plan isn’t necessarily the one designed around one particular destination.

It is the one that gives you the freedom to choose where your life takes you next.

Is your financial plan flexible enough?

If you live in Spain, it can be useful to step back and consider whether your current financial arrangements would still work if your circumstances or country of residence changed.

I help expats in Spain look at the bigger picture — from investments and pensions to tax planning, inheritance and long-term cashflow.

If you’d like to understand how flexible your financial plan really is, get in touch for an initial conversation.