Geopolitics and Oil Prices
Over the past couple of weeks I’ve received a number of questions from concerned clients about the latest geopolitical developments and what they might mean for markets.
Tel: +34 93 665 8596 |
info@spectrum-ifa.com |

By Peter Brooke
This article is published on: 14th March 2026
Over the past couple of weeks I’ve received a number of questions from concerned clients about the latest geopolitical developments and what they might mean for markets.
Whenever headlines become intense, it can understandably feel as though something dramatic must be happening in financial markets as well. The reality is often more nuanced — and this appears to be one of those moments.
Markets have reacted to rising geopolitical tensions, but the moves so far suggest caution rather than panic.
The key variable investors are watching is energy prices. Historically, bear markets tend to be linked to recessions, and the main risk from the current conflict is whether sustained oil price increases could slow economic growth.
Recent tensions in the Middle East involving Iran, the United States and Israel have dominated global headlines and created understandable concern among investors.
When events escalate quickly, it is easy to assume markets will react dramatically. Yet the response from investors so far has been far more measured. Markets have certainly moved, but the behaviour looks much more like caution than panic.
The real question investors are asking is not simply what is happening geopolitically — but whether it could become an economic shock.
So far, markets appear to be adjusting to geopolitical risk rather than assuming it will derail the global economy.
The most immediate reaction has been in energy markets.
Oil prices briefly surged as investors priced in the risk of supply disruption through the Strait of Hormuz, one of the most important shipping routes in the global energy system. At one stage prices approached $120 per barrel, before retreating to below $90, still significantly higher than the $65 level seen at the end of February.
This sensitivity reflects the strategic importance of the region. Roughly 20% of global oil supply normally passes through the Strait of Hormuz, meaning even temporary disruption can move prices quickly.
Equity markets have moved lower, although declines have been relatively contained. Across developed markets, equities have generally fallen between 2% and 6%, while emerging markets have seen slightly larger pullbacks due to their greater reliance on imported energy.
Safe-haven assets have also seen some demand. The US dollar strengthened, while gold briefly rose above $5,400 per ounce before easing again.
Despite dramatic headlines, the overall reaction has remained relatively orderly. As LGT Wealth Management noted in a recent update:
“While the headlines have been dramatic, market moves so far suggest investors are reacting with caution rather than panic.”
Interestingly, much of the volatility has occurred beneath the surface of markets. The Rathbones multi-asset team recently highlighted that while headline equity indices have only fallen around 3–4%, there has been significant rotation between sectors and individual stocks.
Chris Saunders of New Horizon Asset Management also notes that the conflict is beginning to affect other parts of the global economy. Disruptions to Iranian production have tightened fertiliser markets, pushing prices higher and raising the possibility that food prices could also rise in the months ahead.
When geopolitical crises occur, investors tend to focus on one key question: Could this trigger a recession?
This distinction is important because historically bear markets (defined as a fall of 20% or more in stock markets) tend to occur when the economy enters a recession, rather than simply because geopolitical tensions increase.
One of the main channels through which geopolitical events can affect economic growth is energy prices. Economists often use a simple rule of thumb: every $10 increase in oil prices can add roughly 0.3% to inflation and reduce economic growth by a similar amount.
With current expectations for US economic growth around 2.2%, oil prices would likely need to rise well above $120–$130 per barrel and remain there for a sustained period before recession risks became materially elevated.
At present, prices remain below those levels.
However, as Chris Saunders notes, the key variable may be how long the conflict continues, as prolonged disruption to Middle Eastern energy supply could delay interest-rate cuts and keep inflation pressures elevated.
This helps explain why markets have responded cautiously rather than dramatically.
Periods of geopolitical tension can certainly create short-term volatility, but they rarely change the long-term trajectory of global markets unless they spill over into the broader economy.
Portfolio managers also emphasise the importance of remaining disciplined during periods like this.
As one Rathbones portfolio manager noted in a recent discussion:
“What was a good company before the weekend is still a good company afterwards. The share price may now be lower — which can create opportunities.”
Similarly, the investment team at Atomos emphasised that predicting short-term market movements during geopolitical crises is extremely difficult, reinforcing the importance of maintaining diversified portfolios designed to withstand periods of uncertainty.
Energy shocks can also accelerate structural change. Previous crises — including Europe’s energy shock following Russia’s invasion of Ukraine — helped accelerate investment in renewable energy, batteries and alternative energy systems.
• Markets have reacted with caution rather than panic despite dramatic geopolitical headlines
• Oil prices remain the key variable investors are watching
• Historically, bear markets are far more closely linked to recessions than geopolitical events alone
• Current oil prices remain below levels historically associated with recession risk
• Maintaining a disciplined, diversified investment strategy remains the most effective approach during volatility
Geopolitical developments will inevitably continue to evolve over the coming weeks. However, markets so far appear to be adjusting rather than overreacting.
History repeatedly shows that while headlines can move quickly, markets often prove more resilient than expected.
I hope you found this update interesting and helpful.
If anything has raised questions for you, or you’d simply like to talk something through, please don’t hesitate to get in touch. That’s exactly what I’m here for.
Please complete the form below:
By Peter Brooke
This article is published on: 12th March 2026
I hope this newsletter finds you well; So, pensions are back in the spotlight as governments in the UK and Ireland introduce meaningful changes that could affect how individuals and business owners save for retirement. In this edition, we break down what’s changing, why it matters, and what you should be thinking about next.
As you may have seen in the recent UK budget from April 2026, most expatriates will no longer be eligible to pay Class 2 National Insurance Contributions (NICs) and will instead need to use Class 3 contributions which cost more — but this still may offer an excellent return on investment.
The ruling states:
“From 6 April 2026, individuals will no longer be able to pay voluntary Class 2 NICs for periods abroad. Only voluntary Class 3 contributions will be available for tax years 2026 to 2027 onwards.
This change does not affect any voluntary contributions that can be paid for periods abroad before 6 April 2026 – there is more detail here
If you’d like help interpreting your forecast or reviewing your eligibility for Class 2 vs Class 3 contributions, feel free to share the summary or screenshots — I’ll walk you through the options.
The ruling also states that “New applications to pay voluntary Class 3 NICs will need to have either”
What remains unclear is whether contributions paid for whilst abroad will count towards the 10 year rule and whether it is therefore sensible to pay for missing years before April 2026 to ensure you have 10 qualifying years so that you will be eligible to pay future years.
It certainly appears that long term non-UK residents, without 10 years of NICs, could be “locked out” of the system from April.
Based on current UK State Pension levels, even at Class 3 NIC rates (around £900 per year), each extra qualifying year typically adds about £330 per year to your State Pension for life (though this will depend on future government policy).
This means most people recover the cost in less than three years of receiving their pension — and every year after that is a financial gain.
You generally need 35 qualifying years of National Insurance contributions to receive the full UK State Pension. That’s why it’s important to know three things:
Once you understand these three numbers, you can work out exactly how many additional years you might need. And remember: you may not have to pay for every remaining year at the higher Class 3 rate after April 2026.
Many expatriates will reach the 35-year mark using a combination of existing contributions, cheaper buy-back years, and only a small number of future payments.
Government Gateway tip:
To log in, you need to receive a security code by text message. If you change your mobile number, make sure you update it with HMRC before you lose access to the old phone number. Otherwise, you may be locked out of your Government Gateway account and unable to view your State Pension record.
Ireland is restructuring older Executive Pension Plans (EPPs), and by April 2026 the IORP II regulations (see details here) will require EPP schemes to either:
…or risk becoming frozen or facing significantly higher running costs.
For clients living outside Ireland, the decision between these options is particularly important.
If you expect to remain an EU resident during retirement, there are often strong long-term reasons to transfer your pension out of Ireland; (I cant cover this in this newsletter but contact me if you want more information).
Because of this, it is crucial that whatever happens to your pension today does not restrict your ability to make that transfer in the future.
To protect your future options, we strongly recommend:
✔ Before agreeing to a Master Trust transfer, obtain written confirmation that the scheme allows transfers to foreign pension arrangements in the future.
✔ Do not sign any PRSA transfer paperwork without a full review of the long-term implications.
✔ Forward any pension documents or transfer requests to us — we will assess them for you and advise on your position.
We help clients:
If you hold — or think you may hold — an Irish Executive Pension, reply to this email or click here to schedule a consultation.
We’ll ensure the restructuring supports your long-term financial interests, rather than simply following administrative defaults.
Since Brexit, many expatriates are discovering that once they are no longer UK-resident, it is often not possible to receive ongoing regulated advice on their UK pensions from either UK-based advisers or overseas firms like Spectrum.
We regularly see clients being contacted by their UK adviser or pension provider and told that the relationship must end — leaving them unadvised and unable to manage their pensions effectively.
At the same time, changes to pension regulation mean that QROPS transfers are now far less common and often no longer suitable. This leaves many expatriates unsure how to handle their UK pension schemes as they approach or move through retirement.
Your UK pensions can still be actively and professionally managed by a local adviser by transferring them to an International SIPP. This can also allow you to consolidate multiple pension pots into one, making your retirement planning far simpler.
An International SIPP can provide:
✔ Access to regulated advice
✔ Better consolidation and control, including currency options
✔ Potentially lower fees
✔ A flexible investment approach aligned to your residency and long-term goals
We can help you:
You don’t need to leave your pension un-managed. Send us your pension information and we’ll assess whether an International SIPP could allow us to advise you properly and optimise your retirement planning.
Important pension changes are now underway across the UK and Ireland and for many expatriates and business owners these changes create both risk and opportunity.
Across all three areas, the key message is the same: early decisions have long-term consequences. A short review today can protect flexibility, reduce future costs, and strengthen your retirement position.
If any of these changes affect you, we encourage you to get in touch. We’re here to help you navigate the complexity and ensure your pension remains aligned with your long-term plans.
If you have any questions please send them via the channels below, or the booking system – always drop me a quick message if you need a time slot outside of those available.
If you have missed any previous emails, click here to access the Archive.
For now, have a great day, speak soon…
Best regards
Peter Brooke
Mobile & Whatsapp: +33 6 87 13 68 71
Email: peter.brooke@spectrum-ifa.com
Calendly booking system: https://calendly.com/peterbrooke/30min
By Katriona Murray-Platon
This article is published on: 4th March 2026
After a very wet, windy and stormy February it is lovely see some sunshine and the first spring flowers coming into bloom.
The income tax thresholds have not been frozen as initially planned in the 2026 finance bill; instead, they have increased by 0.9%, aligning with the 2025 rate of inflation. The new tax-free allowance is €11,600 per person. The other tax bands are as follows:
| INCOME | RATE |
| Up to €11,600 | 0% |
| From €11,601 to €29,579 | 11% |
| From €29,580 to €84,577 | 30% |
| From €84,578 to €181,917 | 41% |
| Over €181,917 | 45% |
Employees can deduct a set amount of €509 from their taxable salaries for costs, capped at €14,556. The 10% abatement before tax will still apply to pensions with a minimum of €454 and a maximum of €4439.
To reduce your taxes and assist you at home you may use home help such as a gardener or cleaner. Now the cost of home delivered meals to the handicapped or elderly and their dependents also qualifies for a tax credit even if you don’t have other kinds of home help. While services may be more limited in rural areas, it’s worth exploring.
Another measure that has been scrapped is the increased VAT threshold for independent workers and furnished rentals. This threshold remains unchanged.
As mentioned in last month’s Ezine, social charges have risen from 17.2% to 18.6%. Whilst this does not apply to assurance vies nor PEL accounts, it will apply to PER retirement accounts. Also, after the recent fall in interest rates on the Livret A and LDDS accounts on 1st February, the interest rate on the LEP account has also dropped from 2.7% to 2.5%.
Assurance Vies remain the most popular investment products in France with €2,107 billion currently invested, compared with only €449 billion in Livret A and €136 billion in retirement accounts. According to INSEE, investments in Assurance Vies have increased over the years with €121 billion invested in 2005, €135 billion in 2015 and €192 billion in 2025. Whilst Euro Funds (the money that that French government and businesses borrow from the insurance companies) remain the preferred asset class, this figure has decreased from 79% to 61% in 2025 with the remaining 39% in equities. Although the average rate of Euro Funds was 2.7% in 2025, it has rarely outpaced inflation over the past 8 years. Our assurance vies offer a more diversified, cross-border approach, making them more suitable for English speaking expats.
On 25th February 2026 the Prudential Assurance Company board reviewed the Prufund Expected Growth Rates (EGR) as part of its quarterly review. Prufund aims to help customers grow their investments over the medium to long term (5 to 10 years) while protecting them from short-term market fluctuations through the unique smoothing process. The Expected Growth Rate (EGR) is the forward-looking element of the unique Prufund smoothing mechanism. This quarter the EGRs for all versions of Prufund remain unchanged.
However, there have been some upward movements to the, the Unit Price Adjustment (UPA), the backward-looking element of the Prufund smoothing process, which is formulaic and non-discretionary, as follows:
Prufund Growth GBP +2.54%
Prufund Growth Euro + 3.25%
Prufund Growth USD + 3.46%
This is positive news for Prudential International investors when they receive their quarterly statements at the end of the month.
At the time of writing, the US and Israel have launched strikes against Iran, which will have an impact on oil prices and may cause some short-term market volatility. However, our well diversified portfolios are designed to withstand periods of geopolitical tensions. In times of intense media coverage, it’s important to remain calm and focus on long-term strategies.
By Katriona Murray-Platon
This article is published on: 10th February 2026
At the end of January, I joined colleagues and product providers at our annual conference in Monaco. We heard a range of insightful presentations from companies including Evelyn Partners, iPensions, Momentum, New Horizon, VAM Alquity, LGT Wealth Management, Novia Global, Rathbones, Utmost, Prudential and RBC Brewin Dolphin.
There is often a difference between what dominates the headlines and what investment managers focus on. While it has become increasingly difficult to ignore what is happening in America, it is important to remember that we maintain a long-term focus for our clients’ investments.
As outlined by the fund managers, markets remain heavily tech-focused. However, although stocks from the companies known as the “Magnificent Seven” dominated markets in 2023 and 2024, there has been some broadening in 2025. Nvidia shares have recently flatlined and Microsoft was down 20%. Even though European stock markets are performing better, fund managers are not yet ready to abandon US equities in favour of European ones.
Unfortunately, the UK economic outlook remains gloomy. For several years now, fund managers have highlighted how little exposure they have to UK stocks within their portfolios. However, the FTSE 100 performed well in 2025, largely because many UK companies generate profits outside the UK.
There was considerable discussion around artificial intelligence.
While some may view AI as potentially similar to the dot-com bubble, our product providers demonstrated how the underlying economic fundamentals are very different.
Many people now use AI, but the key question remains: who is actually making money from it?
AI also requires significant infrastructure, including large data centres and substantial energy supply. Its influence is now extending into emerging markets as well.
Fund managers have reduced their oil exposure as energy prices continue to decline. Sovereign bonds, however, are becoming more attractive, with yields of between 1% and 3%, particularly Norwegian, Australian, New Zealand and Japanese bonds.
Novia announced its new GIA product which, like its SIPP, can hold funds denominated in HKD and Australian dollars, as well as GBP, EUR, CHF and USD. Currently, UK SIPPs sit outside a deceased person’s estate for inheritance tax purposes. However, proposals from the UK Chancellor will bring defined contribution pensions into the inheritance tax net from 6 April 2027.
Evelyn spoke about the digital data boom, describing it not as a fad but as a generational shift (anyone with teenagers will relate). Their aim is to “turn data into dollars” in 2026, and they continue to see opportunities, particularly among companies utilising AI. Stronger earnings and a weaker dollar are also supporting emerging market equities.
In French financial news, from 1 February 2026 the interest rates on French savings accounts have been reduced as follows:
Livret A: 1.50%
Livret de développement durable (LDDS): 1.50%
Livret Jeune: 1.50%
Compte Épargne Logement (CEL): 1.00%
Returns from euro funds in French assurance-vie policies appear to have stabilised. The average rate of return in 2025 was 2.65%, compared with 2.63% in 2024 and 2.60% in 2023.
After social charges taken at source, the average net return is 2.19% — only 1.5 percentage points above inflation.
While these assets are often viewed as safer options, cautious investors may benefit over time from increasing equity exposure to achieve stronger long-term growth.
Local taxes, in particular taxe foncière, are not expected to increase by more than 0.80% in 2026, due to the increase in the rental value of properties.
Other key changes from 1 January 2026 include:
In January, if you benefited from specified tax credits or reductions (for example, home help), you will have received a payment equal to 60% of the total amount. The remaining balance will be reconciled through your 2025 tax return in September 2026.
After catching up with work following the conference, I will be spending time with my family from 16 to 20 February during the half-term holidays. If you have any questions about the information above, or would like to arrange a time to discuss your financial matters, please do get in touch.
By Peter Brooke
This article is published on: 9th February 2026
I’ve just returned from the 23rd Spectrum annual conference — my 22nd — which this year was held in Monaco, making it refreshingly easy travel for me.
Each year we bring together Spectrum advisers from across Europe, along with our support and management teams, and a carefully chosen group of investment managers, pension specialists, and tax experts. It’s a chance to step away from the day-to-day detail, compare notes, challenge assumptions, and make sure the advice we give clients continues to stand up in a changing world.
One thing that’s worth sharing, because it underpins everything else in this update, is what Spectrum actually is. We’re a large, international advisory firm — but we’re also owned by the advisers who work in it. We’re currently restructuring the business to widen that ownership further, so more advisers have a direct stake in the firm’s future.
That matters because we’re not building towards a quick exit. We’re building something designed to last, we are proud of the longevity of the business and the strong retention of our advice team. The conversations at the conference reflected that long-term mindset — less about chasing the next headline, and more about understanding the forces that genuinely shape investment outcomes over time.
With that in mind, here are the main themes I took away from the conference, and why they matter for expatriates and internationally mobile families.
Artificial intelligence was easily the dominant topic of the conference — but not in the “buzzword of the month” sense. The most interesting discussions weren’t about which stock has run the hardest, but about where AI is genuinely changing productivity, margins, and long-term business models.
The key message from managers like Rathbones and Evelyn Partners was that we’re moving into a second phase of the AI story. The early gains were very concentrated — a small group of large US technology companies driving market returns. That phase isn’t necessarily over, but it is evolving.
What’s happening now is a broadening out. AI is starting to affect industrial businesses, healthcare, logistics, energy management, data infrastructure, and even areas like waste management and defence. In other words, it’s moving from “who builds the chips” to “who uses the technology well”.
That distinction matters. History shows that transformative technologies don’t just reward the obvious early winners — they reward companies that apply them intelligently, efficiently, and profitably. For investors, this reinforces the importance of looking beyond the headlines and staying diversified, rather than assuming yesterday’s winners will automatically dominate tomorrow as well.
Another strong theme that came through very clearly was a return to fundamentals.
Markets over the last couple of years have often felt narrow and momentum-driven, with a small number of stocks (mainly AI/Tech) doing most of the work. Several managers made the point that this sort of environment can feel exciting — but it also increases risk if portfolios become too concentrated – at one point just 7 companies made up nearly 35% of the size of the US stock market (S&P 500)!
Rather than trying to predict short-term market moves, the emphasis is now firmly back on:
cash flow and balance sheet strength
sensible valuations
real earnings growth
businesses with pricing power and durable demand
For clients, this translates into something reassuringly familiar: diversification still matters. Not just across regions, but across styles, sectors, and asset classes. It’s rarely the most exciting message — but it’s consistently one of the most effective.
Several presentations also focused on areas outside traditional listed markets.
There was strong interest in private assets and real assets — things like infrastructure, property, and long-term income-producing investments. These aren’t about quick wins; they’re about accessing different return drivers and reducing reliance on public market volatility alone.
For many expatriate investors, this can be particularly valuable. Income that’s less sensitive to daily market swings, assets linked to real economic activity, and structures designed with long-term planning in mind can all play a role alongside more traditional portfolios.
As always, these areas need careful selection and suitability — but the message was clear: a well-built portfolio doesn’t rely on a single engine to get where it’s going.
Another interesting thread was the importance of scale and governance, particularly in uncertain markets.
From an investment perspective, larger, well-capitalised businesses tend to have more resilience: better access to finance, more flexibility in downturns, and greater ability to invest through cycles rather than cut back at the wrong time.
That same principle applies at an advisory level too. Spectrum’s size, international reach, and shared ownership model allow us to invest in systems, compliance, and expertise in a way that simply isn’t possible for smaller, standalone firms.
It’s not about being big for the sake of it — it’s about stability, continuity, and quality of advice over decades, not just years.
Another reassuring takeaway from conference was spending time with the firms we work with on clients’ behalf — not just listening to presentations, but understanding how they think, how they’re governed, and how decisions actually get made.
One of the advantages of being part of a group like Spectrum is that we’re able to be selective. We don’t work with managers because they’re fashionable or because they shout the loudest — we work with them because they have depth, longevity, and a track record of navigating change.
None of this guarantees outcomes — nothing ever does — but it does give us confidence. These are organisations built to endure, with governance structures and cultures that align closely with how we think about long-term planning for clients.
For me, this is a crucial but often invisible part of the job: doing the work behind the scenes so that clients don’t need to worry about whether the foundations are solid. The conference reinforced that the partners we choose, and the effort that goes into maintaining those relationships, genuinely matters.
Stepping back, the conference reinforced something I see year after year: successful long-term investing is rarely about prediction.
It’s about:
That’s particularly important for expatriates, where cross-border rules, currencies, tax systems, and future uncertainty add extra layers to every decision.
If you’d like to talk through how these themes relate to your own situation — or simply want a sense-check that your plans still reflect what matters most to you — that’s exactly what I’m here for.
If you want to dive a little deeper into any of this detail, there are some great articles at these links.
Evelyn Partners Turning data into dollars in 2026
Rathbones Video Market broadening and Geopolitical noise
If you feel this would be helpful to friends, family or colleagues, please do feel free to forward this on to them.
As always, I’ll keep translating what we hear from conferences like this into practical, real-world advice that fits your life, not just the markets.
Finally, I’d like to say a genuine thank you to the firms who took the time to join us in Monaco, share their thinking so openly, and engage in thoughtful, sometimes challenging discussion.
In particular, my thanks go to the teams from Rathbones Asset Management, Evelyn Partners, LGT Wealth Management, Alquity VAM Investment Management, New Horizon Asset Management and Prudential International, and the other investment, pension, and tax specialists who contributed to the conference.
These events only work because people are willing to go beyond polished presentations and talk honestly about risks, opportunities, and uncertainties. That openness is exactly what helps us refine our thinking and, ultimately, improve the advice we give to clients.
It was a privilege to spend time with such high-quality partners — and it left me confident not only in the ideas discussed, but in the people and organisations helping us put those ideas into practice.
By Katriona Murray-Platon
This article is published on: 7th January 2026
Happy New Year!! I wish you all the very best for 2026. I hope that you had an enjoyable festive season. We spent Christmas at home, which was very nice and relaxing, so now I am well rested, ready for the new year and looking forward to seeing all my clients.
On 9th December the Law for the Financing of the Social Security was adopted by the National Assembly and, pending any issues with the Constitutional Court, it is now enacted into law. Under this law, the official retirement age is now 62 years and 9 months, with a required contribution of at least 170 semesters set until 1st January 2028 for pensions taking effect from 1st September 2026. As a result, anyone born between 1964 and 1968 may retire 3 months earlier than previously expected. Furthermore, as from 1st January 2026, the French state pension increased by 0.9%.
This law also increased the CSG social charges on interest, dividends and capital gains from 9.2% to 10.6%. The flat tax (PFU) on this income has therefore risen from 30% to 31.4%. However, withdrawals from assurance vie policies, PEL and PEP (plan épargne populaires) accounts, rental income and capital gains on property are not affected. So for people with money in UK saving accounts, the interest will now be taxed more heavily in France. It is worth considering whether it remains appropriate to keep such accounts, or whether it would be more tax-efficient to move funds into French savings vehicles such as a Livret A or LDDS, or into an assurance vie for longer-term planning.
If you have up to €61,200 that you need to put away for a year or two, a PEL account opened from 1st January 2026 now offers an interest rate of 2% compared with 1.75% for PELs opened after 1st January 2025. The interest rate for a PEL is determined at the time the account is opened.
From 1st January 2026, cash gifts now need to be declared online via your account on the impots.gouv.fr website. This applies to gifts of money, shares or valuable items such as a car. You will be asked to declare any money or gifts of value and state whether they fall under the €100,000 allowance between parents and children or the €31,865 made by a relative under 80 years old to a recipient who is over 18 years old. If the recipient is a minor, their parents should do the declaration for them on their online account. Christmas gifts remain exempt and do not need to be declared.
Since 1st December 2025, parents who are divorced or separated, will now both receive childcare benefit (complement de libre choix de garde) provided the child is cared for by a registered childminder either at the childminder’s home or at the child’s home.
For those looking for a bargain or waiting to buy something special, the sales in France will begin on Wednesday 7th January at 8am and will continue until Tuesday 3rd February.
If you are considering choosing an electric vehicle for your next car, the good news is that government incentives will continue in 2026.
Low-income households may receive a bonus of €5,700, middle-income households €4,700, and all other buyers €3,500, when purchasing a brand-new electric car.
An additional bonus of between €1200 and €2000 may also be granted if the battery of the car was manufactured in Europe.
Furthermore the thresholds for what is considered a low income and middle income households have been increased.
Later this month, I will be attending our annual conference in Monaco with colleagues and meeting with our product providers to review the past year and discuss the factors likely to influence investment strategies in 2026. I will share key insights from our conference in the next Ezine.
In the meantime, if you have any questions about the topics above or would like to discuss your personal financial situation, please do not hesitate to get in touch to arrange a free phone call or meeting.
By Peter Brooke
This article is published on: 25th December 2025
As we come to the end of the year, we wanted to share a brief reflection on what has been a challenging but ultimately rewarding period for investors.
It’s been another unusual year (I think I wrote that in my last Christmas newsletter!!). We began 2025 with talk of a Trump tariff driven recession, interest rate cuts and the end of US dollar dominance. Instead, growth has slowed but not collapsed, interest rates have stayed higher for longer, and after weakening early in the year, the US dollar has strengthened again in the second half of 2025.
Equities experienced volatility along the way, driven by geopolitics, policy changes and concerns around inflation. Despite this, strong company earnings — particularly in technology and AI — helped global markets finish the year close to record highs. This was a reminder of the value of staying invested through short-term uncertainty.
Bonds quietly did their job. While yields rose earlier in the year, they provided attractive income and stability, reinforcing their role as a key diversifier within portfolios.
Gold stood out as a strong performer, offering effective protection against geopolitical and economic uncertainty while contributing positively to returns.
Overall, 2025 reinforced an important lesson: diversified, multi-asset portfolios can help investors navigate uncertainty and capture long-term opportunities — even in unsettled markets.
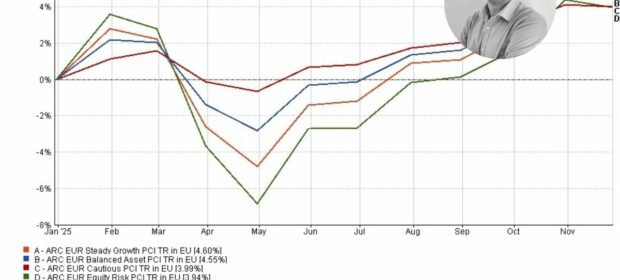
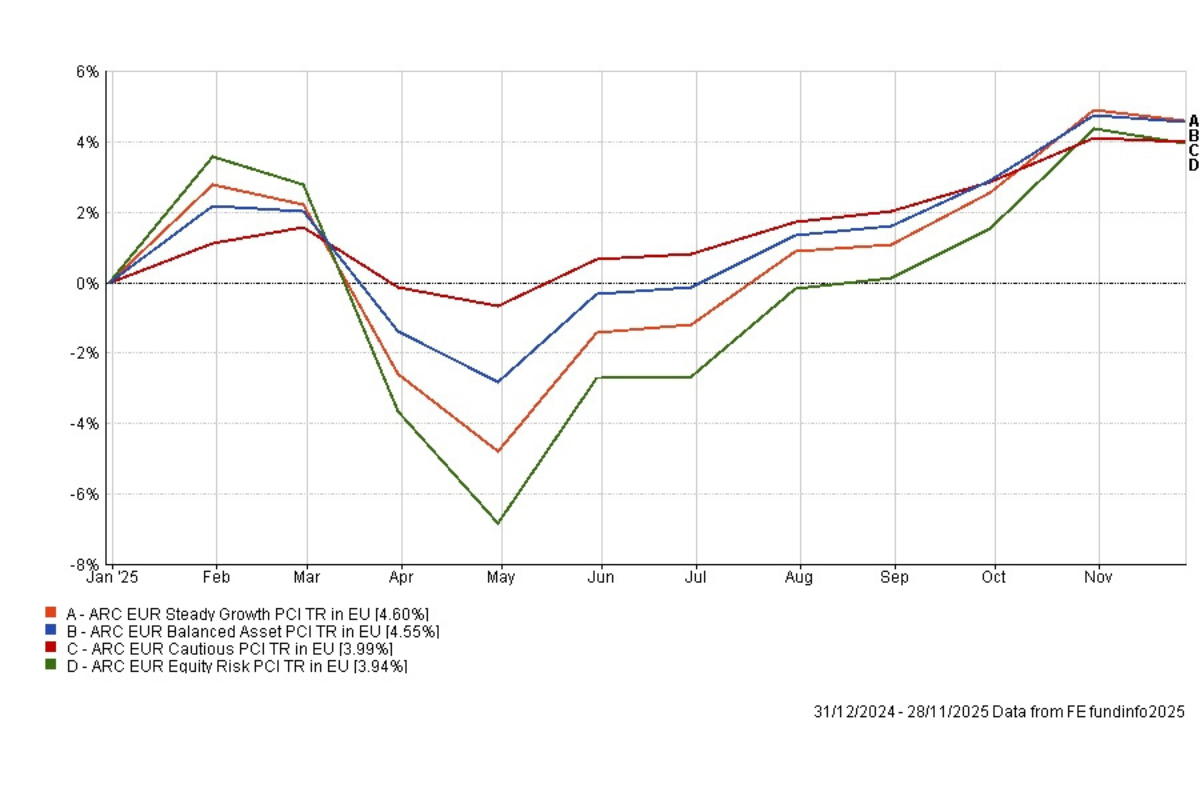
You’ll see below a chart showing the ARC Euro Indices for this year; the movements reflect the periods of volatility investors experienced, especially post ‘Liberation Day’ followed by a recovery as confidence improved.
It’s a helpful visual reminder that while markets rarely move in a straight line, staying invested through the ups and downs has historically been key to achieving long-term outcomes.
As we head into the festive season, I’d like to thank you for your continued trust and wish you and your family a very happy Christmas and a healthy, prosperous New Year.
I will be back in touch in January with a financial outlook for 2026 following our next annual Spectrum conference and, of course, I plan to continue to provide you with updates, developments and new support tools over the year ahead…
By Victoria Lewis
This article is published on: 27th November 2025
A présent d’usage is a customary gift given on a special occasion and of modest value, in proportion to the donor’s wealth and income.
In plain terms, it’s a gift made for a particular event – like a birthday, wedding, graduation, Christmas, or another significant celebration – and it must not be large enough to affect the donor’s financial situation.
If those two conditions are met, the gift is not subject to gift tax and does not need to be declared.
Legal definition and principles:
French law doesn’t specify a fixed euro amount. Instead, courts and tax authorities judge “modest value” relative to the donor’s means.
Event + Typical acceptable gifts (if proportionate)
Birthday or Christmas: A few hundred euros, watch, jewelry, small artwork
Wedding: A few thousand euros if donor is wealthy, smaller if not
Graduation / birth of a child: A symbolic sum or piece of jewelry
Religious events: Usually modest cash or gift
The gift ceases to qualify and becomes a taxable donation if:
If the tax administration audits and decides it’s really a “donation déguisée,” they can requalify it and apply the 60% gift tax (if between non-relatives).
Practical rule of thumb.
A gift of no more than 1–2% of the donor’s net worth or a few weeks’ income will usually be accepted as a présent d’usage, provided it’s tied to a genuine occasion.
There’s no official threshold — it’s all about proportion and context.
As noted earlier, there’s no fixed ceiling — it depends on whether the gift is modest relative to the donor’s wealth and income and is tied to a special occasion (birthday, wedding, graduation, etc.).
For guidance, notaires and tax authorities often use informal rules of thumb when advising clients.
If the donor earns about €500,000/year and has assets consistent with that income, a gift of roughly 1–2% of annual income would often be viewed as proportionate for a major occasion.
That works out to:
€5,000 to €10,000 for a standard event (birthday, graduation, wedding present, etc.)
Possibly up to €20,000 or so for a very special event (e.g. child’s wedding, milestone anniversary) — but that’s at the high end and should clearly match the occasion.
To keep it safely tax-free:
Occasion-based: The gift is clearly tied to a socially recognized event (wedding, birthday, graduation, etc.).
Proportionate: It doesn’t change the donor’s lifestyle or deplete assets.
Customary: It’s the kind of thing people of similar means might reasonably give.
Documentation: It’s helpful to note (privately) what the occasion was and the donor’s income level, in case of audit. There’s no need to declare it if it’s truly a présent d’usage.
If the amount goes well above 2–3% of income (say, >€15,000–€20,000 on €500,000 income) or there’s no special occasion, a notaire or fiscaliste should review it. The tax office could otherwise requalify it as a donation taxable at 60% (for non-relatives).
By Victoria Lewis
This article is published on: 21st November 2025
Deposit limit protection increase
From 1 December 2025 the Financial Services Compensation Scheme (FSCS) deposit protection limit will rise to £120,000. This means that if you hold deposits or savings with a UK-authorised bank, building society or credit union and it goes out of business, FSCS will compensate you up to the new limit of £120,000 per eligible person, per authorised firm.
The FSCS also covers temporary high balances, which will also rise from December, of up to £1.4 million. These may occur from major life events, such as selling a home or receiving an inheritance. Temporary high balances are protected for up to six months.
There are some details to be aware of:
A range of life events could create a temporary high balance in your bank account, including:
To verify the source of funds for a temporary high balance, the FSCS may ask for evidence which could include (but not be limited to) the following:
This list isn’t exhaustive, and the evidence needed will depend on your individual circumstances. If you provide the relevant supporting evidence and your claim is eligible under FSCS rules, compensation is payable within three months.
The previous protection limit was established in 2017, when the UK was a member of the EU. Following Brexit, regulatory control has returned to the UK, whilst inflation since 2017 has reduced the real value of the original limit. As a result, the FSCS has increased the protection level to ensure it remains equivalent in value to that provided in 2017.
While this increase is welcome, maintaining substantial cash balances in a bank account is generally not advisable over the medium to long term. We would be pleased to advise you on tax-efficient investment options for any surplus deposits you may hold.
By Katriona Murray-Platon
This article is published on: 9th November 2025
Autumn has officially arrived in France. The clocks have gone back, the air is cooler, and whilst grey, rainy days have set in, we can still look forward to the occasional burst of sunshine. November may be one of the shorter months, but before preparations for the end-of-year festivities begin, there are several important matters to keep in mind
Although the taxe d’habitation has become a thing of the past for most French residents, it still applies to owners of second homes in France. Over four million households are liable for either the Taxe d’Habitation sur les Résidences Secondaires (THRS), the Taxe sur les Logements Vacants (TLV), or the Taxe d’Habitation sur les Logements Vacants(THLV).
The Taxe d’Habiation statements should now be available in your online account on impots.gouv.fr, where you will also find the payment details and deadlines.
On 25th October, the French deputies voted to amend the draft finance bill that was proposing to freeze the income tax rates, instead voting in favour of re-establishing indexation in line with inflation which increases current tax bands by 1.1%. Below is a table showing the 2025 thresholds compared with the proposed thresholds for 2026.
| 2025 income tax thresholds | Proposed tax thresholds (increased by 1.1%) for 2026 | Income tax rate |
| Under €11,497 | Under €11,623 | 0% |
| Between €11,498 and €29,315 | Between €11,624 and €29,637 | 11% |
| Between €29,316 and €83,823 | Between €29,638 and €84,745 | 30% |
| Between €83,824 and €180,294 | Between €83,746 and €182,277 | 41% |
| Over €180,295 | Over €182,278 | 45% |
Once the finance law is officially adopted at the end of the year, I will confirm these thresholds.
If you are subject to Wealth Tax on Property (IFI) and the amount due is €300 or less, this must be paid by 17th November by cheque, cash or bank card or by the 22nd November if you pay online. If the amount is more than €300, it must be paid online via the impots.gouv.fr website.
By now, you should have received your income tax statement and paid tax due. If you have discovered any errors or miscalculations, please correct them as soon as possible as after 3rd December 2025 you will no longer be able to submit an amended tax return on the impots.gouv.fr website; any corrections after this date must be submitted in paper form.
If you have a PEL account which was opened between 2011 and 2015, your bank will automatically close it and transfer the funds to another savings account. PELs opened since 1st March 2011 can be held for a maximum of 15 years, whereas the PELs opened before this date can remain open indefinitely. According to the Banque de France, the average balance of a PEL account is €25,017, with around 12% of such accounts exceeding the maximum capital limit of €61,200. These accounts are not term accounts and should only be used if you plan to purchase a property or carry out renovations to your property.
If you do seasonal lettings, you will have received an email from the tax office reminding you that the tax rules have changed in 2025. For “meubles de tourisme non classés” if your income in 2023 and 2024 was more than €15,000 you can no longer stay as micro-BIC. The income that you received will be under the “régime réel” and will require the assistance of an accountant. You should contact your tax office for more information.
Urssaf also sent an email to remind those who earned over €23,000 from their season lettings that they have to pay social security contributions on this income and not social charges like other landlords. Depending on your turnover, you can opt for the micro-social regime at either 21.2% (for meublés de tourisme non classés) or 6% (for meublés de tourisme classés). From 2027, website-based business as Airbnb and Arbitel will take the social contributions directly at source.
If you have any questions on the above or any other matters, please do get in touch. I am available for online meetings or face to face meetings throughout November, so if you have any questions about your finances, please do contact me to arrange a free, no obligation, meeting.