
As John Cleese conceded in Monty Python’s “Life of Brian”, they did provide sanitation, medicine, education, public order, irrigation, roads, a fresh water and a public health system – oh and wine! However, they also came up with – pensions.
Viewing posts categorised under: France
What did the Romans ever do for us?
By Tim Yates
This article is published on: 17th February 2025
17.02.25
In 13BC Emperor Augustus had Roman soldiers stationed across the empire, including some poor souls stuck in Britain disillusioned with the weather and living conditions. To keep morale up, Augustus introduced the first Defined Benefit “Final Salary”, pension scheme. After 20 years’ service soldiers could retire with a lump sum equal to 13 years’ salary. It was initially funded by regular taxes but later by a 5% inheritance tax. Perhaps the UK Chancellor has been studying the Romans recently!
Not much then happened on the pension front until the 17th century when the Germans started the first pension fund in 1645. It was set up to provide benefits for widows of the clergy followed in 1662 by a similar fund for widows of teachers. It took another 200 years for civilian pensions to become widespread, with Germany leading the charge again under Chancellor Otto von Bismarck.
Fast forward to today and global pension funds hold over $55 trillion in assets. The largest 300 account for $22 trillion, with the top 10 holding $7 trillion. Japan and Norway’s government pension funds top the list at around $1.5 trillion each. The problem is that many of these funds (Norway being the exception) are struggling and are unsustainable in their current form.
Back in the 17th century, pensions weren’t costly. People worked until they dropped – literally. The pension age was 60, but the average life expectancy was only 45. Today, life expectancy in the Western world is over 80, and many retire in their mid 60’s, meaning pension funds have to support retirees for 15 years or more. That’s problem number one.
Problem number two is “lifestyle investing”. This affects Defined Contribution (DC) “Money Purchase” schemes. As retirement nears, fund managers gradually move investments from the stock market into government bonds, historically seen as the safest asset.
Bonds are basically IOUs and if issued by the UK government are called gilts (because the original certificates had gold leaf embossed edges). These bonds promise to return the initial investment after 10, 20 or 30 years, paying annual interest in the meantime. Investors typically don’t hold them until maturity but trade them in the open market instead.
Imagine in 2020, I borrowed £10,000 from you on a 10 year, interest only basis at 1% a year. At the time, it seemed a good deal – your bank was paying next to nothing. Now, in 2025, you realise you could lend that money elsewhere and get nearly 5%. But I’m not keen to repay early. Your only option, if you want the higher rate of interest, is to negotiate a lower payout, meaning you get back less than £10,000. That’s how bond markets work.
Before the UK’s 2015 pension freedom reforms, most people took 25% of their pension pot as a tax-free lump sum (tax free in the UK not France) and used the rest to buy an annuity which gave them a guaranteed lifetime income. Since 2015 when everyone was given the flexibility to do basically whatever they liked with their pension, most people have taken their tax-free lump sum and then left the remaining funds in “drawdown” – staying invested and taking an income every year – rather than buying an annuity. This seemed safe after decades of low interest rates. But rising rates in 2022-23, driven by inflation, caused bond yields to soar and bond prices to plummet, hammering lifestyle funds.
Charles Stanley, a leading UK wealth management firm, recently analysed the impact of over- reliance on bonds. If you had invested £150,000 five years ago in a portfolio with 80% shares and 20% bonds, it would now be worth £210,000. But if you had gone all in on bonds, your portfolio would have shrunk by 20% to £120,000. This illustrates the divergence between shares and bonds in recent years.
So, what’s the takeaway? First don’t panic. If you have a final salary (DB) scheme, you are protected – provided your scheme is well funded. If you have a DC pension but don’t monitor it , or don’t have someone reviewing it regularly on your behalf, then you should.
We get regular health checks. Our cars get checked once they reach a certain age. Pensions and other investments are no different. Regular reviews ensure you maximise returns, minimise tax exposure, provide financial security for yourself and your family, and avoid unwelcome surprises. After all, the Romans may have invented pensions, but it is up to you to make sure yours actually works for you.
‘Play it again ‘Uncle’ Sam’
By Peter Brooke
This article is published on: 4th February 2025

04.02.25
Looking forward to 2025
Another year and another wonderful Spectrum conference. More on that in a moment.
Last year, in Budapest, was my 20th conference with Spectrum after which I offered a fairly cautious outlook for the year to come. You can review my thoughts in The view from the Danube
I have now just returned from a superb four days in Casablanca, hence the name of this piece, which was our first ever conference outside of Europe. We had another great group of experts who shared their views on the key themes likely to shape 2025. From the future of US markets under Trump 2.0 to opportunities in bonds and the transformative power of AI; here’s a summary of the insights most relevant to your investments and financial goals. Overall I feel cautiously optimistic looking forward to 2025.
Market Highlights & Opportunities
US Exceptionalism: Can the Outperformance Continue?
Even with the slightly pessimistic outlook for 2024, the US stock market had an exceptional year, with the S&P500 delivering one of its strongest performances in history, though much of this was led by a small handful of stocks.
As we look to 2025, several factors suggest US markets could remain a standout:
-
Momentum: The US economy grew by 3.2% in 2023 and is forecasted to grow 2.8% in 2024, showing resilience despite high inflation and interest rates.
-
Earnings Growth: US companies are projected to achieve earnings growth of 13.8% in 2025—significantly higher than the 7.4% forecast for European companies.
-
Profitability: The US has long maintained a profitability edge over other developed economies, and Trump’s deregulation efforts could further enhance competitiveness.
-
Structural Advantages: Energy independence, favourable demographics, and leadership in technology (particularly AI) continue to position the US ahead of its global peers.
Trump 2.0: Pro-Growth Policies and Market Implications
With the Republican Party securing a clean sweep in the 2024 elections, President Trump is expected to have more freedom to implement his policies in his second term. Here’s what investors should consider:
- Focus on Stock Market Performance: Trump views stock market performance as a key indicator of his success, aligning his administration’s priorities with investor interests.
- Trade and Tariffs: ‘America first’ tariff policies aimed at encouraging manufacturing in the US could have a mixed impact—potentially limiting inflationary pressures but altering global supply chains.
- Tax Cuts and Deregulation: Further tax cuts and red tape reductions are likely. While tax policy changes may take time to impact the economy, they could provide immediate support to stock markets.
- Immigration: A crackdown on illegal immigration could weigh on certain sectors like agriculture, but a scaled-back approach may reduce the economic disruption.
- Geopolitical Stability: Trump’s administration is expected to focus on negotiations over conflict, which may support global market stability.While there are risks—such as high valuations in sectors like Artificial Intelligence (AI), the US markets remain supported by strong fundamentals, making increased exposure to this market a prudent strategy.
UK Bonds: A New Era of Opportunity
Bonds are regaining their appeal:
-
Attractive Yields: UK gilts are offering a 5.5% yield, equivalent to a real return of nearly 3%, presenting an appealing alternative to equities, especially in Europe.
-
Diverse Opportunities: Investors are also finding value in international bonds, including those from Portugal, Romania, and Germany.
-
Volatility Awareness: Bonds have become as volatile as equities, underscoring the need for a well-diversified portfolio.
AI: The Next Growth Engine
The AI revolution is driving innovation and creating new opportunities across industries. It is important to consider those companies who will be enabled by AI and who will earn from “enabling the enabled” as well as those companies supporting the infrastructure of AI.
Key investment areas include:
-
Data Ownership and Infrastructure: Companies like RELX (legal and medical data) and Equinix (data centres) are poised to benefit from the AI boom.
-
Efficiency Gains: Firms such as Rentokil and Waste Management are leveraging AI to optimise operations and drive growth.
-
Cloud Infrastructure: AI can’t happen without the Cloud.
Navigating Risk in 2025
Understanding and managing risk is critical to achieving long-term financial success. I will be writing a newsletter in the coming months focussing solely on ‘risk,’ but for now here are key considerations:
-
Inflation remains sticky: The risk of doing nothing could erode your cash’s value over time.
-
Volatility: Short-term market fluctuations are normal but tend to even out over time, emphasising the importance of staying invested.
-
Longevity: For couples, there’s a 50% chance one partner will live to age 90—making a long-term income strategy essential.
-
Sequencing Risk: Timing withdrawals during retirement requires careful planning to avoid depleting your assets prematurely.
What This Means for Your Portfolio
With markets adapting to new norms, a balanced and diversified approach remains crucial:
-
US Market Focus: While US equities remain a core component, avoiding over-concentration in sectors like AI is vital. Just 7 companies make up 33% of the S&P 500 index and contributed 55% of all the returns of the S&P500 in 2024 – the largest concentration in history.
-
Employ Active Managers: Passive investors have had a great run, especially if invested in US equities but as we have already seen this month the AI Titans have sold off on one piece of news from China. Active managers will control these concentration risks.
-
Global Bonds: High yields make bonds an attractive addition to portfolios, particularly for those seeking income and stability.
-
Alternative Investments: Assets like gold can provide a hedge against geopolitical risks and inflation.
I would very much like to thank the investment management teams at RBC Brewin Dolphin, Rathbones Investment Management, Evelyn Partners, New Horizons, Alquity Investments, VAM Funds and Prudential International for their time and expert views for the content in this update.
Here are some links to other articles supporting this summary if you want to dive deeper into the details:
US Continues to Outperform https://www.evelyn.com/insights-and-events/insights/can-us-outperformance-continue/
A look back on 2024 https://www.evelyn.com/insights-and-events/insights/2024-investment-review-ifa/
Trump 2.0 https://www.lgtwm.com/uk-en/insights/market-views/trump-politics-the-global-order-250934
The excellent monthly Rathbones Sharpe End Podcast https://www.rathbonesam.com/uk/sharpe-end-podcast#podcasts
French financial update February 2025
By Katriona Murray-Platon
This article is published on: 3rd February 2025
03.02.25
In January at our annual conference in Casablanca it was nice to escape the cold, dark mornings of France and get a bit of sunshine. It was an interesting and informative conference thanks to our product providers bringing their various observations and opinions about investment markets and geopolitical events.
On 20th January, just as we were arriving at our conference, Donald Trump was sworn in again as the American president. He wasted no time getting to work with executive orders. On day two of our conference, Rathbones Asset Management presented their views on what we can expect from Trump 2.0. The phrase “Drill, baby, drill” was mentioned more than once – like his first term in office, we can expect (to the extent that Donald Trump’s decisions can be predicted) that he acts to protect American interests and American businesses with tax cuts and less regulation, which in turn is likely to be good for the US economy. This time around it looks like he has his eye on imposing tariffs on everything.
There was much talk about how well the US market had done last year. However, Rathbones also highlighted the following:
- 29% of the global stock-market (as measured by the FTSE All World index) is now in the technology sector, and of this, 19% is concentrated in just seven companies
- 65% of the FTSE World index now comprises US companies
- the top 10 holdings in the FTSE World index account for 23% of the index’s total value
So, whilst markets (and investors’ portfolios) have performed well, the dominance of the “Magnificent Seven” is a concern for some investors.
On the subject of risk, RBC Brewin Dolphin gave us a fascinating presentation on this important aspect of investment management. We often associate risk with the possibility of something bad happening if we take a certain action. Whereas is in practice there is risk in everything we do and everything we don’t do. Over the past few years, the negative impact of inflation on the value of our cash has been significant. For the long-term investor, though, with sensible planning, there is the opportunity to protect capital from erosion by inflation and to achieve strong ‘real’ returns.
It is important to review your appetite for risk regularly. The risk of being too cautious in your investment choices, for example, may lead to disappointment in the years come.
On day three of our conference, which was the second day of Donald Trump’s second term in the White House, he had already introduced executive orders and other measures, which meant that our presenters, Evelyn Partners and LGT Wealth Management, had fresh insights for us. This is likely to be an ongoing theme of Trump 2.0 – there will be lots of change, there will be lots of noise, there may be action that may need to be reversed for not complying with the law and/or the US Constitution, and there may be controversy. However, as controversial as Donald Trump is, and regardless of your personal views on his character, the consensus is that he will be good for the markets.
Prudential International told us about their funds’ positive performance in 2024, how inflation seems to be easing and how property values are showing signs of stability. In 2024 Prudential completed investments in two French forward living projects, notably Clichy Rue du 8 mars, in Paris, and Aurientis, a senior living development in Aix-en-Provence. They now have their sights set on projects on Rue de le République in Lyon, Leadenhall in London and Haymarket in Edinburgh, which are scheduled to complete by the end of 2025.
There were mixed views from our presenters on whether bonds would be a good investment in 2025. New Horizon Asset Management gave us their predictions for 2025 and showed us which of their predictions in 2024 had been accurate.
I have spoken to many people in the past about some UK pension providers requiring them to buy an annuity. Conversely, without a UK address, an annuity is generally unavailable to British expats in France. This however is not an obstacle to successful retirement planning. We work with international pension providers such as Novia Global and iPensions who provide low-cost pension solutions, with a range of investment opportunities, and the option to receive payments in Euros or Sterling. If you or someone you know would like to arrange a free, no obligation, pension review, please get in touch.
In France, there is still no finance bill, which is a cause for concern. Recent issues of Le Particulier magazine (I am a subscriber) have been rather thin. There is some financial news however that may be of interest. New PEL accounts, opened since 1st January 2025, are now paying 1.75% interest as opposed to 2.25% previously. Also, your electricity bill should reduce by around 14%, from 1st February.
If you are heading to Bordeaux, or to any of the other major towns in France, you will need to have a Crit’Air sticker in your car as of 1st January 2025.
Finally, as a reminder, please be vigilant when communicating with financial institutions. You can now look on the impots.gouv.fr website for accounts registered in your name, a worthwhile exercise to check for any that you may have forgotten about, or which may have been opened without your consent (unlikely, but worth checking). You will find this in the “other services” tab on the Impots website.
If you have any questions on any of the points made above, please do get in touch.
Financial update December 2024
By Katriona Murray-Platon
This article is published on: 4th December 2024

04.12.24
The year 2024 is drawing to a close. Financially it has been a rather good year in the markets with a lot of our clients’ portfolios doing much better this year than previous years. Even as you start to prepare for Christmas or wind down at the end of the year, there are still some financial points you should be aware of.
The interest rates on the Livret A and the LDDS savings accounts will reduce from 3% to 2.5% next year (probably in February). Even though the rate has dropped these accounts are still a good place to keep money needed for the short to medium term. Any amounts that you do not foresee needing or you want to get a better return from without paying tax, should be put into an assurance vie.
Christmas is a time for giving whether that is to families or charities. Although gifts to friends and family normally have to be declared, for events such as birthdays or Christmas, you can give money to your loved ones without having to declare these amounts to the tax office. This is known as a “presents d’usage”. If you wish to give money by bank transfer it is advisable to put on the transfer order the words “Présent d’usage pour Noel” so that there is no doubt about the fact that it falls under the exemption.
If you haven’t been giving to charity regularly over the year, now is the time to gift money to any worthy causes. Gifts to charities of general interest or recognised as of public utility in France would allow you to benefit from a tax reduction of 66% of the amount gifted up to a maximum amount of 20% of your taxable income. Gifts to charities who help those in difficulty receive a tax reduction of 75% of the amount gifted for amounts under and including €1000. Any amount over €1000 will get a tax reduction of 66%. In both cases the tax reduction cannot be more than 20% of your taxable income.
You have until 4th December to amend your 2023 tax return online from your online account on the impots website.
After this date you will only be able to submit a paper return with any amendments.
Until 12th December you can change the amount of the 60% advance that you will get for your tax credits and reductions which is normally paid mid January.
December is the last chance to add some money to your PER retirement accounts if you have the money to do so and if you want to reduce your tax liability. You can put as much as you like into the PER but the tax benefits are limited to either up to 10% of your annual income up to a certain amount or 10% of the PASS (see below). You may also use any unused amounts from previous years, these will appear on your 2023 tax statement. This amount is deducted from your taxable income before being assessed at your marginal rate.
The PASS (plafond annual de la sécurité sociale) has increased by 1.6% and is set at €47,100 for 2025 or a monthly amount of €3925 (compared with €3864 in 2024). This has an impact on the maximum amount you can receive from daily sick leave pay for occupational illnesses or maternity pay, disability allowances or French pensions. It is also used to calculate the maximum amount you can pay into a PER retirement account.
There are still a few weeks in December and I will be working until 20th, seeing existing clients and meeting new ones. We are going to spend a few days in London and then travel up to Liverpool to spend Christmas with my family.
I hope you have a lovely holiday season with all your friends and family and I look forward to bringing you more financial news and information next year.
Nice-Cannes Marathon 2024
By Peter Brooke
This article is published on: 2nd November 2024
02.11.24
Run with Purpose: Peter Brooke and The Spectrum IFA Group Take on the Nice-Cannes Marathon 2024!
On November 3rd, Peter Brooke from The Spectrum IFA Group will proudly run with The Run for Hope Team in the Nice-Cannes Relay Marathon. For years, Peter and Spectrum have embraced this challenge, raising awareness and funds for a cause that deeply resonates with them.
The Run for Hope team, is a partnership between Mimosa and Cancer Support Group 06, brings together a community of runners from beginners to experts, inspiring teamwork and fun to raise funds for cancer support by running in the Nice-Cannes Relay Marathon. Participants enjoy comprehensive training, support and a festive after-party, all contributing to a great cause, the support of cancer patients on the French Riviera.
As experts in financial planning for English speaking expatriates living in Europe, The Spectrum IFA Group provides comprehensive and personalised financial advice, and planning. Peter, who has been with Spectrum for 20 years on the French Riviera understands the complex financial and tax issues his clients face and he and Spectrum are dedicated to helping you navigate these challenges.
By participating in the relay marathon, Peter and Spectrum demonstrate their commitment to the broader community on the Côte d’Azur. Supporting The Run for Hope Team allows them to blend their professional expertise with their passion for making a difference. Cheer on Peter and the whole Mimosa team as they run for hope, showcasing the same dedication they bring to managing your finances.
Together, we can achieve great things—both on the marathon route and in your financial journey!
The Spectrum IFA Group: Running for Hope, Running for You!
The relationship with a financial adviser
By Victoria Lewis
This article is published on: 31st October 2024
31.10.24
The majority of individuals that receive professional financial advice across the UK have remained with the same adviser throughout, a new study by St. James’s Place (SJP) reveals, highlighting the power of longstanding advice relationships. Just under 12,000 UK adults were surveyed this year and the results show financial advice and guidance can benefit immensely.
More than 62% have never switched their financial adviser, rising to nearly 75% for those aged 35 and over.
The study also found that the typical relationship with a financial adviser or advice firm lasts around 7 years, but this increases to over a decade for those aged 55 and over – with nearly 31% of this generation having been with their adviser for 16 years or more.
Trust, understanding and financial satisfaction are the main reasons for never switching financial adviser:
• Trusting their adviser
• Being happy with the advice and financial returns their adviser has delivered
• Their adviser understanding their financial situation
• Having a good relationship with their adviser which has been built over several years
• Their adviser understanding their long-term goals and helping to deliver them
• Their adviser looking after both them and their family
• Their adviser having helped them through big life stages/ moments
SJP said: “Financial advice is about much more than numbers on a page or graphs on a screen.
It’s about building deep, meaningful relationships, and as our research shows these can last many years and span generations.
Whether you’re navigating the early stages of wealth creation, planning for retirement, or managing an unexpected life change, having a trusted adviser by your side can make all the difference.
These were the main reasons cited for working with a financial adviser on an ongoing basis:
• Putting the foundations in place for a stronger financial future
• Helping them to save more money for retirement
• Ensuring they have adequate protection in place if they need it
• Getting on the property ladder
• Navigating difficult periods like divorce or bereavement
• Pass on money to their children or loved ones
• Better manage the cost of raising children
• To provide more financial support to elderly family members
Andy Payne continues: “These goals, moments and milestones may be common to many throughout their lives, but the specific circumstances will always be unique. Having support from an expert financial adviser, with not just the technical expertise but the empathy to deploy it sensitively and with their clients’ needs in mind, can be the difference between a hope dashed and a dream realised.”
If you have already have a financial adviser but doubt if they are the right person for you, perhaps it’s time for a change?
Or perhaps have you been struggling to navigate your financial planning on your own?
I have worked with Spectrum as an International Financial Adviser for over 21 years and still look after my clients who worked with me from the very beginning. I advise the children of my clients now and even other family members too.
The synergy I have with my clients is because we understand each other – our relationship is based on trust and confidence and I know it’s an enjoyable experience because they recommend me to their family and friends. That’s the greatest endorsement I could wish for.
French Bank Accounts
By Occitanie
This article is published on: 22nd October 2024
22.10.24
Back to basics – an overview of some French bank accounts.
French Interest-Paying Bank Accounts
Whether your level of savings is modest or if your financial circumstances are more comfortable, we recommend that everyone considers using one or more of these accounts available from all banks in France.
These accounts pay interest and there are several available, depending on your circumstances, all providing a modest risk-free return on your savings.
In addition to paying interest on funds deposited, the other benefit common to all these accounts is that the interest payable is exempt from tax and social charges.
Livret A
Eligibility: Open to everyone with a minimum deposit of €10 (only one account per person) and offered by all banks. There are no requirements in relation to age, nationality or tax residence.
Permitted Value: Once the balance of the account reaches €22,950 (whether by deposits or interest or a combination of both), no further deposits can be made but interest can take the balance beyond this maximum.
Current Rate of Interest: 3% per annum
Livret de Développement Durable et Solidaire (LDDS)
Eligibility: Available only to adults who are tax resident in France and offered by all banks. Only one account per adult and no more than two accounts per tax household.
Permitted Value: Once the balance of the account reaches €12,000 (whether by deposits or interest or a combination of both), no further deposits can be made but interest can take the balance beyond this maximum.
Current Rate of Interest: 3% per annum
If you are an adult tax resident in France, it is possible to hold one each of the above. For example, a married couple can hold two Livret A and two LDDS accounts between them with a maximum deposit of €69,900.
Livret d’Epargne Populaire (LEP)
Eligibility: Available at banks, this account is specifically for those on more modest incomes. This account is only for adults and those who are tax resident in France with a limit of two accounts in a tax household.
As this account is focussed on those on modest incomes only, income ceilings apply. If opening an account in 2024, your tax income in 2023 will be referenced. For example, for a 1-part tax household, the ceiling is currently €22,419 and for a 2-part tax household, €34,393.
Permitted Value: Once the balance of the account reaches €10,000 (whether by deposits or interest or a combination of both), no further deposits can be made but interest can take the balance beyond this maximum.
Current Rate of Interest: 4% per annum
Livret Jeune
Eligibility: This account is reserved for young individuals between the ages of 12 and 25 years. An account can be opened with a minimum deposit of €10 with funds freely available from the age of 18 years. Up until the age of 16, minors must obtain the authorisation of their legal representative to make a withdrawal and between 16 and 18 years of age the legal representative has the right to object to a withdrawal request. Only one account is allowed per person.
Permitted Value: Once the balance of the account reaches €1,600 (whether by deposits or interest or a combination of both), no further deposits can be made but interest can take the balance beyond this maximum.
Current Rate of Interest: The current rate of interest can be set freely by the bank but must be no lower than that of the Livret A (currently 3% pa).
The accounts outlined above are always worth using for immediately accessible funds which provide a return which is exempt from tax and social charges, however, the interest rates currently available are the highest for years and will start to decline, with a first reduction likely in January 2025.
Next time
In our next article we will focus on savings/investments where no limits on the investment value exist and where the potential for greater returns is possible. With additional benefits, including tax efficiency and significant inheritance benefits, all roads lead to the Assurance Vie!
If there are any subjects you would like us to cover in one of these articles or if you would like to contact one of our advisers for a financial consultation (no fee), then please get in touch at info@spectrum-ifa.com
Le Tour de Finance 2024
By Spectrum IFA
This article is published on: 14th October 2024
14.10.24
Despite stormy conditions locally, our 152nd Le Tour de Finance event was well attended in the beautiful setting of Chateau Val Joanis, north of Aix-en-Provence.
Our expert panel, hosted by Jonathan Goodman and Victoria Lewis of The Spectrum IFA Group, included assurance vie provider Prudential International, Novia Global Pensions, investment manager RBC Brewin Dolphin and tax lawyer AGN Avocats.
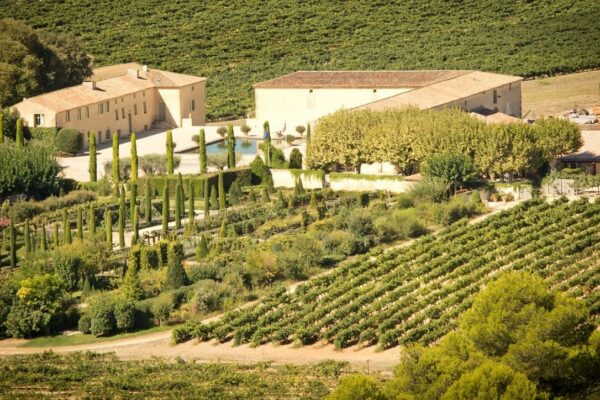
Quick-fire questions and answers on wide-ranging subjects allowed the panel to share their knowledge in an informative and interactive format over 90 minutes followed by a delicious buffet lunch and wine.
Our 153rd Le Tour de Finance event was well attended on the 9th October at the Chateau de Saint Martin in Taradeau in the Var.
Our expert panel, hosted by Jonathan Goodman and assisted by Tim Yates and Lorraine Chekir – all of The Spectrum IFA Group, included assurance vie provider Prudential International, Novia Global Pensions and investment manager RBC Brewin Dolphin.
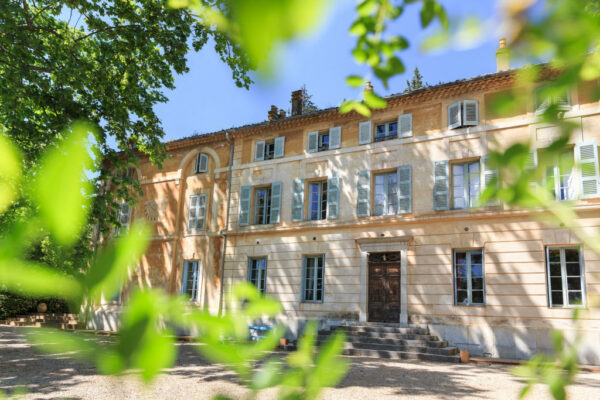
The format was a question and answer session over a period of 90 minutes or so with some of the questions pre-prepared but many also coming from the audience. The questions were wide ranging covering subjects such as assurance vie, pension transfers, fund management, portfolio construction and tax treatment. These allowed the panel to share their knowledge on all these diverse but highly relevant topics in a lively and interactive way. A number of people commented after the seminar that they appreciated the format and that it was better than having people simply standup and lecture to them on their chosen subjects. They also found it refreshing that the emphasis was on being informative with no attempt at a “hard sell”. The event finished with an excellent buffet lunch with wine.

ESG and Impact Investing
By Richard McCreery
This article is published on: 8th October 2024
08.10.24
Impact investing is increasingly becoming an important element of ESG-orientated investment portfolios.
Many people are familiar with the concept of sustainable investing, where a company may incorporate Environmental, Social and Governance (ESG) principles into its decision-making and risk management.
The aim is to promote positive long-term values that should improve the way a business is run by aligning its interests with those of society.
For example, in order to improve its effect on the environment, a company may introduce measures to reduce its carbon footprint, to minimize the use of finite resources or to eliminate waste. To improve the way it plays its part in society, it may insist on minimum standards in labour practices in its supply chain, it may introduce policies to expand its gender diversity or it may fund projects that build its standing in the community. When considering governance issues, a company might focus on how it balances executive compensation with performance, it might assess how ethical its operations are or it may improve transparency in its financial reporting.
Over the long term, it is believed that a more principled company culture that ultimately makes it more sustainable will improve the financial performance of that business, creating a win-win for all stakeholders. That is why the global ESG investing market was estimated to have grown to more than $25 trillion in size by 2023.
Sustainable investment funds that invest in a range of underlying companies may choose to exclude certain industries or sectors that don’t comply with ESG principles, such as gambling, tobacco or controversial weapons. But they may also choose to favour companies that have a strong ESG rating, that have made a conscious efforts to develop better behaviour along defined guidelines, such as those laid out in the United Nations 17 Sustainable Development Goals.
Impact investing goes one step further, because it favours companies that intentionally make a measurable positive contribution towards solving environmental or social problems alongside a financial return. It fills a funding gap when traditional philanthropy and government aid might be insufficient. Investments could be in healthcare, education, recycling, social housing, sustainable agriculture or climate change action. For example, investing in a renewable energy company could positively impact climate change, whilst investing in a plant-based meat company could positively impact public health and the environment.
Today, fund managers can incorporate impact investing into their sustainable funds or as part of an overall ESG strategy, ensuring that investors have the opportunity to make a financial return and generate a positive return for society. As you would expect, the addition of investment criteria other than just financial performance means that more work has to go into researching and selecting the best investments. However, clients can gain exposure through individual funds or managed portfolio services that offer liquidity, expertise and ongoing monitoring to ensure that goals are met and principles are adhered to.
If you would like to find out more about how to align your investments with ESG criteria and make impact investments, please get in touch.
At Spectrum, whilst we are committed to offering comprehensive solutions for sustainable investing, we also believe that all clients should decide freely on how to allocate their capital. We recognise too that no single, simple solution exists for how to invest responsibly. For these reasons, we include responsible investment discussion in our advice process but do not impose personal or corporate views.
Financial update France October 24
By Katriona Murray-Platon
This article is published on: 5th October 2024
05.10.24
As we head into October, this means that we are now three quarters of the way into 2024. When we look at the markets we can see that in spite of a short dip in August, the year to date figures for almost all of the main market indices are showing performances in the double figures.
Autumn is the season for what are known as local taxes, i.e. the taxe foncière, taxe d’habitation and tax on vacant lodgings. Whilst the taxe d’habitation only affects those with second homes, taxe foncière has to be paid by all property owners. Properties that are inhabitable but remain vacant, which are situated in one of the 3697 communes listed in the decree number 2023-822 of 25.08.23 and which have been left unoccupied for at least a year as at 1st January of the tax year may be subject to the annual tax on vacant lodgings. For a property to be liable for this tax in 2024 it must have been empty since 1st January 2023. If it has been vacant for 2 years since 1st January 2022 there may be a local tax on vacant lodgings which may apply.
The Taxe Foncière statement should already be available in your account on the impots website. This must be paid by 15th October or you have until 20th October if you pay online. It doesn’t need to be paid all at once, you can set up monthly payments so that by the time October comes along you will have paid most of it with the extra amount being paid in November. Whilst the Taxe Foncière will increase again this year, not everyone has to pay it. Those on benefits (ASPA, ASI) are exempt as are those who are aged 75 or over on 1st January of the tax year and those on disability allowance (AAH) provided that their annual taxable income is under €12,455 per person or €19,107 for a couple. If you fall under the income threshold and are over 65 on 1st January there is a €100 reduction. There is no need to notify the tax offices, any exemptions or reductions will apply automatically provided that you meet the income conditions. However there may be extra allowances granted by your local authority so it is worth making enquiries.
The housing market in France is improving in spite of a difficult first half of the year. As several of the main central banks have started cutting their rates, the mortgage rates are also falling. According to our Spectrum International Mortgages expert Patricia Nadal, the average rate over 20 to 25 years granted in September was around 4.30%, compared to the average of rate for the same length of time in June which was around 4.45%.
The banks are also being more flexible in their requirements for granting mortgages. In the UK even though the Bank of England voted to keep their rate at 5%, mortgage rates have fallen to 4% with some just under this rate.
From 24th October 2024, anyone opening a new French assurance vie or PER will now have the possibility of investing in venture capital investment funds. These are only for those with a balanced risk profile (around 4% of the investment) and adventurous profiles (up to 8% of the assets). There is no obligation to invest in such funds for cautious profiles. For PERs it will depend on the attitude to risk of the policy holder and how long they have until retirement. Also, from the same date, if you have a PER they will now be able to offer more adventurous investment strategies.
Although the weather may be getting cooler and you want to spend more time indoors, if you have any financial questions you would like answering, I would be happy to arrange a video call or I could come and meet you in the comfort of your own homes. Please do get in touch to arrange a time that would suit you best.