
Save money on charges
I have to tell you about ‘una scoperta’ recently. I have been an account holder at Revolut bank for a year or so now. Revolut being the online bank but did not have a national presence anywhere other than the UK (I think) Well, that all changed recently and it opened a full Italian online banking operation (plus a number of other European fully operational online banks). I converted to the Italian bank when notified.
Viewing posts categorised under: Italy
Revolut – it’s now an Italian bank
By Gareth Horsfall
This article is published on: 17th September 2026
17.09.26
This is not the interesting part. The better news is that over the summer I had another one of those bills to pay to a comune, or a multa or something and I was moaning, again, at the fact that you always have to pay about €1.50 to some entity somewhere, or worse €1.95 in the post office or in the tabaccheria, even when I am spending the time to input the payment myself online. This annoys me so much! In fact, I get quite furious about it. Banca Intesa charges me €1 every time I make a bonifico from my business account. I see red every time. I mean why, when I am entering the data myself on my phone and spending my time to enter the bonifico ONLINE should I have to pay €1 to the bank?
Well, the fantastic news is that I discovered, (through an AI search, ironically) that Revolut does not charge those pesky bank charges, neither for bonifici nor bill payments, nor comune payments, nor Agenzia delle Entrate payments. I think that this could save me in the region of about €100 a year, approximately.
And besides the cost savings the Revolut app is fantastic and much easier to use than any other Italian banking app I have. So, I am a convert. I hope they use this as disruption to the Italian banking sector and bring some positive change because, quite frankly, the time is up for charging to send payments in Italy! When disruption makes companies more competitive and treats clients better than before, this is my kind of capitalism. (I just hope they don’t fall in line with the other Italian banks, over time)
The death of original content – The AI takeover
By Gareth Horsfall
This article is published on: 16th September 2026
16.09.26
Over the summer I have been seeing alot written about AI, most of which I take with a pinch of salt, but one headline that appeared in my inbox was the following:
Bot and AI overtake human-generated web traffic for the first time; we are in the age of the “Dead Internet”
According to data from Cloudflare, automated bot and AI agent traffic has surpassed human-generated web traffic for the first time in history, with 57.4% per cent of requests to websites it hosts being automated bot requests, while only 42.6% originate from human users. Matthew Prince, co-founder and CEO of Cloudflare, expressed surprise at the speed of the transition from human-generated to computer-program-generated content. He expected this would happen towards the end of 2027.
This, for me at least, is alarming. Not because automated AI generated content will surpass human generated content, I think that was almost inevitable but because AI models are all fishing in the same pond. I don’t know enough about how well AI can generate new creative ‘original’ ideas, but I am almost certain that it will never surpass the human capability to create and innovate, therefore it does leave you wondering to what extent the information we are getting from Chatgpt or Claude, or any other open source AI model, is just recycled from the same information which AI put there in the first place. I am sure the more technologically advanced amongst you may be able to educate me on this point, but unlikey to convince me that the loss of original human generated content is not just a loss for us all, but also very dangerous when looking to make important decisions based on information which for all intents and purposes can be wrong. The level of error in AI generated search results, for example, is something that worries investors in its longer term application.
(Please remember that my Ezine’s are human generated and researched (using minimal AI input)!
We must adapt
Having said all this above, we have no choice but to adapt. Here is a good point to tell you a personal story about my own family name history. I have written about this before but it is good to remind you of it, given the context.
My name is Horsfall!
For those of you who are familiar with industrial revolution history in the UK, you may be award of the Luddites. In Huddersfield, where I am from, they were a group of people who worked in the textile industry and who were involved in the finishing of cloth by hand. The introduction of machinery, which both streamlined the operation and made it much quicker, put their jobs and livelihoods at risk and as a result they organised themselves into groups who went around the mills destroying machinery. In 1812, a man named William Horsfall (a direct line ancestor), a mill owner himself, and a vocal opponent of the Luddites, was also an advocate of installing machinery in his factories, to modernise, streamline and introduce efficiencies and greater productivity. On his horse, coming back from the market one Tuesday morning, he was shot and killed by the Luddites. This culminated in the death of the Luddites movement because the police immediately swooped in to avoid similar occurrences happening. However, the term ‘a Luddite’ became synonymous with people who are opposed to technology, automation and modern working methods. (If you want to see the full family story you can click HERE)
Personally, I don’t like AI in it’s present form (although I recognise it’s application in business to make things easier), but I know it’s here to stay and as Jensen Huang CEO of Nvidia recently said:
“You are not going to lose your job to AI, but you are going to lose your job to someone using AI”
Here are a couple of interesting slides about AI, courtesy of our friends at Evelyn Partners Investment Management
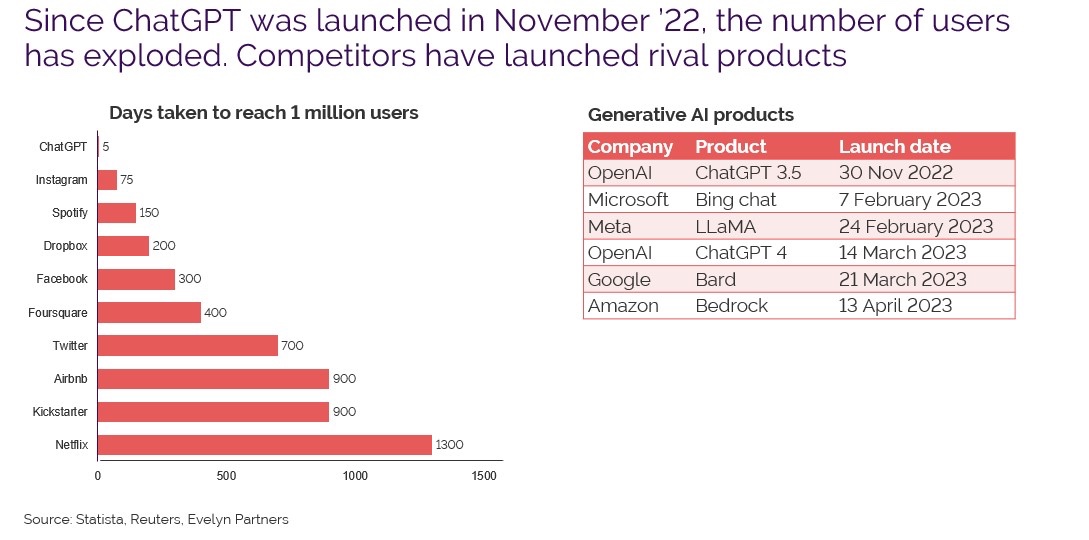
Jobs will change, but not be lost.
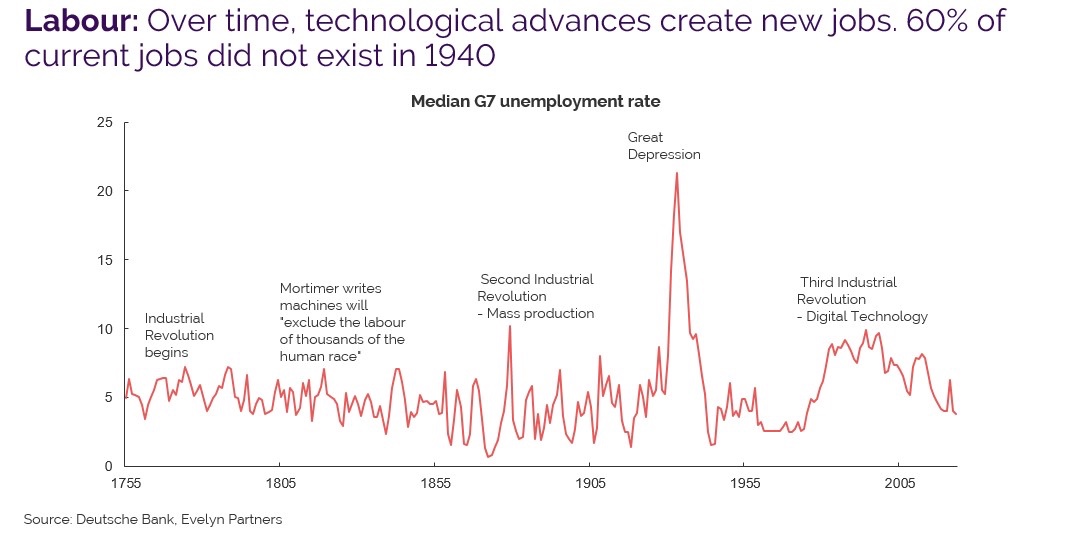
This slide particularly interests me because it goes to show the power of human ingenuity. As we can see, apart from the great depression, unemployment levels have largely hovered around the 5% mark since the 1700’s, over which time we have seen the introduction of so many new technologies – in no particular order: the train, car, aeroplane, the telephone, machines in factories, the radio, TV, the washing machine, going into space, the cell phone, computers, the internet, and now AI.
Influencing
I think one of the best examples of this human adaption is the job of the influencer. 10 years ago, internet influencers never existed. Yet now, people are making millions from online ad revenue, quite often it is completely useless content, but which creates the clickbait required to generate income. It is also becoming a life saver for certain sectors, such as farmers, to sell direct to the public instead of through distributors or to supermarkets. The internet and now AI has, in a way, democratised the world of work in professions which, previously, had been reserved for a select few. Now, more opportunites are available to the masses.
I have noticed this myself because in my efforts to understand the world of the land a little bit more, I have done a lot of research online and come across many people who have created Youtube or TickTok channels, producing short videos on the things they do on their land and the methods they use. One development I have noticed is that when these influencers seem to reach a critical mass of followers, subscribers and likes, then they suddenly start appearing with tools sponsored by certain companies and they start writing books for sale. It is well known that generating revenue through subscribers, followers etc is not going to a create a big and reliable long term income stream, but ancilliary product and services, sponsors and driving traffic through your website, seems to be the way to go.
Influencers – a job also at risk of AI
However, the influencer space may also be a ‘job’ under threat, with the rise in automated traffic, as explained above, this presents challenges to their economic model. Bots do not click on ads, which raises questions about how content creators can generate revenue in an increasingly bot-dominated landscape. As a potential solution they could charge bots for access to digital users’ content. Like every other employment, it will have to adapt to a rapidly changing future.
What the jobless numbers can tell us about the growth in AI
I will finish my section on AI with this, because it really puts into context why AI, robotics and automation are going to play an increasingly large part in our lives.
At the beginning of August new jobless claims were announced in the USA. New filings for unemployment benefits dropped to 187,000 for the week ending July 18 — a nearly 57-year low, and a much bigger drop than economists expected. This is probably not a cyclical blip. It’s demographics finally showing up in the data. Birth rates across the developed world — the U.S., Europe, Japan, China, South Korea — have been falling for decades, and it’s finally catching up. Fewer young workers are entering the work force every year than are retiring from it. This is basically a structural worker shortage, and jobless claims sitting near six-decade lows is exactly what you’d expect that shortage to look like on paper: a “low-hire, low-fire” economy where employers are desperate to hold onto the workers they already have. (I think about our friends in N.Italy who run a number of bars and they can never find trained staff and spend most of their time interviewing, hiring and firing. It has become their biggest headache). However, a labor shortage this bad can’t be solved through immigration, fast-enough, to mitgate your way out of a birth-rate collapse, and you definitely can’t train workers who don’t exist.
The only option left is productivity — which means robotics, automation, and AI aren’t optional anymore. They’re the only way to keep the economy growing when the number of available humans is shrinking. That’s why capital is pouring into automation and AI — this is not an passing fad, this is the innovation cycle!
Is this an investment opportunity?
Many of you have quoted me headlines that there is an AI bubble just waiting to burst and that a market crash will be lead by over speculated AI stocks. There is probably some truth in the fact that there are companies out there who have overly inflated valuations due to the hype around AI. However, the question is whether a revaluation of these stocks alone would be enough to generate a full market crash, or maybe a correction.
Major innovation cycles have never been cheap, and they’ve never been non-inflationary. Every prior boom — the 1970s energy and productivity shock and others — was accompanied by a commodity repricing. Building new infrastructure and new machines at scale means real demand for real materials.
Put it all together: a demographic worker shortage forcing an automation super-cycle, requiring a huge amount of hard assets (commodities) to build it all out. The smart money has already moved away from the speculative AI firms who may see a revaluation sometime soon, into the resource based companies who are going to be building the infrastructure to take us into this innovation era.
Artificial Intelligence: Opportunity, Risk, and a Question Bigger Than Markets
By Andrew Lawford
This article is published on: 16th September 2026
16.09.26
AI has moved from research lab to the centre of global capital allocation faster than almost any technology before it. Goldman Sachs Research projects worldwide AI-related investment will exceed $1 trillion in 2026, with about $581 billion of that in the US alone. At 2-5% of GDP, this peak intensity is comparable to prior general-purpose technology buildouts — railways, electrification, the internet — though compressed into a far shorter timeframe.
Where the opportunity lies
The clearest opportunity is infrastructure: chipmakers, power and grid companies, and data-centre suppliers behind AI’s physical build-out. A second lies in software and services companies genuinely embedding AI and showing measurable productivity gains, rather than simply attaching the label. A third is second-order: healthcare, logistics, and financial services benefiting from AI-driven efficiency without being “AI plays” themselves. For cross-border clients, diversified thematic exposure, rather than concentrated single-stock bets on US mega-caps, is usually the more sensible route in.
Where the risk lies
The most immediate risk is circularity: a meaningful share of AI capex is financed by the same handful of companies that supply and buy from one another, so returns are more sensitive than headline growth suggests to any slowdown in adoption or rise in the cost of capital.
Concentration compounds this — a small number of companies drive a disproportionate share of both AI capex and recent index gains, so even diversified portfolios may carry more AI-specific risk than clients realise. And the return on this capital is genuinely uncertain: even Goldman’s own analysis calls AI spending a “key source of uncertainty for macro markets,” without forecasting whether it will pay off.
The existential question
Clients increasingly ask directly: could AI pose a genuine risk to humanity? Honesty about uncertainty matters more here than a confident answer either way, because expert opinion is genuinely split. A recent academic survey found two coherent camps — those viewing advanced AI as a powerful but controllable tool, and those viewing sufficiently autonomous systems as a harder-to-control risk. Disagreement correlated less with general AI expertise than with familiarity with specific technical concepts, such as the tendency of highly capable, goal-directed systems to develop self-preservation sub-goals; researchers less familiar with such ideas were markedly less concerned. Still, 78% of surveyed experts agreed that technical AI researchers should be concerned about catastrophic risks — real agreement on direction, even amid disagreement on scale and timing, which most estimates place in decades rather than years.
A balanced conclusion
AI will likely remain a defining investment theme this decade, and exposure to it is reasonable. But the same technology is the subject of genuine, unresolved expert disagreement about its longer-term risks to society. The sensible approach: disciplined, diversified exposure to the theme, awareness of concentration already embedded in portfolios, and honest acknowledgment that both AI’s financial and societal trajectory remain more uncertain than its loudest advocates or critics currently claim.
Perhaps it will come as no surprise (or perhaps I’m just hoping that readers recognised the above for what it was!) when I say that everything written before this current paragraph was generated by AI (Claude in this case), based on the following prompt I had given it (please note that Claude knows what work I do and that I am based in Italy):
“I need you to write me an article that I will distribute to my clients. The topic is AI and its opportunities and risks from an investment standpoint, as well as a balanced discussion of whether or not there are existential risks to humanity over the medium to long term. Max 1000 words”
It took about 2 minutes to generate the response, which I subsequently asked it to shorten to no more than 500 words and which I have not edited at all. To me it seems like a competent, if somewhat uninspiring commentary on the current AI debate and its consequences for investors. I’m not sure that it has really given me any great insights beyond what one would glean from reading a modest amount of financial journalism and from being generally interested in the subject. In fact, I find myself wondering if these sorts of AI-generated documents “are simply the copy of one thousand summaries” (solo la copia di mille riassunti) as Samuele Bersani put it in his song Giudizi Universali.
Needless to say that the topic of AI must be taken into consideration when investing, yet we must acknowledge the limits of our understanding in terms of how all of this plays out. I think it is wise to exclude the potential for an existential crisis of humanity from our calculations, mainly because if that scenario does unfold, rather like a global nuclear war, we will have more important things to worry about than the value of our investment accounts. On a more moderate view, there will be beneficiaries and victims of AI that we cannot even begin to imagine, and we must maintain a fully diversified approach and understand how much exposure we have to certain types of investment.
One of the first things I do when evaluating a portfolio is try to get an understanding of the underlying investment exposures in order to make it clear what risks clients are exposed to: it remains a useful discussion to have before contemplating any investment changes, above all considering the concentration in a small number of companies that certain stock indices have (these points are well-made by Claude above).
Finally, should I just forget about AI in my day-to-day work?
That seems foolish, rather like the accountant I remember stories of from my youth who forbade the use of calculators in his practice because he was convinced that his employees’ brains would atrophy as a result. AI is enormously helpful in analysis and presentation, in making calculations and especially in investigating and flagging potential errors. Yet it is imperitive to understand any AI output before adding my own evaluation and conclusions, and the exacting task of finding the correct investment structures and navigating the potentially difficult topics of estate planning and tax efficiency seem, at least for the moment, to be beyond what AI can competently deal with. So, welcome to the era of the AI-enabled adviser. Believe me when I say that I am highly motivated to be one, because otherwise I may find myself facing that most uncomfortable of questions: what exactly do you need me for?
Why you should change adviser when you move to Italy.
By Gareth Horsfall
This article is published on: 11th September 2026
11.09.26
More and more UK clients are choosing to live, work or retire overseas. Italy has always been and continues to be a popular destination, and is attracting not just retirees but internationally mobile professionals, entrepreneurs and families.
If you have been working with a UK financial adviser, this could present a big challenge. You may have valued and trusted their advice for many years, but becoming resident in Italy can fundamentally change your financial planning requirements.
A different tax system, regulatory framework, pension rules and investment restrictions apply in Italy. Arrangements that might have been suitable for you when you when you were in the UK will need to be reassessed, once you move to Italy. The tax treatment of your pensions and investments will change, while local reporting requirements, succession laws and inheritance tax rules will introduce further complexity.
Without appropriate planning, you can face unexpected tax liabilities, unsuitable financial arrangements or difficulties accessing ongoing advice. Your adviser should have local financial and tax knowledge and consider your life in the future.
The importance of local knowledge
Planning across borders requires more than just a general understanding of international finance. It requires knowledge of the rules for residents of Italy and your country of origin.
The treatment of UK pensions, investment accounts, insurance-based arrangements and other assets differs considerably between the UK and Italy. A product that is tax-efficient in the UK, such as an ISA, does not receive the same tax treatment in Italy. You may also find that certain investment funds or financial institutions are unable or unwilling to retain you as a client when you change your residency to Italy.
Regulatory permissions are equally important. A UK adviser will no longer hold the permissions required to provide regulated advice once you become resident in Italy. Even if they promise continuing service by offering ‘management but not advice’, (which is not a viable solution) without local knowledge or access to appropriate solutions they can be inadvertently creating more problems for you in the future.
Advisers naturally want to protect your longstanding relationship, but they must also recognise the limits of their permissions and expertise. All advisers should operate in your best interests. Finding a regulated adviser in Italy and working on a plan with your UK adviser, together, to transition you over is the best solution.
A UK adviser should feel comfortable that they can introduce you to a company like The Spectrum IFA Group whom they can work collaboratively with. You gain access to relevant international and local expertise, while your relationship with your UK adviser is recognised and respected.
Your financial life does not stop at the UK border, but the rules governing your pensions, investments, taxation and estate planning can change considerably when you move overseas.
A UK based adviser may have spent many years earning your trust, and the relationship should not be placed at risk simply because you relocate.
As an adviser and the manager of The Spectrum IFA Group, I have over 20 years of relevant international and local Italian financial planning knowledge and created a list of trusted professionals that I can refer you to.
Planning before your move
The most effective time to consider the financial implications of your relocation to Italy is before you change residence.
Decisions made in the months leading up to a move can have a lasting effect on how your income, investments, pensions and estate are treated.
Early engagement gives us time to plan and utilise any tax benefits in your home country, any tax and time planning opportunities in the year of your move and then any possible Italian tax incentives after your move.
Addressing these matters if you have already become resident in Italy becomes harder or more expensive to resolve, but not impossible.
Supporting you in your move
Cross-border planning is rarely a one-off exercise. Your circumstances will evolve as you move to Italy, develop businesses, sell assets, receive inheritances or approach retirement.
You may decide to remain in Italy long-term, or decide to move back to the UK, or divide your time between different countries. Your financial arrangements must therefore remain flexible enough to respond to further changes in residence, regulation and personal objectives.
Regular reviews are essential. This allows us to consider whether arrangements remain appropriate, whether legislative developments have altered your position and whether your longer-term goals have changed.
The Italian flat tax regime for HNW and the UK pension opportunity
By Gareth Horsfall
This article is published on: 7th September 2026
07.09.26
By now, the Italian flat tax regime for High Net Worth individuals has been running since 2017 but has probably seen more of an uptake in recent years. It has become more interesting for many HNW individuals to establish residency in Italy, even if you have business interests elsewhere and also when the flat tax rate has increased from €100000 in 2017 to €200,000 and from the 1st Jan 2026 increased to €300,000.
It is commonly thought that once accepted onto this tax regime that there is little financial planning to be done and you can largely leave your financial affairs untouched. This might well be the case, but it leaves a hugely unexplored financial planning opportunity by most advisers and accountants alike – liberation from UK pensions.
In the case of a UK pension (or most other country pensions), if you remain a resident in Italy after the end of the 15 years period, and you are over the age at which you can access your UK pension then any lump sums and / or income drawdowns from this pension will likely be subject to your progressive marginal income tax rates.
A lot depends on where you might be resident at the time of taking your retirement scheme benefits, but in most European countries, for example, the income from your UK pension will be taxed in Italy at the following rates: 23% rising to 35% and 43%)
On the other hand, if you were to generate income from a portfolio of assets or a highly tax efficient Investment Bond, you would only be charged capital gains and / or non-earned income tax (26% flat rate in Italy) on the assets and not on the whole income drawdown.
Therefore, if it were possible to convert your UK pension pot into a standard investment portfolio you could potentially free yourself of future income tax liabilities.
The good news is that it is possible with careful planning. Firstly, you would need to consider your future residency arrangements when taking benefits from the pension pot and assuming you are already above the UK pension access age (55 or 57 from 6th April 2028), then you could encash your UK pension and invest the proceeds in an investment portfolio, and in the process have created a much more tax efficient future income stream for yourself.
If you are on the HNW flat tax regime, you have established residency outside the UK and therefore under the double taxation treaty between the UK and Italy you only need to pay tax on UK pension income in your country of residence.
However, any encashment should be exercised with caution.
As a result of establishing residency outside the UK, the UK government will automatically apply a progressive emergency tax code to your encashment (20%, 40% and 45%) and assuming the UK pension pot is of sizeable value then this could mean an equally sizeable HMRC tax bill.
But, because you can prove residency outside the UK, you are covered by the UK /Italy double taxation treaty, and any tax will be refunded by HMRC on request of an NT (non-taxable) code.
However, there is a way to avoid paying tax to HMRC altogether, with a little careful planning.
If you think that might be of interest to you, please feel free to get in touch on
gareth.horsfall@spectrum-ifa.com or message me on +39 333 649 2356
Finance event Italy September 2026
By Gareth Horsfall
This article is published on: 2nd September 2026
02.09.26
FINANCIAL TALK, TAX PLANNING AND RAPHAEL IN UMBRIA – 24TH SEPTEMBER 2026
BOOK YOUR PLACE ON THE INVESTMENT, FINANCIAL PLANNING AND RAPHAEL IN UMBRIA TALK ON THE 24TH SEPTEMBER IN THE HEART OF THE NICCONE VALLEY.
If you haven’t registered, I would like to extend the invite to the event I will be hosting in the Niccone valley, Umbria on the 24th September.
On the 24th September in the gardens of the amazing Casa Nova, https://casanovaumbria.eu/, Niccone Valley, near Umbertide, I will be hosting an investment talk presented by Christopher Saunders from New Horizon Asset Management (Watch his video here on why we could be living through World War 3…) followed by some Italian financial and tax planning talk, and Q&A, from myself and to finish a wonderful talk from Dr Tom Henry on the life of Raphael in Umbria. All this within the stunning Niccole valley backdrop.
The future of financial markets, AI, continuing wars and financial and tax planning your life in Italy
By Gareth Horsfall
This article is published on: 22nd August 2026
22.08.26
FINANCE – ART – GARDENS
A TALK IN THE NICCONE VALLEY, UMBERTIDE
24th September 2026
10.30am to 14pm.
Morning beverages and lunch included.
During my time spent trying to keep cool, my mind turned once again to upcoming events this year. Conversations with clients are almost always lurching around all the current potetial threats – from AI, continuing wars, the US midterms and a future which seems more uncertain than ever. I can almost feel everyone’s anxiety, and so I thought, let’s talk about them in person and try and put our minds at ease, before the winter period sets in.
So, I decided to set up an in-person talk like no other.
A talk on the future of financial markets, AI, continuing wars and financial and tax planning your life in Italy
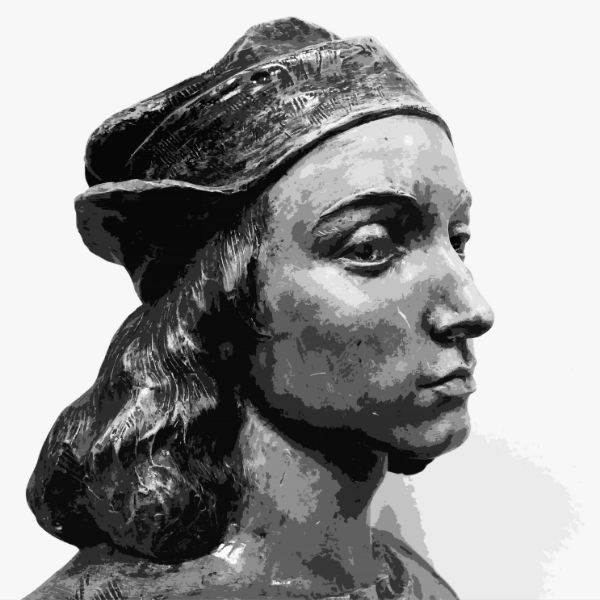
All this mixed with a more ‘soothing’ art history talk on the renaissance artist Raphael and his life in Umbria, presented by Dr Tom Henry – Emeritus Professor of Art History at the University of Kent on the artist Raphael in Umbria.
All this, in a stunning hillside location, Casa Nova (www.casanovaumbria.eu) nestled in the Niccone Valley, Umbria.
First up with be a financial markets talk with Chris Saunders of New Horizon Asset Management
AI, War & Markets: Investing in a Divided World
You can watch a very interesting 2 minute video by clicking on the link below👇, of Chris explaining why we are very likely living through World War 3. Not a world war as we know it historically, but one which may be taking place right before our eyes.
**WHY WE COULD BE LIVING THROUGH WORLD WAR 3**
New Horizon Co-Founder Chris, will discuss:
- The global AI race and the opportunities it may create
- Why volatility is likely to remain a feature of investing
- Where the winners and losers may emerge
We celebrate 15 years of The Spectrum IFA Group in Italy in 2026.
In my time since I set up the branch in Italy, I have learned a few Italian financial planning tips and tricks along the way.
I will make a short talk and then throw questions over to you in a Q&A.
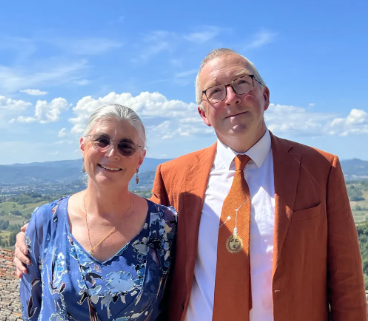
Dr Tom Henry and his wife, Patricia Robertson
And finally, to eradicate any anxieties about the future, there will the talk by Dr Tom Henry – Emeritus Professor of Art History at the University of Kent on the artist Raphael in Umbria.
Formerly Professor of History of Art at the University of Kent and now Emeritus Professor; Lecturer in Art History at John Cabot University. Cavaliere dell’Ordine della Stella d’Italia. He was Director of the University of Kent’s School of Classical and Renaissance Studies in Rome, and is a curator and expert on Raphael, Signorelli and Central Italian painting, with extensive experience of working in Italy. He speaks regularly at conferences in Italy (including at Villa I Tatti and British Institute, Florence; Accademia di San Luca, Rome; Bibliotheca Hertziana, Rome; Villa Wolkonsky, Rome; Museo di Capodimonte, Napoli; and in the Vatican Museums) as well as abroad (Albertina, Vienna; Courtauld Institute of Art, London; Cleveland Museum of Art; National Museum of Western Art, Tokyo; Musée du Louvre, Paris; Metropolitan Museum of Art, New York; National Gallery of Art, Washington).
And you get to see all this in the amazing country hillside garden setting in the Niccone valley, curated by Trish, Tom’s wife, a passionate gardener and lover of nature, and who also cultivates and sells irises.
Trish will also be avaialble for any gardening questions you might have!
Due to the nature of the event, I only have space for a maximum of 30 participants, so if you are interested in attending and blocking your place then please let me know as soon as possible.
Please contact my assistant, Silvia Loi on silvia.loi@spectrum-ifa.com and book your place.
Let’s get out and get some fresh autumnal air after a seemingly endless hot summer!
Financial update Italy May 2026
By Gareth Horsfall
This article is published on: 27th May 2026
27.05.26
OIL AND INFLATION, UK INHERITANCE TAX PLANNING AND THE 7% TAX REGIME
My son turned 16 this year, and I guess it’s normal, especially in today’s world of instant gratification and media, that young adults would be curious about global political events.
It is therefore no surprise that he has been asking about the Iran/US war, how it started, and what the reason behind it is. Clearly, it is not easy to give a simple and quick answer to these sorts of questions, but often I simply answer, “follow the money.” If you follow the money trail, it will very likely lead to the main real reason why.
In the 2022 Ukraine/Russia conflict, we can see that the territory which has now been claimed by Russia in the eastern part of Ukraine, apart from being ethnically Russian, is also the most resource-rich part of Ukraine, holding the majority of Ukraine’s $15 trillion mineral wealth. The region accounts for roughly 80% of conventional oil, gas, and coal reserves, as well as critical minerals essential for defence and green technologies. The Dnieper-Donetsk Basin and the Donbas (Donets Basin) are the most resource-important parts of the country.
The east contains the overwhelming majority of Ukraine’s coal, natural gas, and conventional oil reserves. The region is also home to major deposits of iron ore, titanium, uranium, and lithium — materials that are highly prized for their use in aerospace, electronics, and electric vehicle battery industries. It’s no wonder that the war trudges on!
Follow the money!
It is therefore no surprise that the recent Trump visit to China ended with reports (albeit from Trump himself — no word from China yet!) that China will now be buying more oil from the USA and less from the Middle East.
Is this a sign that China is not happy with recent events in the Gulf and has decided that its economic links and export-led economy are more tied to the US consumer than they would like to admit, and therefore they want to secure energy resources from them as well? Or merely a case that they are left with no choice?
Either way, the decision makes a lot of sense given that China is the largest consumer of oil in the world, and the US is the largest producer. In fact, the USA is, by a long way, the biggest oil producer in the world, pumping 13.58 million barrels of crude a day. Its nearest competitor is Russia on 9.87 million barrels of crude per day, closely followed by Saudi Arabia on 9.51 million barrels of crude a day. The three together account for 40% of the world’s supply! (The USA also now controls the Venezuelan energy infrastructure!)
So, energy reliance on the Straits of Hormuz is likely to decline in coming years given the chokehold that Iran has on the area. 20% of the world’s oil passed through the Straits of Hormuz prior to this war, and Europe was the most susceptible to Middle Eastern oil disruption. Trump is going to open up drilling in Alaska and, as more oil is pumped out of that region, then it’s likely that China and the rest of Asia will start buying more from Alaska as it comes online.
Global politics is redrawing economic borders again and redefining alliances!
Just like I say to my son…..follow the money!
So, does this create a potential investment opportunity? It certainly does! Mining and oil exploration are starting to look attractive once again.
Our asset manager partners are keeping a close eye on the opportunities as they arise.
I know for the green investors amongst you this is the worst possible news, but the economic “West” can only protect its future development into a world of AI, robotics, and tech with access to primary resources which are not in what is considered economic or geopolitical hotspots.
Inflation
I won’t blather on about this, but just to say:
- Diesel up 19% to 26% in Italy since the start of the Middle East crisis (depending on region)
- Benzina up 17% to 47% since the start of the Middle East crisis (depending on region)
- Fertiliser is up between 51% and 80% (this could have a further knock-on effect on food prices — we may not have seen the worst yet)
- Melanzane up 21.5%, peas 19.6%, zucchini 11.1%, lemons 10.8%, strawberries 10.8%, eggs 8.5%, red meat 8.4%, wood fuel and pellets up 8.2%
- I don’t even know the information on building materials, but am very glad we moved into our house and did the work in 2024 and not now. That being said, the cost of materials had already risen significantly since Covid in 2020.
In the meantime, a typical GBP multi-asset portfolio in a balanced risk profile returned around 17% p.a. over the last year to date, 31.49% over the last 3 years to date, and around 33% over the last 5 years. Average annual return over the last 5 years: 7.7%.
A typical EUR multi-asset portfolio in a balanced risk profile returned around 15% p.a. over the last year to date, 32% over the last 3 years to date, and around 31% over the last 5 years. Average annual return over the last 5 years: 5.27%.
The McKinsey Global Institute frequently discusses how similar cycles of pessimism and economic hardship impact consecutive decades and generations, meaning that every adult generation is likely to live through the same economic periods as the one before them at least once in their life, if not more.
I turned 18 (supposedly an adult!) in 1992. Prices hardly rose in real terms from 1992 until 2020. Then Covid, then Ukraine/Russia, and now the Middle East conflict. It’s now my turn to live through an inflationary period.
Prices rarely come back to where they were before!
In 1973, an oil embargo lasted 6 months. Crude went up 400%. It never came back to where it started from.
1979 — The Iranian Revolution — prices doubled again.
The world rearranges first and then prices move second
Prices may fall back a little when the conflict settles, but are unlikely to settle back to previous levels. Given my eye-wateringly high gas heating bill over the last winter, I am not looking forward to next winter! But I still have the summer to try and avoid overheating!
Investing is the only way to protect your hard-earned capital. Do not sit in cash long term. Keep the things under your control under review — costs and your risk profile — and let the markets do the rest.
Inflation in Italy since 2020 sits officially at 18%, but the reality is that it is more likely 30–45% depending on location.
Between 5% and 7.5% per annum.
At a sustained 7.18% inflation rate, your money will halve in value in 10 years…
…this has the same effect as your healthcare costs, care homes, schools, trips for the kids and grandkids, flights, food, eating out, etc. doubling in value.
Making your money work harder for you is so important in periods like the one we are currently going through. Protecting your future is key.
UK Inheritance Tax Planning
At the moment I am working with a lot of clients to plan their UK Inheritance Tax liabilities and how to avoid them under the new UK Statutory Residence Test system.
Given the change to UK Inheritance Tax for non-UK residents, which will come into force in April 2027, it makes perfect sense for anyone who has already been away from the UK for more than 10 years, or anyone thinking of doing so, to take a good look at their financial affairs and see how they might be able to avoid UK inheritance tax, and in some cases avoid it altogether.
From next year, the rules will change from a domicile basis to a residence basis. Domicile was always a difficult link to break with the UK, regardless of where you were living in the world, and the UK always had the right to tax your worldwide estate if they deemed that you had sufficient ties to the UK at the time of your death.
Now, given the Statutory Residence Test rules, if you can show that you have been a non-UK resident for 10 out of the last 20 years, then your non-UK situs assets will not fall under UK inheritance tax law. UK situs assets will, however, still be subject to UK inheritance tax. When it comes to gifting assets to your spouse, then there are some new things to consider:
The financial planning opportunities and pitfalls:
When both spouses have been outside the UK for more than 10 of the last 20 years and are considered non-UK long-term residents
You can no longer transfer an unlimited amount of UK situs assets between spouses. In this case, you can only transfer £325,000 on top of the nil-rate band, therefore a maximum of £650,000 before UK IHT at 40% is applied. If you have assets in the UK over £650,000 and qualify under the non-UK long-term resident rules, then the logical conclusion is that you look to move your assets outside the UK as soon as possible as part of your UK IHT planning exercise.
One of you is a UK long-term resident (has not yet qualified with 10 years’ continuous non-UK residency) and the other is a non-UK long-term resident
In this case, the logical conclusion is that, once again, you look to move your UK situs assets outside the UK, but by gifting them to your non-UK resident spouse. Your spouse would be subject to the same rule as above, i.e. a limit on the transferable amount at a £325,000 tax-free allowance plus a £325,000 additional non-UK long-term resident allowance, therefore £650,000 total. Anything over £650,000 would be subject to the UK’s potentially exempt transfer rules, i.e. if you live 7 years after the gift, then it is fully transferred and no longer in your estate for the purposes of inheritance tax in the UK. The obvious advantage of this approach is that your spouse is no longer subject to UK IHT and, if considered for IHT in Italy, then with some careful planning may be able to even reduce that to zero in Italy.
The alternative, depending on your own circumstances, is to keep the assets in your own name and move them outside the UK, taking the view that once your 10 years’ continuous non-UK residency has passed, then they no longer fall within your UK estate for IHT purposes.
Private pension funds
Unused private pension funds will be brought into the IHT net in the UK from April 6th, 2027. This is bad news for anyone with a sizeable pension pot in the UK. At the same time, the UK has imposed an Overseas Tax Charge on moving your pension outside the UK. In the past I have moved clients’ pension funds into a QROPS (Qualified Recognised Overseas Pension Scheme), and for European purposes those schemes were always located in Malta due to the compatible financial system there. Now, a transfer of this type for an Italian resident would incur a 25% overseas one-off tax charge.
Having stated this, given the prospect of paying a 25% overseas tax charge for moving your pension outside the UK versus 40% IHT on the fund in the UK, the former might be the better option. I am currently planning this action with some clients. This only makes sense where you have qualified as a non-UK long-term resident for IHT purposes.
A simple comparison between UK and Italian IHT
It is well known that Italy is a fiscal paradise from an inheritance tax point of view. They prefer to tax during life, but are very light on inheritance tax.
Whereas the UK will typically tax 40% on anything over £325,000 — the nil-rate allowance (plus an extra £325,000 for a spouse and a further £150,000 for primary house relief), Italy by comparison charges a mere 4% where the transfer is made between spouses and/or children, but the spouse and children each get a €1 million allowance (franchigia) before the 4% applies. In addition, the house price is based on the cadastral value (and not the market value) and so is much lower. Not only that, but if you structure assets correctly using an insurance portfolio wrapper, you can actually place any amount in the product and it does not enter into your estate for the purposes of making the estate value calculation.
For a family of 2 children and 1 spouse, you would pay just 4% on an estate over €3 million in value, plus the availability of any sum in an insurance portfolio wrapper without inheritance tax applied. Clearly, with some sensible planning, it is possible to reduce your estate dues to near zero in Italy.
Getting the right last will and testament in place
This all sounds very attractive, but what about the forced succession laws in Italy? If you are no longer subject to UK law, then how can you plan to leave your estate to your chosen beneficiaries?
Well, if you are an Italian citizen, then you probably don’t have a choice, but would be best speaking to a lawyer to determine if this is the case. But if you haven’t taken citizenship, then European law may allow you to nominate your home jurisdiction’s administrative law to distribute your assets to your chosen beneficiaries.
So, once again, with some careful planning you can probably even avoid Italian forced heirship rules. This is the realm of a good lawyer, and you would need to have a correctly worded will. Always take legal advice when considering your will planning options.
The 7% Tax – ‘Regime Pensionati’
I wrote an interesting blog post on planning around the 7% pensionati tax regime in Italy. It was put into place in 2019 to challenge the Portuguese non-resident tax regime and has had limited take-up to date, but has become more interesting since April due to a change in the rules.
If you are interested in learning more about it, and more importantly the financial planning tricks, then you can read my post HERE.
Stay in cash or invest?
By Gareth Horsfall
This article is published on: 19th May 2026
19.05.26
I could give song and verse about why it is a good time to sit in cash based on high valuations in equity markets or Bond prices being low, but my job is about long term financial and tax planning for people who are living in Italy. Therefore, 99% of the time the answer to the question will always be to invest and not sit in cash.
That might sound like a simple and quick reply to the question, but there is really only one instance when we would advise someone living in Italy to stay in cash for any period.
Why should I keep my money in cash?
For anyone who needs cash in the short term — for a renovation of their Italian home, an Italian property purchase, or a major life event, money to support income needs or care costs etc — keeping money in cash is sensible, regardless of interest rates or market returns. Cash is stability, and stability has a value when we have expenses or liabilities, which can be quantified both monetarily and the term over which they need to be paid.
However, for all other long‑term goals — retirement income, future healthcare needs, supporting children or grandchildren — cash is a terrible solution. Over long periods, inflation erodes purchasing power far faster than cash can grow and if you are planning for life in Italy it is no different to anywhere else.
Even when interest rates appear attractive (and sometimes cash rates are better than that offered by the markets, but for very brief periods) they rarely keep pace with rising prices over a decade or more. Markets fluctuate, but over time, they have consistently outperformed cash.
Cash returns often fail to keep up with inflation!
The same principle applies today that we have always applied for our clients. Cash has a role, especially for short term needs.
But for long term goals, investing remains the most reliable way to preserve and grow purchasing power.
Inflation never disappears — and cash alone cannot protect you from its long term effects.
Italian life can be much cheaper, in many ways (food, access to services [beaches, countryside, cultural venues], eating out at restaurants etc) than life in other countries, but it still does not negate the need to invest for your long-term future rather than leaving your money sat in cash.
(At time of writing you can expect to get back, on average, a 2% return from your cash in EU based deposit accounts. If you lock in for any specific term, you may be able to get some higher rates but then you lose the liquidity of your funds)
How are UK pensions taxed in Italy?
By Gareth Horsfall
This article is published on: 8th May 2026
08.05.26
Because pension systems across Europe – and beyond – follow different tax models, understanding how Italy interprets them is essential for anyone planning their long‑term financial life here.
EET, ETT, or TTE?
Across the world, private pension systems follow a handful of tax models. The three most common are known as EET, ETT and TTE. These refer to how contributions, investment growth and withdrawals are taxed. Many countries, including the UK, use the EET model, where contributions and investment growth are tax incentivised and withdrawals are taxed at standard progressive income tax rates.
Italy, however, uses the ETT model, where contributions into a personal pension ( previdenza complementare) can be eligible for a tax deduction (up to a certain limit), the fund itself is taxed but at the time of the payment of the income a lower income tax rate is applied.
(Only a few countries use the TTE model, where contributions and growth are taxed but withdrawals are exempt).
These differences matter because when someone moves to Italy with a UK pension from the the Italian tax authorities will classify it according to Italian tax law interpretation. Often, a commercialista is left with the decision of ‘using best logic and guidance from the Agenzia delle Entrate. This is where mismatches can arise: a pension designed under one model does not always fit neatly into another.
The EET model (UK)
The EET model is widely used and easy to understand. It allows individuals to save efficiently during their working life and then pay income tax on withdrawals in retirement. Many people from the UK arrive in Italy with personal pensions/SIPP’s/occupational defined contribution pension schemes etc, and the question becomes how Italy should treat them for taxation purposes?
Since Italy taxes its own pension funds during the accumulation phase, it would not make sense for a foreign pension to benefit from tax‑free growth abroad and then also receive Italy’s preferential tax rate on withdrawals. That would amount to a double taxation benefit, which the Italian system is not likely to provide.
The ETT model
Italy’s own system provides for a 100% tax deduction for contributions to a ‘previdenza complementare’ up to a limit of €5300pa (as at 1 Jan 2026) but then taxes the fund during the accumulation phase. Italy also taxes withdrawals, although at a reduced rate for long‑term contributors of between 15 and 9% depending on the length of time contributions has been made.
Despite this, private pension participation in Italy remains low compared to the EU average. Limited tax incentives, restricted investment options and relatively high charges have made private pensions less attractive than other forms of long‑term saving. Many Italians prefer property or alternative investments, and the system has never fully encouraged widespread private pension participation.
So what does this mean for the taxation of your UK pension in Italy?
Given the UK incentivises pension accumulation with tax breaks, then Italy is unlikely to apply its own reduced tax rate on withdrawals, as stated above.
Guidance issued by the Agenzia delle Entrate issued on SIPP’s (found here) seems to confirm the tax treatment as detailed above, indicating that pensions built under the EET model should be taxed as ordinary income when paid out to an Italian resident.
Ultimately, the interpretation rests with the professional preparing your tax return, but with the ruling on this specific case in 2024, we can be assured that treating UK personal and occupational defined contribution pension income as taxable under standard Italian progressive income tax rates is the correct tax treatment in Italy. Choosing a different approach may be possible, but it carries the risk of future reassessment by the Agenzia delle Entrate and possible back fines and penalties.
Qualifying Recognised Overseas Pension Scheme
For those planning to live outside the UK permanently, transferring a UK pension into a QROPS has been an option for many years. These schemes operate under EU‑aligned rules and are designed for individuals who no longer intend to reside in the UK.
The UK has now introduced (from 2025) an overseas transfer charge of 25% on transfers to QROP’s where the pension holder resides in a different state to the place where the QROP’s is registered. Malta was used, prior to this ruling, as a way for EU residents to transfer their UK pensions away from the UK due to Malta’s status as an EU member state and it’s double taxation treaties with all other EU member states. (Italy does not have any QROP’s vehicles to which UK pensions can be transferred) However, given the 25% overseas transfer charge this is not a suitable option for most people.
If there is an overseas tax charge on a transfer to a QROP’s, what can I do instead?
Since Brexit, UK pension providers and UK asset managers should no longer manage monies for non-UK resident individuals due to a loss of licensing and regulatory authority. Therefore, you may find yourself in a position where
a) you are being refused any investment and /or pension advice
b) asked to transfer your pension to another pension provider who can work with you as an Italian resident
c) and/ or take the pension in one lump sum but NOT in income drawdown
Clearly all the options are unsatisfactory and c) itself could generate a big tax liability in Italy if you have a large lump sum, which becomes taxable in one year.
Bear in mind that the 25% tax free lump sum in the UK, would be taxable in Italy as income tax ! As a smart financial planning tip, it is always best to withdraw this sum before becoming a resident in Italy, if possible.
Therefore, the best advice is to transfer to a UK SIPP which can work with EU residents and will allow you the flexibility that a standard UK domestic SIPP would provide. You can get access to a wide range of asset managers and low cost model portfolio solutions. We work with such companies and regularly transfer pensions as a financial planning strategy to ensure you get access to the right advice in Italy based on your other incomes / assets.