
I wanted to communicate some information regarding what is going on in the Middle East with some information from Evelyn Partners ( one of our asset management partners) in an email newsletter to all advisers, which provides perspective regarding investments. If you have any questions or thoughts, do not hesitate to get in touch and fingers crossed this situation does not last long!
Viewing posts categorised under: Italy
Crude awakening in the Middle East
By Gareth Horsfall
This article is published on: 4th March 2026
04.03.26
Crude awakening in the Middle East
Escalating tensions in the Middle East have brought renewed market volatility and lifted oil prices, but diversified portfolios offer resilience in periods of uncertainty
What has happened?
Over the weekend, tensions between the US, Israel and Iran escalated materially. Israeli strikes have reportedly targeted Iranian nuclear facilities, while the US has signaled a broader objective that may extend beyond deterrence towards regime change. Iran has responded with attacks affecting parts of the Gulf region, including strikes impacting areas in the UAE, Qatar, Bahrain and Kuwait, as well as Israel.
This marks a significant shift from prior contained flare-ups. Financial markets are responding to the risk of further escalation.
Initial market reaction
Three key price moves frame the immediate response:
- Brent crude oil is up roughly 10%, to around $80 per barrel.
- S&P 500 futures are modestly down approximately 1.5%.
- Gold is up around 2.5%, reflecting demand for traditional safe havens.
The move in oil is central.
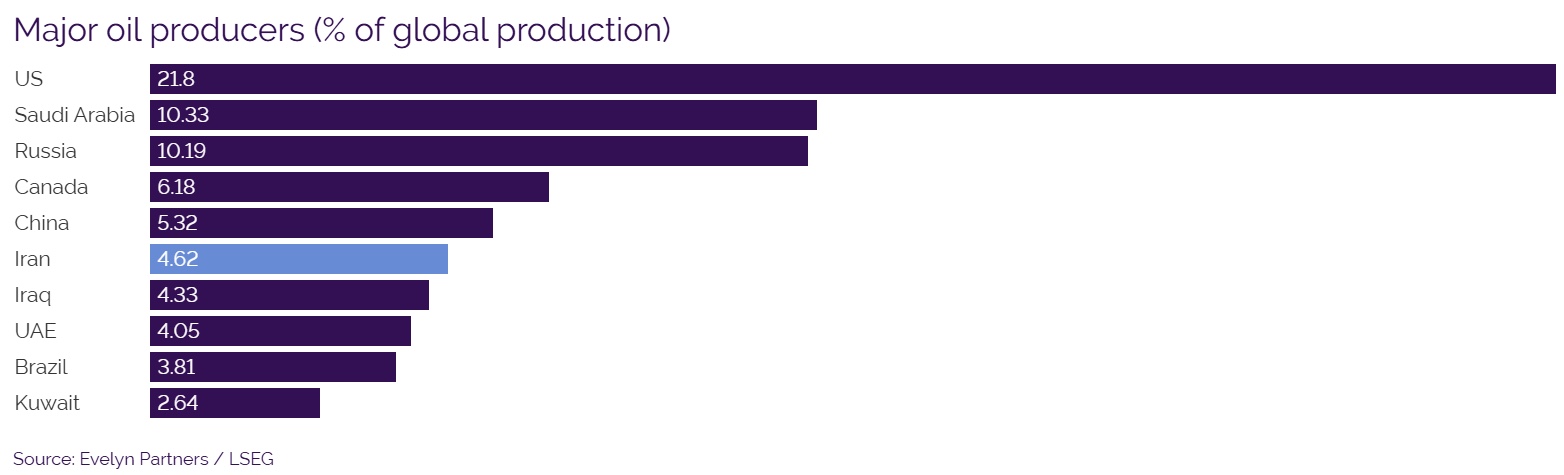
Iran is a major exporter, and critically, more than 80% of Iranian oil exports go to China. Iran is also strategically important to China’s Belt and Road initiative, is a member of BRICS, and plays a role in facilitating trade outside Western sanction frameworks.
In that context, this is not just a regional issue; it intersects with broader US – China strategic dynamics. Should the US gain greater leverage over oil flows coming out of both Iran and Venezuela, it would provide Washington with a significant bargaining chip ahead of the upcoming summit between Presidents Trump and Xi of China.
Paradoxically, such leverage could also deter China from blockading or invading Taiwan, a far larger systemic risk to global markets given Taiwan’s dominance in producing advanced semiconductors.
Key risks to watch
The primary “tail risk” remains disruption to the Strait of Hormuz, through which roughly a fifth of global oil supply passes. At present, while there are signs of disruption – including higher shipping insurance costs and some tanker hesitancy – the Strait remains open and traffic continues. A full closure or mining of the waterway would represent a far more severe shock to energy markets and global growth.
There is also the risk of broader attacks on regional energy infrastructure or US-linked assets across the Gulf, as most of the key oil infrastructure sits within short-range missile range of Iran. However, at this stage, markets are pricing heightened uncertainty rather than a sustained supply shock.
It is also worth noting that global oil inventories have been rising, which provides a partial buffer against near-term supply disruption. That does not eliminate risk, but it may dampen the impact unless escalation becomes materially worse.
Equities have softened modestly, but earnings growth remains the dominant driver of equity markets. Corporate Earnings Per Share momentum has so far offset geopolitical and tariff concerns this year, and we are not seeing signs of systemic stress or disorderly market functioning.
Portfolio implications
Periods like this are uncomfortable, but they are not unfamiliar. We have seen similar episodes – most recently during prior Israel–Iran tensions and in the 2022 energy shock.
History shows that while oil and gold often react sharply, diversified portfolios tend to prove resilient.
Across asset classes, we are seeing natural offsets:
- Energy prices rise, supporting oil and gas equities.
- Gold acts as a multi-use hedge during geopolitical stress.
- Inflation-linked bonds, such as TIPS, provide protection should higher crude feed into inflation expectations.
Within equities, exposure to energy producers can help offset broader market weakness linked to rising oil prices. In fixed income, inflation-linked bonds could benefit from rising inflation expectations. Alternatives such as gold continue to demonstrate their value during energy shocks, as seen in previous episodes including 2022.
Investment strategies are designed with periods like this in mind. They are constructed to withstand geopolitical shocks, inflation pressures and bouts of market volatility, while remaining fully liquid and aligned with clients’ long-term objectives and risk profiles.
Looking ahead
We expect markets to remain volatile in the days ahead. News flow may be intense and, at times, sensational. It is important to distinguish between media tone and market fundamentals.
At this stage, this is not a systemic market event. We are not seeing disorderly trading conditions or liquidity stress.Remain vigilant and ready to adjust portfolio positioning should fundamentals materially change.
For now, the appropriate stance is calm, disciplined and long term. Periods of geopolitical tension are unsettling, but diversified portfolios are designed to navigate precisely these environments. We will continue to monitor developments closely and keep clients informed with measured, evidence-based updates as the week progresses.
I know these are not easy time and so if you have any questions, or would just like to send me some comments then feel free to do so. I am always interested to hear your thoughts on these matters.
Financial updates – February 2026 – Italy
By Gareth Horsfall
This article is published on: 20th February 2026
20.02.26
In this Ezine I will summarise the discussions and news from our annual event which took place in Monaco this year.
As you may know my newsletters are not AI generated and for this reason they take me a little time to summarise the information, and also find the time to do so. I hope that you appreciate the fact that you are not being sent existing information which has been trawled out of the internet-o-sphere, but rather real, new and original content. (AI was a big story on the conference actually, so I will be touching on this a bit further down.
Interest rate cuts – Tax cuts – Lower energy costs – Deregulation
One interesting thing that occurred before I went on the conference, in fact just a few days before, was that a handful of people contacted me to say that they wanted to sell out of US based assets because they didn’t like the activities of Donald Trump and the current US administration. My advice at this time was:
We need to separate the political from the investment!
It is always good to be reminded that the US stock market is valued (USD 67-69 trillion) at more than the rest of the worlds stockmarkets cumulatively (USD 55 to 60 trillion). So no matter what we think about the politics in the US at the moment, to exclude ourselves from the US stockmarket would be akin to investment suicide. We can make investment choices based on sustainable and ethical choices (and we offer these services as well for our clients) but some of the best research, technological innovation and new creative thinking comes from the US and so it still retains it’s spot as one of the best, if not THE best places for an investor.
To further explain the importance of the US market, it was explained at the conference, that should just 1% of the total value of the US stockmarket be moved at any one time, it would hardly move the markets in the US at all. That same amount would be the equivalent of the entire German stockmarket (which includes all the big names we know such as Volkswagen, Basf, Siemens, SAP, Mercedes Benz and many more) and would have a tremendous impact on the German stockmarket and in Europe, just to give context on how important the US is for our portfolios.
Saying all this, I appreciate that the Trump administration may still be a little too much to bare for some people, and so here is my summary of what is going on there:
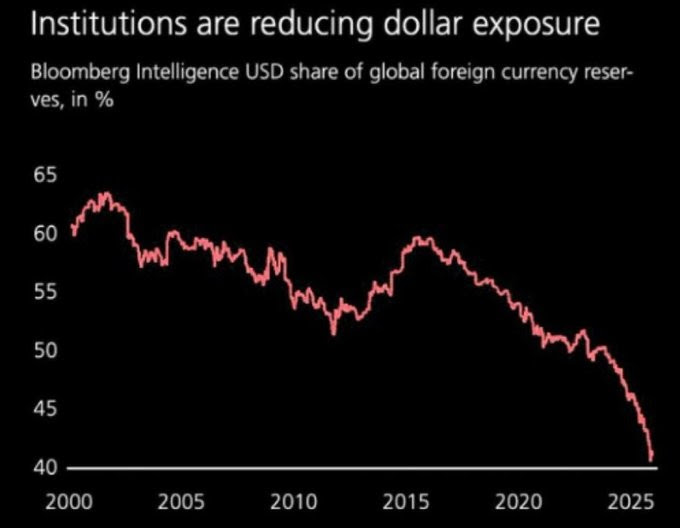
DRIVING THE US DOLLAR LOWER
If the U.S. economy is about 30% of global GDP, then should its currency, being that it is the reserve one, account for 35%-40% of global reserves and not 50% or 60%?
It is now pretty evident that the Trump administration is aiming to push the US Dollar lower against other currencies…but why?
The old globalisation game where the US outsourced everything and let China build the factories is effectively over. The idea that cheap imports were free trade and you don’t pay the price for destroying your industrial base is something which needs to be re-addressed as many economists on both the left and right side of politics, agree. To some extent Beijing also started weaponizing supply chains, particularly in rare earths such as lithium, cobalt and graphite, because they have an almost 90% control over these rare earths, both in mining and refining. The Trump administration is aiming to protect US interests and rebuild American industry from the ground up.
Tariffs are back—and they’re not going anywhere. They have largely turned out to be a negotiating stick and strategically aimed at specific goods rather than blanket punishment, to protect US domestic producers and force companies to bring manufacturing back to the US. As DT has said: “if you want access to the world’s largest consumer market, build in the US” Produce there and employ Americans.
A WEAKER DOLLAR IS PART OF THE PLAN
Not a collapse, but more than likely a deliberate, controlled depreciation to make U.S. exports competitive again and make imports more expensive. (2026 may see a further USD decline when the new Fed Chairman Kevin Walsh is put in place, and then it could stabilize)
Cheap foreign goods have flooded the US market (and Europe) for decades because the dollar was probably too strong. A weaker dollar rewards domestic production, boosts manufacturing margins, and will hopefully brings jobs back to places that have been forgotten for years! (If this strategy works then you can be assured that Europe wil adopt the same approach, no matter how much they hate to admit it!)
PROJECT VAULT
This could be one of the most significant decisions made by any US administration for decades. Project Vault is a $12 billion strategic plan to stockpile critical minerals, the equivalent of a Petro Reserve for the AI and defense age. The US is building a preferential trading bloc with price floors, adjustable tariffs, and enforceable rules to crush China’s predatory pricing and market flooding.
The winners will be the ones who control the physical economy—the mines, refineries, smelters and processing plants. Critical minerals and rare earth security.
Without them, nothing modern works. Jet engines. Hypersonic missiles. Wind turbines. Electric motors. Drones. Smartphones. AI data centers. Defense systems. EVs. Nothing.
And here are some examples:
Niobium—an irreplaceable steel strengthener. Adds toughness, corrosion resistance, and high-temperature performance to superalloys
(Brazil controls ~90% of global supply. The U.S. imports 100%. Zero domestic production. One mine in Canada which given the fractious nature of current US / Canada relations, the US considers this a national security nightmare)
Neodymium (Nd) and Praseodymium (Pr)—the magnetic rare earths that power permanent magnets, the strongest magnets ever made.
(Essential for EV traction motors, wind turbine generators, missile guidance, radar, precision-guided munitions, and high-performance robotics)
CHINA CONTROLS CIRCA 90% OF REFINING AND 93% OF MAGNET PRODUCTION AND 60% OF THE REFINED SILVER MARKET.
IF RELATIONS SOUR FURTHER, THEN BEIJING WITH JUST ONE PHONE CALL, COULD PARALYZE WESTERN DEFENSE AND CLEAN ENERGY SUPPLY CHAINS
And so, in a nutshell, that is what the Trump administration would appear to be doing geopolitically. (I won’t mention any US domestic issues that are….well….. questionable).
My hunch is that you will see Europe follow suit. Europe appears to have woken up (c/o D.T) to the fact that it needs to protect itself and can no longer rely on the US Military Industrial Complex. Re-arming Europe seems to be the EU leaders first objective, but if they then see progress with this economically nationalistic kind of behaviour in the US then I would say that they will start to walk a similar path, even though the EU is quite protectionist by nature anyway. It may mean that you need to stock up on TEMU goods now, whilst the prices are still low!
I have probably dedicated more time here to the Trump administration than I had wanted to, but it is clearly on alot of minds and so was worthy of a few lines.
However, on our conference we did discuss other investment matters, which arguably are not quite as important as what is happening in the US administration, but also warrant some time being spent on them.
THE GREENLAND DEBATE
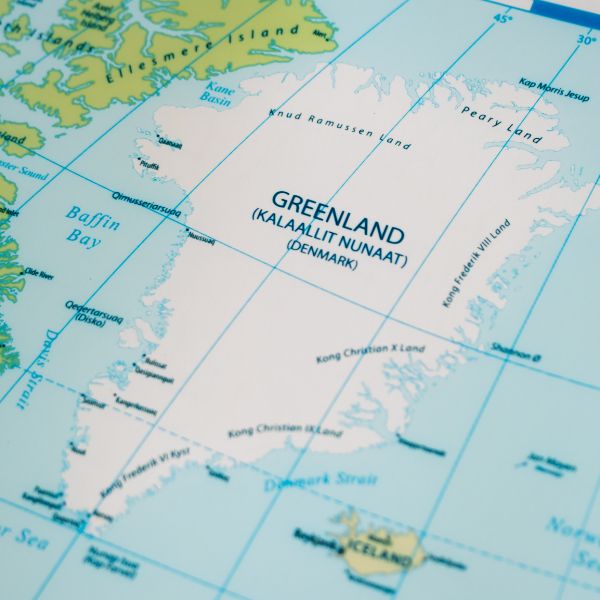
These conferences are always interesting to get perspective on certain matters and the issue of Greenland was brought to light as follows:
From 1951 to 2004 the US had the right to place US bases in Greenland without any permission required.
From 2004 this power was taken away when Greenland gained sovereignty and fell under the supervision of Denmark.
Now, the pre-1951 agreement is being re-negotiated, and although not a ‘free to do what you wish’, the US will certainly have the possibility to expand its military presence. Was the whole ‘buying Greenland fiasco’ just a ruse to restablish this agreement?
THE AI BUBBLE
At the 2025 conference alot was made of AI and how it would be changing the world, putting people out of work and taking over our world. Just one year on and the view from the asset managers was almost completely the opposite, but also that it is not going anywhere soon.
However, an AI bubble (like the tech bubble of 2000), it would not seem to be. AI is already helping businesses to improve productivity but not by firing staff. There is no evidence of this and the companies running AI models themselves, are already profitable. In addition the Big tech companies are cash rich. It is more likely that AI integration will more of a messy technological shift, than a huge damaging effect and it’s very unlikely that AI stocks will be the cause of a global recession, or mass unemployment no matter what you read online.
Net income from Tech + comms services companies has grown from 23.1% in the year 2000 to 35.3% in 2025
HOWEVER, AI IS NOT LIVING UP TO EXPECTATIONS
A term was used: ‘Crap in – Crap out’.
What is being found is that the AI we know: ChatGPT, Google Gemini etc cannot be relied upon for accurate results.
Search results are based on the data that is out in the internet-o sphere. If that data is flawed then it has no way of knowing how to fact check it and hence it will produce inaccurate results. (In fact caught out ChatGPT on 3 occasions, when I knew its results were incorrect. I now use Google Gemini, which appears to be better). There is also a HUGE amount of internet fraud and scam and the culprits are using the internet to deliberately put out content which furthers their devious means. So, how can we rely on such a system? Markets are worried about the inability to overcome this problem and about a lack of innovation in AI. If we are all fishing in the same pool of information and being provided the same results then innovation and creativity grinds to a halt, and that is not good for businesses who are looking to find an competitive edge and / or increase productivity.
THE STRENGTH OF AI
But, AI probably has a more focussed strength in it’s ability to gather, organise and analyse large data sets. Private data is the real gem! It’s what you can’t see rather than already public data. I may have mentioned in my Ezine last year the example of the Lancet medical publication in the UK, which has archives going back 203 years. It is almost unimaginable that human beings would be able to reference a tiny fraction of that information, whereas they are already using AI tools to organise data and information in their business and to make it available to a much wider and much more targeted audience. Data is the new gold! Loyalty card data would be a perfect example of data which can be privately exploited by companies looking to gain a competitive edge with the use of AI tools.
AI POWER
The strange thing with AI is that the people who are probably going to make money from it are not the people directly running AI tools, but more likely the periphery businesses that are needed to keep it running: energy providers and data centres being good examples: see images below to give you an idea of just how many resources are going to have to go into running and maintaining these centres.
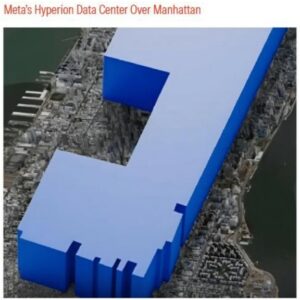
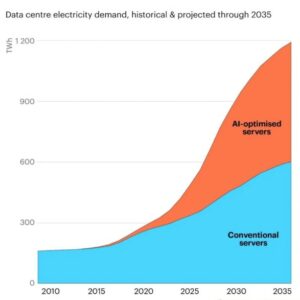
Could nuclear and renewables be the winners long term?
TWO MORE ITEMS
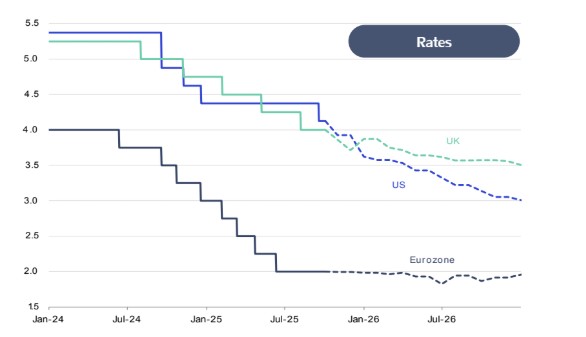
INTEREST RATES: don’t expect rates on your cash to be rising anytime soon. If you are sat with the majority of your assets in cash, then you should really be thinking about the long term implications of inflation on these monies. This is exactly the scenario that governments wanted to see. Low interest rates (which keep government benefit payments down and debt repayments low) but an inflationary economy. They pay their debts down quicker amd erode them away, and we feel the pinch. You can see the interest rate trend in the chart below.
OIL
Given the US’s influence over the world’s major oil producers (Venezuela, Saudia Arabia, Iran and Canada) , it is likely that there will be a glut of oil in the next 5 years. This will most likely push prices down. This is certainly what the D.T administration wants. Energy prices and inflation should fall which could be good for US stocks in particular. The wider US market could benefit greatly.
I hope you have enjoyed this content! Once again apologies for the time taken to get it you. Unfortunately I don’t even think AI is sophisticated enough…yet…to decipher my scribbles and handwriting when note taking.
As always, if you have any questions, or would just like to send me some comments on what you have read here, then feel free to do so. I am always interested to hear your thoughts on these matters.
Equally, if you would like to follow up individually on anything then you can do so on gareth.horsfall@spectrum-ifa.com or message / call me on +39 333 649 2356
Inbound workers tax regime Italy
By Andrew Lawford
This article is published on: 13th February 2026
13.02.26
New rules from 2024
Firstly, if you have already qualified for this regime under an earlier version, this article will not be relevant for you. There are, however, some transitory arrangements for people who became resident under the regime in the 2024 tax year but had purchased a property in Italy by the end of 2023.
If you think this might apply to you, then bring it up with your tax adviser to see which version of the regime applies to you.
What does the benefit consist of?
- A 50% reduction in taxable income for a period of 5 years, starting with the year the individual takes up residency in Italy;
- It is possible to increase this reduction to 60% if the individual has a child under the age of 18 living with them in Italy.
What are the requirements?
- The individual cannot have been a tax resident in Italy within the 3 tax years prior to taking up residency;
- This requirement increases to 6 or 7 years when there is continuity in the employment relationship (e.g. an inter-group transfer) – the 7 year rule applies when the individual was working for an Italian company in Italy before moving abroad;
- Commitment to remain a tax resident of Italy for at least 4 years;
- The work must be performed primarily in Italy;
- Qualification or specialisation requirements must be met (generally speaking you must have a university degree, be specialised by a certain amount of professional experience or be involved in certain types of research).
What are the limitations?
- Maximum income able to benefit from the incentive: €600,000p.a.
- Certain types of income may be subject to exclusion for freelancers, in particular any passive income streams like royalties. The general rule is that the individual must be engaged in “arts and professions”. Sole-trader business income would also be excluded.
What about compulsory pension contributions?
- Based on the prior incentive schemes, INPS contributions would continue to be calculated on 100% of employee income, but in the case of a freelancer, the incentive applies to pension contributions as well;
- The above has yet to be confirmed in practice for the new regime, but it does appear to offer a benefit to the self-employed as opposed to ordinary employees.
To sum up the critical points:
- If you have already been a resident of Italy in the past, make sure you understand the minimum period of residency abroad that applies to you;
- Check if you satisfy the qualification or specialisation requirements;
- As a freelancer, make sure that your particular activity or parts thereof would not be excluded;
- Watch out for clarification of the pension contribution requirements.
If you think this might be of interest to you, don’t hesitate to get in touch. I can’t give you a tax opinion, but I can discuss living in Italy more generally and can help with your overall planning, including getting appropriate professional advice as necessary.
The unusual aspects of taxation in Italy?
By Gareth Horsfall
This article is published on: 5th February 2026
05.02.26
We are a team of fully regulated financial advisers working across Europe, with a strong presence in Italy since 2010. Our focus is on helping expatriates, and returning Italians from abroad, who are residents or want to become residents in Italy.
- Needing a professional to help you – Unless your financial affairs are really simple then you will likely need a professional to help you complete your tax return. Self declaring is complicated due to the codes used to complete the forms and so might not be worth your while due to the risks of getting it wrong. That being said you can get info online as to how to complete your tax return which is helpful.
- Reddito diverso e reddito di capitale – If you have investments in something like Exchange Traded Funds, for example, the income and capital gains are treated as one type of income (reddito di capitale) and the losses as another (reddito diverso). You can’t offset one from the other even though they derive from the same asset.
- Wealth taxes – Many countries do not have wealth taxes. Italy introduced them in 2014 when Mario Monti was Prime Minister. At the time politically, Italy was under the spotlight for its mounting debt and so wealth taxes were introduced as a way to generate more revenue for the country. Also, it harmonised the fact that taxes were paid on domestic assets but not on assets held abroad, at the time and so capital flight was rampant to evade taxes.
- Wealth tax on property – If you have a property outside the EU, then the wealth tax is calculated on the purchase value. This may seem strange but the market value is largely subjective depending on market supply and demand and would be difficult to determine. The purchase price is documented in the purchase contract and so is a definitive sum which reference can be made to.
- Choosing your tax rate – You can choose to have your investment income and/or gains taxed at your lowest rate of income tax IRPEF (23%), if available, or the standard flat rate on investment income (26%). This comes in useful if your total income is low and you can use up your first band of income tax. Otherwise, it’s normally better to go with the standard flat tax rate. You can also deduct certain expenses from the IRPEF choice, which can lower the rate even more. This is not possible on the standard rate.
- There are no personal allowances or nil rate tax bands for personal income. You start paying tax on Euro No 1. If you are in retirement and in receipt of a pension/ retirement income, you may get an age-related credit, depending on your income, otherwise you can deduct some expenses such as some building costs, vets bills, pharmacy expenses and doctors bills, which can reduce your income tax bill further.
Financial life in Italy 2026
By Gareth Horsfall
This article is published on: 22nd January 2026
22.01.26
For those of you who read my last Ezine you will be happy to know that I got my wellies for Christmas and also a more than welcome surprise of a toolbelt. I feel complete! I have been putting both to good use in the last week (seeing as though we have a good weather spell), by doing some early morning ‘potatura‘ of the olive trees.
I thought I would have a go myself this year since the chap who came last year hasn’t committed and it appears to be quite hard to find people in the area who are not already booked up. So, I thought I would give it a try after reading a few books, speaking with numerous people about it and watching far too many Youtube videos on the subject.
I am quickly realising how obsessive one can become when you are pruning olive trees, regarding correct shape, removing too much or too little and wondering whether the tree is growing too high, how to train it further down, whether to cut this branch or the other one. It’s quite therapeutic actually although it appears to be rather arbitary because we have no idea where the olives will produce, how many, and if environmental factors will affect production this year. However, as my 7.30am to 9 am morning routine (when not travelling) it is a good way to start the day.
Anyway, for my readers who have been doing this for many years, I will let you be the judges. See some fotos below. (Feel free to send comments about where I might be going wrong).
Moving on from land work I wanted to send this brief Ezine out just to reconnect in the New Year. 2025 proved to be a positive year for our investment accounts and it is anyone’s guess what is in store for 2026.
I am attending the Spectrum IFA Group annual conference from the 26th to 30th January and will be doing my usual round-up Ezine when I get back. We will be speaking with Rathbones Asset Management, Evelyn Partners, Prudential, New Horizon Asset Management, LGT Wealth Management and others as well.
But, before I return (hopefully Greenland will still be a part of Europe by then) I wanted to share some information on Italy with you, as a light hearted read.
On Facebook I follow a page called Dataroom di Milena Gabanelli. You may know of her from the programme ‘Report’, which is where I first became familiar with her around 15 years ago. Now she works for Corriere della Sera and has her own FB channel. It’s very interesting as they regularly put out content about Italy and global events but backed up with solid facts.
The most recent one I saw was ‘Chi paga meno tasse’. A look at the health system and exactly where tax revenue is coming from to support the system itself.
The following is summary of the video, which is only a few minutes long, but provides some quite interesting information, which I wanted to share with you.
(The data is taken from studies of contributi previdenziali relative dichiarazione 2023.)
Did you know that 76% of taxpayers in Italy declare less than €29000 gross per annum.
This group do not pay towards the health service because they are exempt. Their income is below the threshold set by the Italian government. (The ticket)
9% of taxpayers in Italy declare between €29000 and €35000 gross p.a.
This group pays for health expenses but not for welfare (pensions and schools!).
Only 15% declare over €35000pa.
This group contributes to both the health system and the welfare. They pay for the majority.
Let’s analyse things a little further
With an income of €29000 gross pa there is likely to be very little margin to pay your health care expenses. In this category fall many ‘pensionati and dipendenti’ and so we can exclude them for the purposes of the analysis.
The rest are autonomi ( self-employed people- like myself)
- 1.8 million autonomi in Italy are on the flat tax regime and so cannot be considered.
- 2.2 million autonomi pay IRPEF (normal income tax rates) and of these 1.3 million declare income under €29000pa. This means that they pay €2 billion in tax or ONLY 8% of the whole category for the autonomi.
To analyse further to see whether any of these people have a real need or if they are working in nero, we can look to the index ISA which looks at fiscal ability to pay. They work on a points based system and if a contribuente has under 8 points then there is the risk of fiscal evasion.
Tax Evasion vs Tax Avoidance
Here we have some interesting facts:
- 78% of restaurants declare less then €28000pa gross
- 70% mechanics under €20700 pa gross
- 60% alimentari under €10700 pa gross
- 48% hairdressers under €11900 pa gross and also 45% of balneari
Anyone who is declaring less than they actually bring in is also paying less contributions towards the health service and also they will receive less pension, which means that the people who are paying will have to pick up the bill.
The Agenzia delle Entrate are not funded well enough, even though they have some interesting tools at their disposal, and can do controls on only 4.5% of people / businesses annually.
It’s no surprise that the Italian government really doesn’t have much, if any, room for manoeuvre to change tax rates and why the health service is underfunded.
Short term rentals
If you like those facts you may also like the following ones about the explosion in short term rentals in Italy (affitti brevi), which go some way to explain why many cities and famous locations in Italy are now almost impossible to visit without a tremendous amount of people all doing the same.
- In 2011 short term rental advertisements didn’t exceed 20000 in the whole of Italy
- In 2021 this number had exploded to 620000
- In 2022 to 644000
- and 2023 to 700,000 which equates to approximately 11 billion euro invoiced a year
In the market of short-term rentals Italia is No 3 in the world behind the France and the USA!
If we analyse some of this data then we can see that 75% of these rentals are in the hands of private landlords and 25% managed by agencies.
Agencies, in general, retain 35% of the income to manage the cleaning and change of sheets etc. Almost all of the advertisements are now on the digital platforms like AirBnb and Booking.com, who in general keep between 14 and 18% of the income. The same platforms have been obliged since 2017 to apply a withholding tax of 21% on gross income.
In the Legge di Bilancio 2026 this withholding tax of 21% now applies to the first property. For the second a witholding tax of 26% and for owners of 3 properties or more, they are now deemed to be a business activity and must open a partita IVA (VAT position). The war on private landlords continues, not just here in Italy but across many countries, but whether it will make much difference in the long run is anyone’s guess.
If you have enjoyed this information so far, then I will leave you with the world of Italian politicians and how they are paid (c/o Dataroom di Milena Gabanelli)
They are paid well because they should, in theory, not be corruptible and should work in the interests of the country.
An Italian politician is entitled to a number of benefits, ranging from:
Indennità parlamentare, which is a compensation payment for being a politician and spending time away from home. It is currently €10435pm Gross or €5000-5300 pm after taxes and contributi.
Diara (per deputati e senatori) – just €3500pm
+ Expenses reimbursement.
These do not always have to be documented!!!!
They also qualify for reimbursement of travel expenses
And reimbursement of telephone expenses
Pensions
The same politicians are entitled to a pension after only 5 years of working in Parliament. (versus 20 years for the rest of us!)
Interest payments
They are also entitled to an interest rate of 5.4% on the money in their savings and current accounts. The bank pays this automatically versus the average rate for us , at about
0.2 %
And on that note I will leave it there. This Ezine was really was meant to be a light-hearted way of staying in touch.
I will be following this up from our conference with a market review from the week after next, followed by some other Ezines on tax and also organising your affairs for your loved ones.
Fraud and cyber-security
By Andrew Lawford
This article is published on: 14th January 2026
14.01.26
It’s time to pay (even more) attention!
We all know that we have to be careful when we are dealing with financial matters, especially when we are online.
I appreciate that this isn’t news to anyone, but it is easy to become complacent, as well as to fall behind in our awareness of the sophistication fraudsters have available to them in the era of Artificial Intelligence. I honestly think that we are all vulnerable to frauds, but if we have the humility to admit this, we can better protect ourselves against the most common pitfalls.
I recently watched a webinar made available by Cazenove Capital in the UK and whilst there were things in it that I already knew, I must admit that it also opened my eyes to how frauds are developing as well as reiterating what our best practices should be online and when dealing with financial matters generally.
I would strongly suggest that everyone takes the time to watch the full webinar, but here are a few bullet points that we all need to reflect upon:
- The golden rule in life is that if something seems too good to be true, it most probably isn’t true. However, human nature means that it is a good idea to be reminded of this fact on a regular basis.
- Most frauds are still relatively “low-tech” and involve things like hacking e-mail accounts – the fraudster may monitor e-mail traffic for a while before finding their opportunity, maybe by sending messages from your e-mail account to financial institutions you deal with. Two-factor authentication is an excellent protection against this possibility – if you don’t have it set-up on your e-mail accounts, do it now!
- Be careful clicking on links in e-mails you receive! These communications seem ever more credible nowadays and can easily trap the unwary.
- Any financial transaction that someone is urging you to carry out in a hurry should instantly raise a red flag. If you are being pressured to transfer funds, even by someone you know, hang up the phone, take a few deep breaths and call the person back on a number you know can be trusted. If you aren’t sure what to do, seek counsel from someone you trust who is not connected to the situation at hand. Deep-fake calls are a possibility (where it will appear that you are speaking to someone you know), but there are also cases where people have been contacted by complete strangers who claim that a family member is in trouble and needs money transferred in a hurry.
- If you do expect to have to make urgent payments to someone – maybe a family member or a business associate – use code-words or agree a protocol that only you and the person concerned will know. Agree in advance which accounts any payments will be made to. SEPA transfers in the EU will now confirm the identity of the beneficiary account holder – if your bank flags up any discrepancy between the name you have entered as beneficiary and the actual account holder, take time to check!
What is Spectrum doing to protect me?
For some time now, all Spectrum advisers are required to conduct video calls or in-person meetings when processing withdrawal requests from any investments we intermediate. The fact that withdrawals generally take some time before being paid out also takes away the threat of panicked decisions being made. Of course, one day deep-fake videos will likely become a reality and so even video calls may not be trustworthy, but for today this procedure will protect against all but the most sophisticated fraudsters (and these aren’t the ones who are targeting the likes of us – they will be defrauding multinational institutions).
We must make our job that of being a harder nut to crack compared with those around us. Rather like home security alarms: they will not be sufficient to stop the world’s most sophisticated thief, but they will be enough to make the opportunistic criminal move on to an easier target.
If you find yourself confused or worried about any of the above, please don’t hesitate to give me a call to discuss. The more we are aware of the risks we face, the better we can protect ourselves.
Hoping for wellies! 2025
By Gareth Horsfall
This article is published on: 24th December 2025
24.12.25
It’s Christmas again and how the time flies!
I am hoping for a new set of wellies this year because the emergency pair I bought when we purchased the property didn’t last very long at all.
I sent out a not-so-subtle message to my wife and so I hope my Christmas wish comes true.
I will then be able to also complete my true Yorkshire look in Umbria.
I hope you have a very Merry Christmas and Happy New Year, whatever you are doing.
We will be relaxing at home this year. My Mum has just been for a few days to visit (she hasn’t seen the house since June 2024 when we were in the phase of renovation) and so it was good for her to see it for herself. We are now on our own, but have lots of fun things planned. My son will be playing in the local Pasticceria Russo, in Amelia, this evening (23rd) , playing one of his newly learned Beethoven classical piano pieces.
The Pasticceria is becoming a bit of a focal point for us in the area (as it seems to be for alot of other people as well) and they have their amazing range of sweets and Panettone artiginale, which is a little bit too more-ish for my liking. I am trying my best to resist the temptation and am doing OK, until now! The only way to combat that is to engage in more physical land work anyway. As many of you have told me since we moved here: ‘there is always work to do on the land’.
It will keep me out of trouble until I am back into work full-time in the New Year.
Fiscal residency and corresponding tax returns in Italy
By Gareth Horsfall
This article is published on: 20th November 2025
20.11.25
Have you got it right?
In this article we briefly turn our attention the question of registration of residency in Italy and corresponding tax returns.
I have been contacted by a number of people since September who have received letters from the AdE, this would not normally picque much interest for me because the AdE send regular letters out to try and weed out potential errors or omissions from your tax return in fact I have had a few myself over the years.
However this letter was of particular interest because it broached the subject of residency and non declaration of assets, at all, ever.
Over the years I have seen many times where someone has made a tax declaration, but where errors have been made and / or omissions, and the AdE have eventually caught up with the error and the individual concerned has had to correct the error, pay the back taxes and penalties. Fair enough mistakes happen and often through bad advice on the part of the commercialista but one category of people who seems to have evaded the oversight of the AdE were those people who are resident in Italy, and for one reason or another have never made a tax return here. The main reason is because they were badly advised by a commercialista to not ‘enter the system’ or that they were declaring in another country thinking that it wasn’t necessary to do so in Italy.
However, it may look like that particular issue has been uncovered by the AdE, in fact, in a short period of about 5 weeks, I had 6 people contact me, all with very similar situations, relating to not having filed for taxes in Italy and subsequently receiving a letter from the AdE asking them to visit their local AdE office and explain the anomaly.
Whether this is an awakening for the AdE for merely just a blip is anyone’s guess but I suspect they have finally got the right hand speaking with the left hand and they will weed more of these issues out in the near future. It all corresponds nicely with the change in definition of residency from Jan 1st 2024 and so is probably the start of a wider push to make sure that everyone is doing what they should be, whether they know it or not.
So, in short, if you are resident in Italy then it is more than likely that you should be declaring your financial situation for taxes each year, if a commercialista tells you that you shouldn’t or don’t need to file, then you need to question that and not just take their word for it. I would request written, signed confirmation that this is the case. Equally, filing for taxes in another country, thinking that this is sufficient, is generally the wrong thing to do and you may want to explore this further to avoid eventual contact from the AdE.
If you happen to be in this situation and are wondering what steps to take, do not hesitate to get in touch. I have helped many people through this situation in the past, it’s better to address the matter before being picked up by the AdE.
Now, let’s move on to the subject of the UK property market.
“Property is the best investment”
I don’t know how many times I have heard this said to me in my career, which has spanned an era when property investment probably has been one of, if not the best investment to make.
However, everything is cyclical and whilst UK residential property may have been a great investment, that doesn’t mean to say it will be forever. In fact, the UK property market has stalled, at the time of writing, and it remains to be seen whether it is just a pause for breath or part of a longer period of downturn for the UK property market. As I have repeated many times in the past, in times of needs, governments will turn to the real estate market to generate tax revenue because it is has been the go to investment of choice for most people. The UK budget will roll around at the end of this month and we will see what kind of moves Rachel Reeves makes on the UK property market, it is expected that she will tax properties over a certain value, but little is known at this time. (I spoke with an investment manager in London recently who said they are bracing themselves for a ‘brutal’ budget, were his exact words).
However, as usual these are just my musings.
To explain in a bit more detail Rathbones Investment Management recently wrote a great article for a professional publication and I thought to share this with you here.
The UK’s love affair with property investment is apparent across newspapers, daytime TV and social media. An English person’s home may be their castle – they’ve also regarded it as their nest egg (and the same for other Britons). Many have even bought additional castles, such is their ardour for property. Reflecting this, official figures show more than 2.8mn private landlords in the UK.
However, the days of strong returns from residential property are already past. The past decade has seen three pieces of bad news. House price growth has been slower; higher interest rates have squeezed the buy-to-let business model; the regulatory treatment of private landlords has become progressively less favourable.
The economic and policy outlook suggests those headwinds won’t dissipate. From 1980 to 2016, UK house prices rose 6.7% per year in absolute terms, or 3.3% in real terms (after allowing for inflation). Prices in London rose even faster: 8.5% in absolute and 5.0% in real terms. That rate of capital appreciation is considerable – and investors making an income from renting out properties would have made even more.
It’s difficult to compare returns from property exactly with returns from other investments, for various reasons – such as the cost of mending that leaky roof. But taking the crude numbers, the capital appreciation of a portfolio made up of 25% UK equities and 75% international equities would have been only slightly higher at 9.0% per year or 5.5% after inflation.
What drove high house prices?
What lay behind this? One cause is higher wages. As earnings have risen in real terms, households have been able to spend more on housing.
Between 1980 and 1998, the average UK house price rose by 2.6% above inflation per year. So too did the average wage. As result, the house price-to-earnings ratio – the average house price divided by average earnings – was similar in both years, at around 4.3, although it did fluctuate a lot between these two points.
However, since 2000, the ratio has risen to as high as 8 and never fallen below 6. So pay can’t be the whole story behind the price rises.
A fall in interest rates helped sustain higher house prices relative to earnings. Double-digit mortgage rates were the norm in the 1980s and early 1990s. But these dropped to as low as 1–2% by the late 2010s. This shift allowed buyers to borrow a lot more money for any given level of monthly repayment, bidding up house prices.
Other changes to the mortgage market have probably helped push UK house prices higher, by increasing the availability of loans and encouraging property investment. These include the entry of banks into the mortgage market, the introduction of buy-to-let mortgages, and market innovations, such as the government’s Help to Buy scheme.
Moreover, housebuilding has failed to keep pace with population growth over the past fifty years or so. In other words, demand has risen faster than supply.
Productivity, rates and policy
But conditions for house price growth now look much less fertile. After a period of far outstripping inflation, average earnings have grown much more slowly lately. Even if we ignore declining real wages in the early 2010s, they’ve only outpaced inflation by 0.5% a year since 2016. In the long run, real-terms wage growth is closely linked to productivity – companies generally only pay their workers more if they’re getting more from them. But productivity growth has in recent years been low – and we don’t foresee a dramatic improvement anytime soon.
Moreover, mortgage rates have risen in the past few years. The average 2-year fixed-rate 75% loan-to-value mortgage rate has climbed from 1.2% in 2021 to above 4% since 2022, according to the Bank of England. This has pushed up first-time buyers’ repayments. We don’t see a return to the abnormally low interest rate environment of the 2010s.
On top of higher interest rates, unfavourable tax changes and tighter regulation have added to costs. For example, stamp duty on additional properties was hiked in 2016 and again in 2024.
Moreover, the housing supply pipeline is flowing better. Although the government has fallen short of its housebuilding targets for years, the annual net increase in dwellings has crept back up since 2015, returning to above 200,000. On this measure, the housing stock is growing at the fastest rate since the 1960s.
End of the affair
With those fading tailwinds in mind, it’s little surprise that UK house prices have risen by a much more pedestrian 3.7% per year, in absolute terms, since 2016. That’s only about the same as inflation. Over the same period, the portfolio of UK and international equities we mentioned earlier rose by 7.2% a year.
We think this trend will continue. In our view, it may be time for the British to break off their love affair with the housing market and embark on a new one, with a diversified portfolio of financial assets. After all, 10- year UK government bonds offer yields above 4% and there’s a wide selection of high-quality names across the world’s stock markets. It might not be the most romantic of trysts, but we think it’s likely to offer them a better return in the long term.
Are we in an A.I and tech stock bubble?
For those of you who can remember as far back as the year 2000, as an investor, you may remember the investors favoured around the possibilities of the introduction of the internet (I think we were still working on dial-up connection at the time and my phone was probably a Nokia 3310. The world of today’s smart phones was about another 8 years away, when the iPhone first launched). I remember being at a business meeting in Geneva in 2005 and there was talk of being able to call over the internet from your phone in the near future and being able to answer emails more easily on your phone.
Little did we know how far we would come so quickly ! In the year 2000 there was much hype about this future and that fuelled what is now called the ‘tech boom’ in dot com stocks. Inevitably, this created a bubble in dot com stocks and a subsequent crash in the markets when investors realised a lot of the hype was largely based on fresh air and not much substance.
I have been asked quite a few times in the last month or 2, about the possibility of something similar happening in AI and tech stocks today.
It must be said that the circumstances are quite different this time round. Companies are actually profitable in 2025, and A.I will create problems in the employment market, but also deliver productivity gains.
(Interestingly, I saw an article the other day saying that Italian companies who had laid off employees to benefit from cost and productivity gains from the introduction of AI systems, were doing an about face and re-hiring those same workers because they realised that AI was not going to deliver all those gains which they had been promised).
Anyway, rather than writing a long discourse on the topic I asked Chris Saunders of New Horizon Asset Management what he thought, on this short video with my question and his answer. I hope you find it interesting.
IRPEF (income tax) rates set to drop again!
As part of Giorgia Meloni’ s government’s promise to the Italian people, IRPEF ( income tax) rates would be simplified and even reduced with their long term goal of having a much more simplified tax system ( good luck with that Giorgia !).
In the Legge di Bilancio 2026, which is currently being debated in parliament, they have proposed to reduce the second progressive rate of income tax, which currently sits at 35% for gross income between €28001 and €50000pa, to 33%.
Now, as I have often been heard saying, they are just playing around the margins and this kind of tax reduction will hardly have any real impact for most people who might be struggling with higher prices of the last few years and facing a continued erosion of their income. However, it is still something and in line with the promises made by the current sitting government. (At time of writing it does look like this will be approved and implemented from 2026).
Possible increased tax on rental properties?
This is the one that is creating the greatest political friction at the moment and, so what is it?
The proposal is to increase the cedolare secca tax on rental properties from 21% to 26% from 2026.
Cedolare secca 21% is the tax that is paid on rental property income, where selected, and is a kind of forfeit rate. The income from cedolare secca is not taken into account when calculating your other total income subject to income tax (IRPEF) and so is quite attractive for most. There are some disadvantages, which I won’t go into here because in the main the 21% tax rate is the go to option for most. However, it is proposed to bring this up to 26% on rental income (for private renters, rental agencies and rental agencies online).
As per the UK, see above, real estate is a go to cash cow for governments when they are looking to raise revenue and so this move (although likely to be watered down or removed altogether because Forza Italia are not in agreement and will not vote for the proposed change) is something that we will likely see happen more often.
If, as may be intended, it is being introduced to cool the housing market and, especially in the big cities, cool the rental market itself, I am sceptical that it will have an effect at all. Having lived in Rome for the last 20 years and seeing the explosion in the Airbnb apartment for rent, and the constant stream of tourists to occupy those places then I can’t see that an increase of 5% will hurt that much, other than those who have high debt levels to service.
Anyway, it’s something worth watching, in case you have a rental property, or part of property in Italy which you are generating income from.
London’s attractiveness as an International financial centre.
There has long been talk of London being one of the world’s premier financial centres and for some time, I think, it held the No 1 spot for a period as well, however, that would appear to be changing.
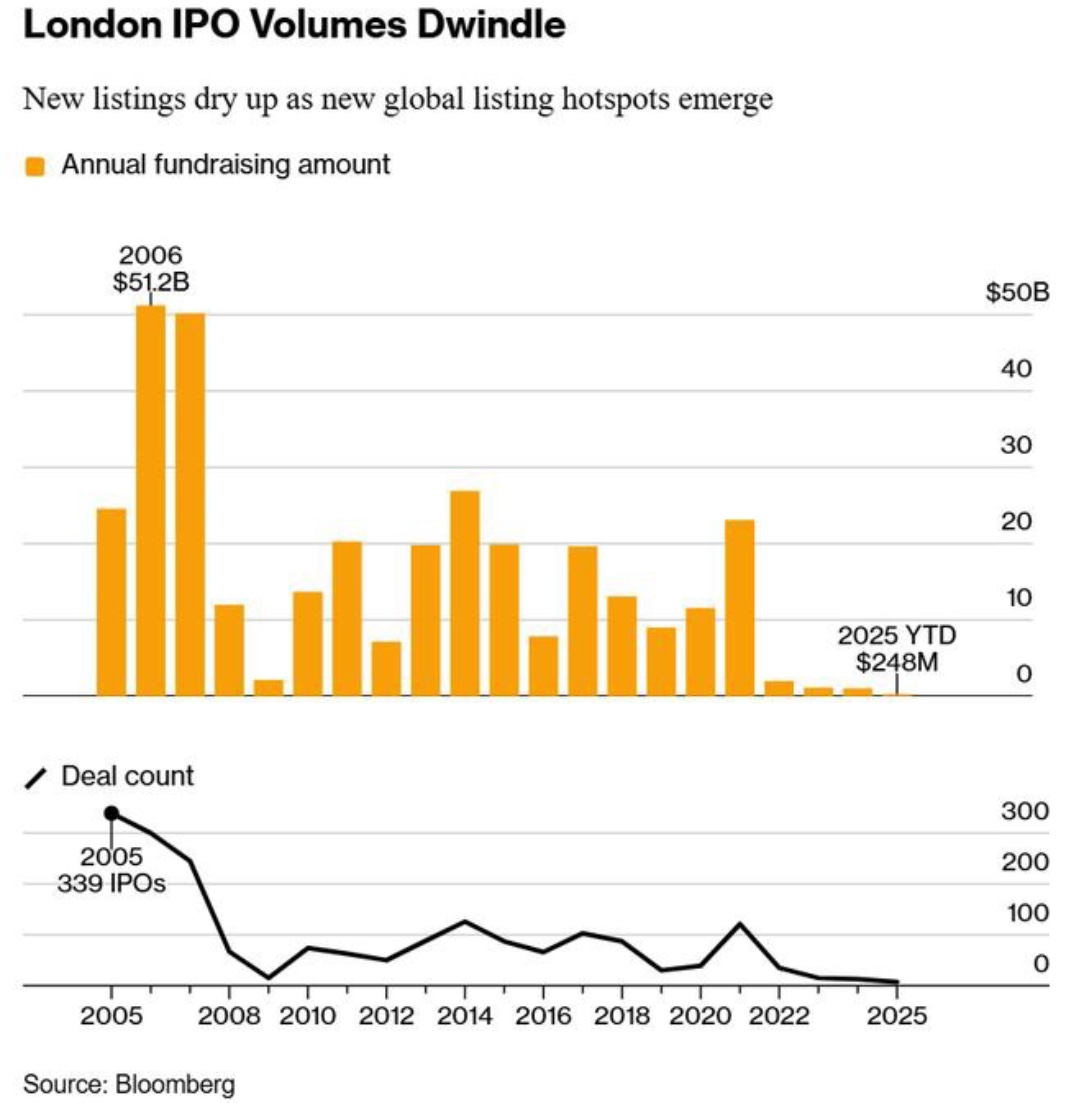
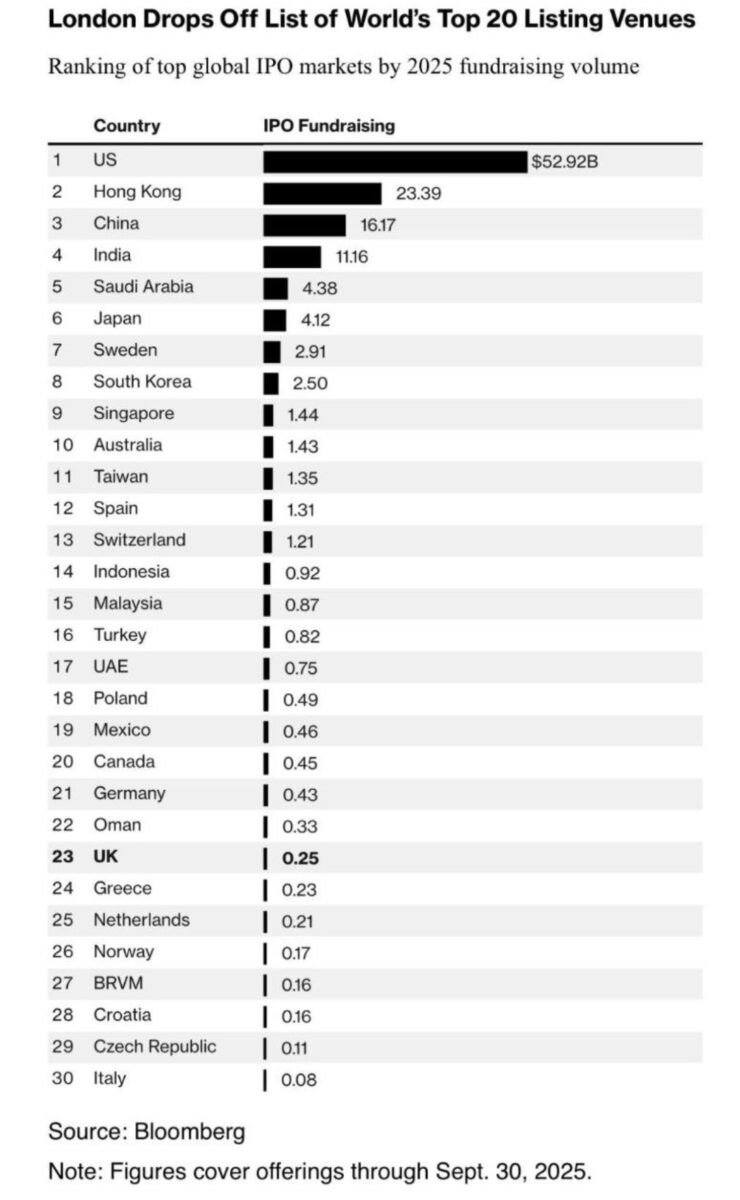
On one of my economist social media feeds, I saw these graphics recently which I thought I would share.
An IPO (Initial Public Offering) is where a private company decides to list on the public stock exchange so that it can raise capital and offer its share to investors. They normally choose to do this when they reach a certain size, as a way of accelerating company growth. In which jurisdiction they do this is important because it can generate a lot of revenue for the financial sector in that country, create jobs and also secures the attractiveness of the financial centre as a place that is deemed safe and secure to list publicly.
London used to be one of the preferred jurisdictions, but as you can see, in 2025, that is no longer the case. London now holds spot No 23 on the list behind some important newer entries, such as Hong Kong, China and India.
What this says about London’s long term future is anyone’s guess but it is interesting information all the same. (Could Brexit have played a part?) . It probably says more about the ever increasing importance of Asian economies and the continued importance of the USA.
Spectrum IFA begins Employee Ownership for a Sustainable Future
By Spectrum IFA
This article is published on: 14th October 2025
14.10.25
Empowering People, Ensuring Continuity, and Deepening Commitment to Clients
At The Spectrum IFA Group, our success has always relied on our people, their expertise, dedication, and a shared belief in doing what is best for our clients. As a firm founded on trust, transparency and building long-term relationships, we recognise that sustainable growth depends not only on sound financial advice but also a solid grounding in joint ownership and responsibility.
Since its inception, Spectrum has aspired to share company ownership with its advisers and staff. Establishing a clear succession plan is essential, not only to ensure business continuity but also to provide long-term security for our advisers, employees, and most importantly, our clients.
Today, Spectrum’s advisers and staff collectively hold over 15% of the company’s share capital. This initiative reflects our belief that those who contribute daily to looking after our clients’ interests should also participate in the company’s growth. In 2026, Spectrum plans to increase employee and adviser equity participation to approximately 30%. Our longer-term intention is for advisers and employees to own 48% of the business, with the remaining 52% retained by the founders.
This approach demonstrates our commitment to creating a resilient, people-focused organisation where everyone has a vested interest in delivering exceptional advice and service. By aligning ownership with those who directly support our clients, we are securing our longevity whilst embedding the long-term continuity of relationships that help define our unrivalled service standards.
At Spectrum, we view this as more than simply an exercise in restructuring company ownership – it reflects of our core values. We are building an organisation that empowers people, rewards dedication, and safeguards the future security of our clients, advisers, and employees alike. Together, we are shaping a stronger, more sustainable Spectrum team for generations to come.
Financial update Italy – September 2025
By Gareth Horsfall
This article is published on: 8th September 2025

08.09.25
Hello again and welcome back to my Ezine after the summer break. I hope you are well and that the somewhat fresher Italian summer was a surprise for you as well. We were not sweltering in 38 degrees this year but enjoying a more pleasurable low 30s for most of the summer. It was a welcome change from last year, for example, when I saw the last rain in mid-May and not again until mid/end Sept.
It was also my first holiday away after our change of lifestyle to the country and with all this land, trees, and plants to manage. I have to say that although time at the beach was great and a welcome break from the country, I did find myself wanting to come back and see how all the plants were doing and also how the olives were developing after lots of summer rainstorms. It was pure curiosity because on my return I found that the whole situation is largely as it was last year at the same time. Grass needs cutting, and a few other jobs need doing, but in general everything is coming along nicely.
For those of you with whom I am friends on FB, you will have seen that I came back to a bumper crop of apples, pears, and figs. The figs are finding their way into my pancia quite quickly and are super delicious. (and I have my new wicker basket for collection – which my wife jokingly bought me at a ‘sagra’ event recently, very Laura Ashley)
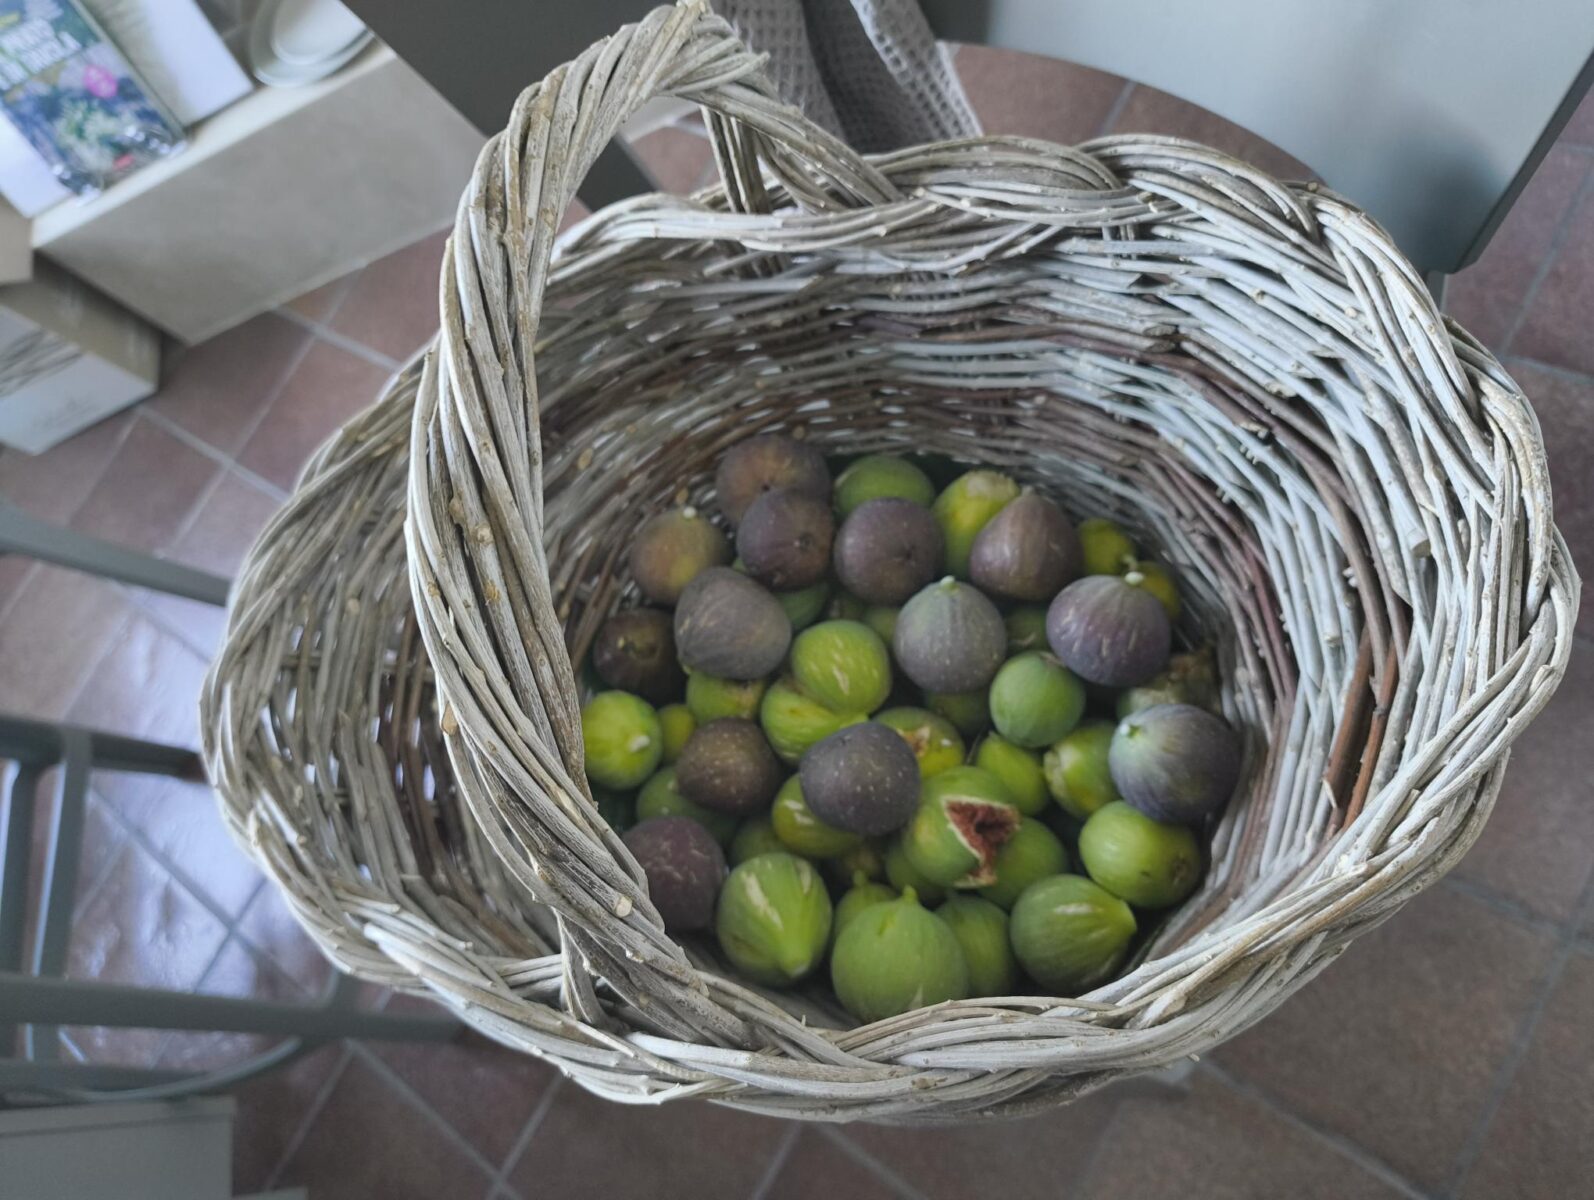
Amelia is famous for its figs, so it’s no surprise that the trees are full of fruit again, exactly the same as last year. The apples and pears, I have now discovered, are different varieties and were pretty much falling off the tree, so I harvested the rest and they have now gone into cold storage until I can get round to doing something with them. (My mum reminded me that my grandfather used to sell fruit and veg and, to preserve fruit, he used to wrap each single piece in newspaper and then put them in cold storage somewhere. Apparently they kept for a few months.
Mine have gone into the underground cellar, which hosts the resident bats. It maintains a constant temperature of about 12 degrees all year round. They can stay there until I get round to dealing with them shortly).
The break also gave me some nice time to reflect on landscaping, round No. 2, this winter. I have made some decisions on some trees which are currently unmanageable. I think I will be lopping off the tops and starting to prune them again into smaller and much more workable trees. Also, I had some ideas about other landscaping possibilities, but one step at a time. Of course, there are the olives to deal with in a couple of months and they seem to be coming along just fine, although the mosca has attacked many this year due to the cooler and wetter summer temperatures. Also, after a serious potatura in the spring, the fruits are fewer than last year. I just hope that the oil content is higher. It’s all a big learning curve!
So now my country life update is out of the way, onto the financial context of this Ezine, but before that I also wanted to share with you some rather disturbing news which I think you should all know about, whether a client or not……..and to watch out for.
Fraud and AI
Earlier in the year we introduced some new security protocols regarding withdrawals from policies/portfolios which clients hold with us. We had been made aware that another financial planning company operating in the Middle East had received a fraudulent request to withdraw funds from a client portfolio. But in this case it turns out that it wasn’t the client making the request, but in fact some Artificial Intelligence application. The worrying aspect of this was that the adviser was contacted directly by the client on WhatsApp and email asking to withdraw a sum of money and have it paid to their nominated bank account. The adviser had an exchange of messages with the so-called “client,” not suspecting anything untoward. When the money had been paid, the actual client rang to ask the adviser why money had been deducted from his portfolio.
I think you can probably understand the ins and outs of this situation. It was a fraudulent approach using Artificial Intelligence.
AI certainly has its positive uses (I have translated some of the content in this Ezine from Italian to English which used to take me a long time, but was done in 3 seconds). However, this is certainly one very dangerous and worrying angle.
Therefore, since the start of the summer The Spectrum IFA Group have introduced a policy of meeting with the client in person or, if not possible due to geographical restrictions, then an video call with documentation required, where a withdrawal is requested. A phone call is not acceptable, nor purely communication via message or email.
We have introduced this to protect our clients and will keep track of the situation as and when we hear more. However, whether you are a client or not, please be alert to messaging and emails when dealing with your financial affairs. Try and engage either in person or via video call ONLY. Do not assume that messages or emails are from the actual person. If in doubt, pick up the phone and call!
Capital gains tax on the sale of property in Italy
I am not sure why, but like buses, the same query seems to crop up multiple times at the same moment, and so it happens that I received a number of queries this summer around the capital gains tax on the sale of property, as a resident in Italy and specifically the implications of selling property either in Italy or abroad.
So let’s look at the details…
The baseline rule is that if you are a resident in Italy and you sell a property after the first full five fiscal years from purchase (not your Prima Casa – different rules apply here, read on for details), you are NOT required to pay tax on any capital gain (CGT) resulting from the sale. This applies to properties you hold in Italy or abroad and applies whether it is your 2nd or 15th property!
This stems from the idea of a speculative intent to buy/sell property and where there is no intent then capital gains tax is not applied. (a nice tax planning opportunity!)
Speculation in Italy is defined as follows:
- the property is sold for consideration (e.g. sale, exchange, contribution to a company)
- the property is sold within five years of purchase or construction
- the property must not have been used as the seller’s (or family’s) main residence if it is a residential unit.
These rules also apply to property located abroad!
If the sale is subject to taxation (because you are selling within the first 5 years since purchase), then you can either opt for:
A substitute tax of 26% (standard capital gains tax rate) at the time of the deed (the notary is responsible for the payment), or
The standard income tax rates (IRPEF), with the possibility of using deductible and creditable expenses such as bonus edilizie, pharmacy expenses, doctors’ bills, etc. Bear in mind that the lowest rate of income tax in Italy is also 23%, so depending on your other income for the year you could fall in the lowest rate of income tax (€0–28,000 p.a.) and be able to reduce the taxable amount even further with deductions.
Below is a list of the main rules to consider:
Taxable conditions
As with all things taxation, it is important to understand the conditions:
- Capital gains tax applies as a result of property purchased, or built, less than five years earlier.
- An exemption is given for urban residential units that, for most of the time between purchase (or construction) and sale, were used as the main residence of the seller or their family. (The idea of Prima Casa)
- As well as, in all cases, capital gains realised from the sale of land that can be used for building (terreno edificabile) according to planning rules in force at the time of the sale.
In the case of donated/inherited property, the five-year period is calculated from the donor’s acquisition date.
(This is particularly important for anyone who might inherit a property from a deceased parent, for example. If you wish to dispose of the property it would be more advantageous to do so in the probate process, otherwise you may have to wait another 5 years before you could dispose of the property to avoid capital gains tax…. if any). However, if you take the property into your name and then can sell it quickly, you may avoid capital gains tax if the property value has not increased between the acquisition and sale.
Exemptions
Exempt from taxation are:
- Sales of properties used as the seller’s or their family’s main residence for most of the period between purchase/construction and resale (the 5-year rule does not apply here – Prima Casa rule!).
- Sales of inherited properties (per Article 67, paragraph 1, letter b) TUIR).
The five-year rule
The 5 years run from the purchase deed (or from the later date of transfer of ownership rights).
- If built by the seller, then the 5 years run from completion of construction.
- The period ends on the date of the sale deed, regardless of when payment is made.
- Renovations or extensions do not restart the five-year period!
Speculative operations: property flipping
If you fancy yourself as a property magnate and decide to try your hand at buying, renovating, and then selling repeatedly within the 5 years (“property flipping”), this constitutes a commercial activity and in this case:
- The capital gains are taxable, and
- The seller is required to operate as a business with VAT registration and related tax and social security obligations.
Calculation of taxable capital gain
It’s a simple formula:
Sale price – (Purchase price / Construction cost + related documented costs)
Allowable related costs include:
- Notarial and accessory expenses,
- Indirect taxes paid at purchase (registration, mortgage, cadastral taxes, or VAT),
- Improvement expenses (extraordinary maintenance, renovations),
- Costs for removing tenants.
It is important to keep all documentation relating to any property purchase/sale for at least 10 years in Italy.
For construction:
- Building contracts, design fees, municipal charges, post-construction improvements.
The gain is taxable in the year the payment is received.
Taxation methods: IRPEF (income tax) or substitute tax (flat rate of 26%)
Capital gains from property sales fall under “other income” (reddito diverso) and you have 2 options for taxation:
- Ordinary IRPEF (income tax) – the gain is added to your total taxable income and taxed progressively (23% up to €28,000, 35% from €28,000–50,000, 43% above €50,000). Deductible and creditable expenses can reduce your tax.
This is a nice potential financial planning option because you may choose to split the tax between spouses by sharing ownership, or put it in one person’s name rather than another to maximise your lowest income tax brackets. It has multiple possibilities and should be explored should the need arise.
- Substitute tax of 26% – flat tax, applied at the time of the notarial deed. The notary withholds and pays it. No deductions/credits can be offset. This is also not subject to tax audit, so may be a preferable option for some.
Generally, taxpayers with other taxable income find the 26% substitute tax more advantageous.
Other cases
- Donation: 5 -year period runs from donor’s acquisition date.
- Built by seller: 5-year period runs from completion.
- Main residence: exempt if used as main home for most of the ownership period, even within 5 years.
- Building land: always taxable when sold; substitute tax cannot be applied.
- Agricultural land: taxable only if sold within 5 years.
- Property with buildings to be demolished: treated as building land → taxable.
- Previously subdivided property: taxation depends on whether subdivision counts as new construction.
Statute of limitations for tax assessments
The Agenzia delle Entrate can assess omitted/under-reported gains:
– Within 5 years from the year after the tax return was filed;
– Within 7 years if the return was omitted or invalid.
So there we have it. All the facts regarding capital gains tax and property in Italy. For most people I know it rarely comes into consideration because the properties are owned for more than 5 years. However, on odd occasion CGT needs to be considered. For somewhere like the UK that introduced CGT on property purchases for non UK residents, the tax interest lies in the UK and not in Italy which is a relief because you don’t have to worry about paying it in 2 places. However, if you think it is applicable to you, then take the necessary advice before you sell.