
Since 2019 Italy has been running a special tax regime of only 7% tax for pensioners (anyone drawing a retirement income) if they relocate to the Southern states of Italy. (Sicily, Calabria, Sardinia, Campania, Basilicata, Abruzzo, Molise or Puglia – or to certain areas affected by the 2009 or 2016 earthquakes)
Viewing posts categorised under: Italy
The 7% tax regime for pensioners in Italy
By Gareth Horsfall
This article is published on: 1st May 2026
01.05.26
The regime pensionati was always limited to towns/ cities, which had less than 20000 registered residents. However, from April 7th 2026 it is extended to towns /cities with up to 30000 residents, which extends the number of possible towns/cities to which you could locate and more importantly have access to important services such as hospitals, medical services, shopping and sports facilities etc.
According to the Italian statistics agency (ISTAT), the majority of comuni in the southern states in this tax regime have less than 30000 inhabitants. IN fact, if we look at how many have more than 30000 residents, the numbers are more startling:
Sicilia (Sicily): 30–35
Campania: 30–35
Puglia (Apulia): 25–30
Sardegna (Sardinia): 8–10
Calabria: 7–8
Abruzzo: 8–10
Molise: 0 (Only Campobasso and Termoli are near or above this threshold historically, but often fall under it depending on current census updates)
Requirements to qualify
- You must have a pension plan which is held with a foreign company
- You must have been resident outside Italy for at least the last 5 consecutive tax years before transferring residency.
- Moving from a country, which has a tax cooperation agreement with Italy.
Important points you need to know!
Whilst this all sounds very exciting, there are conditions to the qualification.
- The pension plan, from which you will draw this income, must have been accumulated from earnings from employment. (self employment or employed work).
- You WILL NOT qualify if you merely add a lump sum of capital into a pension plan before moving to Italy to try to qualify for the tax regime.
- The income that you draw from your pension will be assessed, and whilst there are no specific guidelines, it will need to be sufficient to support your lifestyle in Italy. This will vary from region to region and depending on who is assessing the application. When you make the application, it is best to check with your commercialista at the time.
- The 7% tax is calculated each year on your ‘reddito complessivo’ (cumulative income) NOT just the income from your pension. Reddito complessivo in Italy refers to numerous potential income sources, as follows:
- Income from land or building situated outside Italy.
- Income from capital overseas (dividends, interest etc)
- Income from employed work from outside Italy
- Income from self-employed work where it takes place outside Italy from a fixed place of residence. E.g where you are registered for work purposes in the UK
- Income from businesses abroad.
- Capital gains from the sale of shares in non-Italian resident companies.
- Income from asset held outside Italy.
- Business income generated abroad
- Interest from bank accounts and deposit accounts, national savings and investments and other deposit based savings.
- Capital gains arising from the sale of shares in non-listed companies
Qualifying individuals pay a flat 7% substitute tax on all foreign-source income, in place of ordinary progressive income tax rates. You are also exempt from the property wealth tax and wealth taxes on foreign assets and are relieved of the foreign asset monitoring obligations that would otherwise apply.
Financial Planning considerations
Whilst this may seem a relatively straightforward and simple choice, it does make sense to do some careful planning before you apply.
For example, by using ISA’s in the UK, you can potentially realise capital gains before leaving the UK and re-set the clock on future gains. However, timing is important!
In addition, if you do not have assets in ISA’s you may be able to ‘bed and breakfast’ assets in your portfolio before becoming resident in Italy, to reduce capital gains tax liabilities.
You may also be able to make better use of accumulation style investments rather than income distributing to reduce your tax liabilities even further. Why pay even 7 % tax if you can pay zero?
(You pay 7% on capital gains and income ‘realised’ in a portfolio – not just used as income, and so an actively managed portfolio may produce realised, and hence, taxable ‘Italian income’ even if you are not using it for living expenses!!)
If you are a business owner who is looking to retire or sell your business, then you might be able to use the tax regime to reduce your potential tax liabilities.
These are just a few of the possible financial planning considerations that you may need to make.
You will need to plan to get the best benefits from your 7% tax regime tax residency before, during the transition year to Italy and your Italian tax residency itself.
Rental Income from Properties Overseas and How to Declare It in Italy
By Gareth Horsfall
This article is published on: 29th April 2026
29.04.26
One of the questions I am asked regularly is how income from property held overseas is taxed in Italy. Many people wonder whether rental income is exempt from Italian tax because tax has already been paid abroad, and whether it is treated in the same way as rental income from Italian property.
To be absolutely clear, if you are an Italian tax resident, you must declare and pay Italian tax on the net profit from rental income on properties held overseas. The arrangement is reciprocal: if you were resident in another country and owned rental property in Italy, you would also be required to declare that income there.
Italian tax law states that the net profit, after allowable expenses, from property overseas must be declared in your annual Italian tax return. This net profit is added to your other income for the year and taxed at your applicable income tax rate. In addition to income tax, IVIE — the tax on foreign real estate — applies. IVIE is calculated as a percentage (currently 1.06% [2026]) of the property’s value (purchase value if outside the EU and cadastrale value equivalent if inside the EU) as defined by the rules of the country where the property is located. Even if tax has been paid in the country of origin, you are still required to declare the income in Italy, and annual declarations must be made regardless of foreign tax paid.
There is, however, a legitimate way to reduce your Italian tax liability. If the rental income is declared in the country of origin and all allowable expenses are deducted there, then only the resulting net profit needs to be declared in Italy. This can be advantageous because some countries allow a wider range of deductible expenses than Italy. In certain cases, it may even be advisable to file a tax return in the country of origin, even if that country no longer requires you to do so, simply to document expenses clearly and establish the net profit figure. By doing this, you provide the Italian authorities with evidence of your expense deductions, and the net profit declared in Italy may be significantly reduced, sometimes even to zero.
It is important to understand that all rental income from overseas property must be declared in Italy if you are an Italian tax resident, and what you declare is the net income after expenses rather than the gross amount. The net figure is then added to your other income and taxed at your applicable IRPEF rate. IVIE also applies to foreign property, and declaring the income and expenses in the country of origin can help reduce the taxable amount in Italy. Lower expenses result in a higher net profit and therefore higher Italian tax, while higher expenses reduce the net profit and may lower your Italian tax liability.
Depending on your goals, owning property overseas can work in different ways. If you have high expenses, the property may function well as a long‑term capital appreciation investment with little taxable income. If you have low expenses and high net income, particularly if you rely on the rental income in retirement, you may find yourself taxed at higher IRPEF rates in Italy.
Have you got an old Italian bank account?
By Gareth Horsfall
This article is published on: 28th April 2026
28.04.26
During the course of my many conversations, one particular issue comes up all too frequently, and I felt I just had to write about it.
What am I talking about? I am referring to the basic bank accounts that people use in Italy — those accounts that were probably set up when you first moved here, perhaps because the person you were buying a house from suggested opening an account at the same branch to make life easier, or because you were referred to the local bank simply because “everyone uses it”, or because someone knew someone who could open an account for you even before you were officially resident.
Unfortunately, many of us are still being charged extremely high bank fees for very little service. Some of the traditional banks remain among the most expensive, and yet they are still widely used by foreigners who opened their accounts years ago and never revisited the issue. I continue to meet people who are paying unnecessary quarterly fees, high commissions on simple transfers, and additional charges for cash withdrawals or currency conversions. In some cases, the total annual cost can be surprisingly high.
The problem is that many people assume that changing bank accounts in Italy is too much hassle, or that “they are all the same”, or that banking back home is better so they simply tolerate the situation.
But this is no longer the case. Italian banks — especially online banks — have become far more competitive, and there are now excellent options available that offer modern services at very low cost.
Personally, I use two banks: one for personal use and one for business. My personal account is with Fineco, which remains one of the most efficient and user‑friendly online banks in Italy. It is fully digital, easy to use, and offers a very good app. Customer service is responsive, and the account has no standard maintenance fees if you meet basic usage conditions. Withdrawals from cash machines across Italy are free, and domestic transfers cost nothing. For basic banking, it works extremely well.
My business account is with Banca Intesa Sanpaolo, which is part of a larger national network. I chose this because, as a business account, I occasionally need to speak with the bank director, but otherwise I operate everything online. The monthly fee is modest, and transfers are inexpensive. It is more costly than my personal account, but that is to be expected for business banking.
There are also several other personal banking options in Italy that offer low‑cost or zero‑cost accounts, especially if you are comfortable with online banking. CheBanca!, ING, Hello Bank, Widiba, and N26, Revolut, and Wise all offer modern apps, free withdrawals, and free domestic transfers. Comparison websites make it easy to check current offers and see how much you could save by switching.
My simple message is this: pay some attention to your bank account in Italy if you have not done so for some time. It is not difficult to change accounts anymore, and with even basic Italian you can manage the process without problems. You could be making significant savings simply by switching to a more modern and cost‑effective bank. If someone is paying hundreds of euros a year in unnecessary fees, then it is certainly worth reviewing.
Take a moment to look at your recent bank statements and see what charges you are paying. Then compare them with what is available today. You may be surprised at how much you could save.
Tax deductions and detractions in Italy
By Gareth Horsfall
This article is published on: 23rd April 2026
23.04.26
Spese Detraibili e Deducibili in Italia
Italy does not have a system of taxation with a tax free allowance system and therefore tax is paid from the very first Euro.
However, Italy does allow a number of tax deductible and detractable expenditures from taxable income.
Firstly, what is the difference between a tax deduction and a detractable expense?
- Deductible expenses (oneri deducibili)reduce your taxable income, meaning you pay tax on a lower income.
- Detractable expenses(oneri detraibili) give you a direct reduction in the tax you owe – usually a 19% tax credit on the value of item you are claiming, unless otherwise specified.
Both are valuable, and knowing the difference helps you understand how the savings work.
Healthcare expenses (19%)
Without a doubt the most common category is healthcare expenses (detractable at 19%)
What you can claim is as follows:
- Pharmacy receipts (scontrini parlanti) showing the name of the medicine and your tax code (codice fiscale)
- Doctor visits (GPs and specialists)
- Surgeries and hospital stays (private and public)
- Diagnostic tests, X-rays, and blood work
- Dental care (e.g., orthodontics, if medically necessary
- Physiotherapy and rehabilitation
- Medical devices (e.g., glasses, hearing aids, prosthetics)
There is a ‘franchigia’ (excess) related to these expenses, which means that it is only the accumulated expenses over €129.11 which are considered eligible.
If your total health expenses are below this amount then you cannot detract from tax. (Equally, you cannot claim this credit if the expense is covered by insurance.
To give an example……if my total expenses are €800 during the year, then the calculation is €800 – €129,11 = €670,89, on which I apply the 19% tax credit = €127,47 tax credit.
It may not seem much but a few years ago I had to have some urgent dental care which cost €10,000. It was not covered by insurance and so I had to pay myself. That year I had a tax credit of €1875,46. Every little helps!
When you go to the farmacia make sure you present your codice fiscale to the pharmacist and they will normally tell you whether it is an item that qualifies or not.
** FARMACIA AND HEALTH EXPENSES ARE NOW REGISTERED AUTOMATICALLY ON THE AGENZIA DELLE ENETRATE (TAX AUTHORITY) WEBSITE. YOU CAN ACCESS THE WEBSITE AND CHECK THEM YOURSELF, HOWEVER THERE ARE OCCASIONS WHEN THEY DON’T APPEAR SO MAKE SURE YOU KEEP YOUR RECEIPTS AND GIVE THEM TO YOUR COMMERCIALISTA / FISCALISTA (ACCOUNTANT) WHEN YOU FILE YOUR RETURNS **
Home renovations and energy efficiency (various rates from 36% to 50%)
This is by far and away the next biggest category for gaining tax credits.
The key incentives for home improvements are as follows: (at at 2026)
- Bonus Ristrutturazioni(Renovation Bonus) – 50% for general home upgrades
- Ecobonus– 50–65% for energy-saving improvements (e.g., insulation, windows, solar panels)
On your ‘Prima Casa’ (first home) you can claim a 50% tax credit up to a maximum spend of €96000, spread over 10 years.(at time of writing)
On your second home or property (other than Prima Casa) it is a 36% on a maxi spend of €96000 spread over 10 years.
(excluding boilers which burn fossil fuels.)
- Sismabonus – 50% on Prima Casa for 2025 then 36% for 2026/27 for work related to protection against sismic risks. 30% from 2026/27.
- Bonus mobili (e grande elettrodomestici) – tax credit of 50% on spend of up to €5000 on electrical appliances and furniture that are linked to renovations.
- Nuovo contributo per elettrodomestici ad alta efficienza – 30% up to €100 discount on electrical domestic appliance purchases, outside renovation works
- Green Bonus – 36% on garden and green area improvements.
Insurance premiums
This is a category which people often fail to utilise because there are some questions over whether foreign insurance premiums paid can be deducted in an Italian tax return.
For policies that qualify as Life insurance, accident (both max €530) and long-term care insurance (LTC) – (€1291)
They must qualify (even if issued outside Italy) under the following conditions:
- Policy must be with an EU or EEA-authorized insurer(i.e. the company must be licensed to operate in the EU/EEA under EU regulations).
- The policy must cover eligible risks: life, accidents, disability, or Long Term Care
- The beneficiary must be the taxpayer or close family(not a third party like a bank).
- The contract must not be speculative(e.g., pure investment policies are excluded unless they include real coverage of life or disability).
I enter my life policies issued in the UK years ago, before Brexit, and which cover me throughout the EU and were issued whilst the UK was still in the EU. I principally have life insurance contracts with Legal and General and provide cover across the EU. The other alternative is to take out Italian equivalent policies especially for things like health insurance. It’s worth getting a quote from one of the bigger insurance providers such as Generali (or Genertel, their online offering) Allianz, Zurich, Groupama, Unipol Sai, Banca Intesa, Reale etc
Other categories include:
Donations (19-30%)
donations to recognised NGO’s, religious institutions or universities.
Mortgage interest (19%)
You can deduct interest on mortgages for your first home (prima casa) up to a cap of €4,000 per year.
Education expenses (19%)
- Kindergarten through university tuition (both public and private, up to limits)
- School meals and after-school program
- University housing (if located outside the student’s home province)
Max annual deduction for private schools may vary by level and region, with a cap around €800 per child.
Rental deductions
If you rent your main home, you may claim a tax credit based on your income and contract type.
For example: Ordinary rental contracts (contratto 4+4), Student housing and transfers for work (if you’ve moved for employment reasons)
The credit varies depending on income, age, and contract type (e.g., up to €495.80 or more).
Family related deductions and credits
Dependent children and other family members, alimony and maintenance payments (deductible), Nursery/kindergarten costs (detraction up to €632 per child)
Disabled persons (LEGGE 104/1992 BENEFITS)
Special deductions and detractions for people with disabilities or their caregivers, including: 19% for adapted vehicles (with limits), full deduction of medical devices, assistance costs, etc.
Sport and Youth activities (19%)
Up to €210 per child under 18 for gym, swimming, dance classes, etc. Applies to recognized sports facilities and clubs.
Rendita catastale in Italy
By Gareth Horsfall
This article is published on: 21st April 2026
21.04.26
What is it and how does it affect your life in Italy?
I admit it. I have been confused for years about the rendita catastale. I have never been entirely sure about its role in the Italian economy or how it benefits the individual or the system as a whole. Until now. A recent deep dive into some economic analysis finally made the penny drop.
Which taxes are calculated using the ‘rendita catastale’?
IMU – (Imposta Municipale Propria) – The tax on second + properties and houses, which are considered luxury properties (Class A/1, A/8, A/9)
Imposta di registro, Ipotecaria e Catastale – the taxes when buying and selling property (not market value!)
Imposta di successione e donazione – the value of property is calculated using the rendita catastale for the purposes of inheritance tax. https://spectrum-ifa.com/how-can-i-save-on-inheritance-tax-in-italy
Why is it important?
The rendita catastale represents the amount of “theoretical rent” that a householder pays to him or herself as a measure of economic consumption. It is an imputed figure — a notional income — that reflects the benefit you receive simply by living in a property you own. In other words, if a householder owns their home outright, with no mortgage or debt, then that person is considered both a consumer and an investor of the invisible rent money they would have received had they been renting out a similar property. This money is assumed to be spent, reinvested, or otherwise circulated back into the economy.
Economists consider this a growing financial benefit that property owners enjoy from not having to pay rent. It is a silent contribution to economic activity, even though no cash actually changes hands. And in a country like Italy, where home ownership is culturally and economically significant, this imputed value plays a surprisingly large role.
During the financial crisis 2008/9, the Italian economy shrank dramatically. GDP fell, unemployment rose, and many sectors contracted sharply. Yet property, proportionately, made up more of the gross domestic product. The weighting of property in Italian GDP increased despite falling house prices and fewer transactions. That gives you an idea of how severe the declines were in other parts of the economy. Even when the market was weak, the imputed value of housing — the rendita catastale — continued to represent a stable and substantial component of national wealth.
This helps explain why successive governments treat property taxation so delicately. When the financial benefit from housing takes up a larger proportion of a property owner’s economic position, it becomes politically sensitive. It is no coincidence that governments have repeatedly adjusted or abolished taxes on the prima casa, recognising that Italian homeowners’ spending habits are more important to the domestic economy than the behaviour of foreign buyers. Italy’s economic engine is fuelled by its own residents, and the majority of them live in homes they own.
The Italian economy relies heavily on home ownership. Simply by residing in debt‑free housing, paying no rent, living in family homes, or paying below‑market rents, Italians contribute a significant share to national GDP through this imputed rental value. In a country where more than seventy percent of the population live in owned residences, this contribution is not only substantial but essential. It has grown over time, rising as a share of GDP, and continues to act as a stabilising force even when other sectors fluctuate.
Understanding the rendita catastale also helps explain why property taxation in Italy often feels disconnected from market reality. The cadastral values used for tax purposes are based on an old system that does not reflect current market prices. Yet these values continue to underpin calculations for IMU, taxes on buying and selling properties, inheritance tax, and other assessments. The system persists because it provides predictable revenue for the state and a predictable burden for homeowners, even if it bears little resemblance to actual property values.
There have been discussions for years about reforming the cadastral system, modernising valuations, and aligning them more closely with market prices. But such reforms would have enormous political and economic consequences. Updating cadastral values would instantly increase the taxable base for millions of households, and no government has been willing to take that risk. So the rendita catastale remains, outdated but deeply embedded, shaping everything from tax bills to inheritance planning.
What becomes clear is that the rendita catastale is not just a quirky Italian administrative concept. It is a structural pillar of the economy, a silent indicator of wealth, and a key reason why property taxation is handled with such caution. It reflects the reality that Italians’ relationship with property is not merely financial but cultural, generational, and deeply tied to economic stability.
And now that you finally understand it, you can see why it matters — not just to economists, but to anyone living, buying, inheriting, or planning their financial future in Italy, including us.
How can I save on inheritance tax in Italy?
By Gareth Horsfall
This article is published on: 21st April 2026
21.04.26
You may not be aware, but from an inheritance tax point of view, Italy is actually considered more like a fiscal paradise. After you have picked yourself up off the floor because I just called Italy a “fiscal paradise”, you might want to read on. If your estate, or part of it, is likely to be subject to Italian inheritance tax on your death, then the current rules may interest you.
Italian inheritance tax law dates back to the Napoleonic period.
It requires parents, on death, to leave a major proportion of their wealth to their children instead of just their spouse. This system of forced heirship still exists today and continues to shape how estates are distributed in Italy.
Italy’s inheritance tax works as follows:
If the estate is passed to your spouse or relatives in a direct line, such as children, they are required to pay 4% on the value of the inheritance that exceeds one million euro per beneficiary. Brothers and sisters must pay 6% with an allowance of one hundred thousand euro each. Other relatives must pay 6% or 8% depending on the degree of relationship, but without any allowance. Non‑relatives pay 8% with no allowance.
However, there is a term called ‘eredi legittimi’ meaning that only certain relatives have an absolute right to the share of your estate on your death. These are your children and, spouse. If you don’t leave any children then your parents and brothers and sisters have a legal right to a share in your estate and only in the event that there are none of the above, would your other relatives up to the 6th degree have a legal right to a percentage of your estate.
For foreigners (non- Italians) living in Italy at the time of death they have a right to nominate the law of their home country as a way to distribute the assets from your estate on death, instead of being forced to adopt the Italian forced succession rules. (If you are from the UK, this could create significant IHT planning opportunities). It mean you are taxable in your home country (depending on the IHT rules there) but simply means you may be able to distribute your assets according to a last will and testament, if that is your choice. One exception does apply, where you have spouse of children who are resident in Italy at the time of your death, and in this https://spectrum-ifa.com/rendita-catastale-in-italy/ case, they may be legally entitled to their fair share of your estate regardless of your will. If you are in any doubt it is always best to consult a legal professional to discuss the options.
Despite Italy having a large number of people who are subject to inheritance tax each year, the tax collection is relatively small. This is due to the high allowances and also the fact that succession for a property is based on the valore catastale, not the market value. The cadastral value is often significantly lower than the real value, which reduces the taxable amount.
There has been periodic political discussion about increasing inheritance tax in Italy, but as of 2026 no changes have been implemented. The current system remains one of the most generous in Europe, especially for spouses and children. However, this does not mean that planning is unnecessary. On the contrary, understanding how your assets are treated under Italian succession law can make a significant difference to what your heirs ultimately receive. The new UK Statutory Resident rules https://spectrum-ifa.com/new-uk-inheritance-tax-rules/ for inheritance tax mean that many more UK nationals living in Italy may be able to avoid UK and Italian IHT altogether with some clever planning.
As part of any inheritance tax or succession planning that you may undertake, you may want to look at ways in which you can hold assets in a more tax‑efficient manner. The polizza assicurativa — or life assurance bond — meets exactly that criteria. Any money that you hold in one of these tax‑efficient accounts is completely free from Italian inheritance tax and is kept outside of the estate when the value is calculated. This can be particularly useful for those who wish to leave assets to beneficiaries who are not in the direct line, or who wish to avoid the constraints of forced heirship within the limits permitted by law. It is also outside the Italian equivalent of probate (successione) and so will not get potentially tied up for any length of time in administration or legal affairs, potentially saving thousands in legal fees as well.
The not‑so‑good news is that if the majority of your estate is in your property, this cannot be placed inside the tax‑protective structure. However, any other invested or investable assets can be, generally from around €250,000 upwards. One of the great advantages is that there is no upper limit to contributions. You can protect a large part of your estate from Italian inheritance tax easily and with maximum flexibility to access the capital and any income from it during your lifetime.
Five lessons learned from the building bonus system in Italy
By Gareth Horsfall
This article is published on: 21st April 2026
21.04.26
If you are buying a house in Italy and are intending on benefitting from the system of detractions and deductions for the costs of building and renovating your property, then here are 5 things which we learned in our home restoration.
- All payments must be made by traceable means i.e bonifico (bank transfer) or credit card payment. No trace, no bonus!
- If paying by bonifico (bank transfer) then you need to pay by using the ‘bonifico per agevolazione fiscale’ option with your bank and NOT the ‘bonifico ordinario’ option. It asks for more information, such as the partitia IVA of the company / person you have worked with and this is needed for the bonus.
- If you employ single workmen working alone then you don’t need an authorisation (SCIA or CIA) from the local authority but if they are a ‘dita edilizia’ (this can include even 2 people working together as a construction company) then you may need to have a ‘piano di sicurezza’ from an architect who will need to draw that up and provide you with the necessary numbers/reference codes. No ‘piano di sicurezza’ no bonus! (Our’s cost around €1000!)
- Your workmen can apply for 10% IVA (VAT) on purchased items, but this is not necessarily a given. Our commercialista recommended that we signed a document ‘richiesta di applicazione dell’IVA ad aliquota ridotta’ for each workman / company so they would be authorised to apply for it as the materials would fall under the approved renovation works. Obviously, the Agenzia delle Entrate have the right to investigate these events in the future and so we did the maximum possible to avoid future problems. Documents should be kept for 10 years.
- Try and employ local workmen or businesses which operate in the area, because if you have problems in the future you want to be able to get hold of them quickly and easily.
Expansion of Italy’s 7% Pensioners’ Tax Regime
By Andrew Lawford
This article is published on: 14th April 2026
14.04.26
Many of you will recall that in 2019 Italy introduced a preferential tax regime for pensioners taking up residency in certain areas of Southern Italy.
Over the years there have been a few tweaks made to the rules, but these have generally had the effect of making it more accessible (unlike what has happened to some other tax regimes available for new residents).
Recently, a further change has been made to the regime by raising the population ceiling for eligible municipalities from 20,000 to 30,000 inhabitants, thereby opening up a broader range of towns across the eligible regions of Southern Italy.
What the regime offers
Qualifying individuals pay a flat 7% substitute tax on all foreign-source income, in place of ordinary progressive IRPEF rates. They are also exempt from the IVIE and IVAFE wealth taxes on foreign assets and are relieved of the foreign asset monitoring obligations that would otherwise apply in the RW schedule of their Italian tax return.
Who can qualify
The core requirements remain unchanged. The applicant must hold a pension paid by a foreign entity, must have been tax resident outside Italy for at least five consecutive tax years prior to the year in which the option takes effect, and must be moving from a country with which Italy has an administrative cooperation agreement in place. The regime covers only income considered to be produced abroad.
Geographically, the transfer must be to a municipality in Sicily, Calabria, Sardinia, Campania, Basilicata, Abruzzo, Molise or Puglia, or to certain municipalities affected by the 2009 or 2016 earthquakes. The population of the chosen municipality — assessed using ISTAT figures as at 1 January of the year before the option first applies — must not exceed the new 30,000 threshold.
Sound like it might be of interest to you? Feel free to get in touch for an initial consultation.
THE folder – are you prepared?
By Gareth Horsfall
This article is published on: 8th April 2026
08.04.26
Living in a foreign country is never easy, but have you thought how complicated it would be for your family if you die suddenly?
(Apologies for the subject matter around Easter, but if you are anything like me, I like to try and organise my annual tax paperwork for the commercialista around this time and so it is also a good moment to think about putting parts of your financial paperwork in order)
This article is one which I prepared years ago and have been sending out infrequently because on my travels and in the conversations I have, it is ever apparent that most people do not have all their financial paperwork in order in case anything happens to them.
Ensuring that your papers are in order in the event of your sudden death is incredibly important when living in another country. It will provide you with peace of mind that your loved ones will not have too much difficulty in administering your estate, and your family will be thankful that you did it for them.
The big problem is that we often have documents spread across multiple locations: the office, a house in another country, with family members and in that old box that no-one dares look in.
The purpose of this article is to outline a proven way of organizing your affairs to reduce stress on the family in the event of your death.
So what is ‘THE’ folder?
It is a single file (digital or physical) where you keep all of your important personal and financial information together. It allows easy access to these documents in the event that you are no longer around to deal with these things. It is really important to have it in place where one family member takes the lead on the family finances (as I do in our household). That includes paying bills, managing accounts and storing documents.
Is it worth the effort?
Well, I think it is worth the effort. I did mine a while ago and it gives me peace of mind more than anything else. I also told a few people about its location and left a note of who my wife should contact in the event of my death.. A time of loss can be stressful enough without having to try and piece the financial affairs together.
Preparing ‘THE’ folder is much more than avoiding stress as well. If you leave behind an administrative nightmare you could also delay access to the inheritors’ funds and potentially cost a small fortune in legal fees.
To give you an example of this, the UK Department of Work and Pensions estimate that there is currently more than £400 million sitting in unclaimed pension pots in the UK.
Approximately 1 in 7 Americans are estimated to have unclaimed property, such as forgotten bank accounts, insurance proceeds, or unclaimed inheritances
Which is best…..physical or digital?
This comes down to personal preference. It can be done by either creating an electronic file that survivors can access in the event of death. This file can then be stored on your main computer, in the cloud or on an external hard drive. Alternatively you can use a physical folder to keep all of the important information together.
For what it’s worth, I decided to do both when building mine because my wife prefers paper and so is happier with hard copies of everything. I prefer digital. I have also shared the digital folder with some trusted family members.
So what should go in ‘THE’ folder?
Birth, marriage and divorce
- Personal birth certificate
- Marriage licence
- Divorce papers
- Birth certificate/adoption papers for minor children
- Certificato di residenza (although it only has a 6 month validity, it might be worth while keeping a copy in there, where you are listed as being at your current address)
- Stato di Famiglia document
You can download free copies of your Italian documents, and copies with the ‘bollo’ (for €16) from the Italian national register website, here: https://www.anagrafenazionale.interno.it/ You will need to access it with your SPID or CIE.
Life insurance and retirement
- Life insurance policy documents (including beneficiary nomination forms)
- Details of any employer death in service benefits
- Personal pension documents
- Employer pension details
- Annuity documents
- Details of any entitlement to state pensions and in which country they derive.
Bank accounts
- List of bank accounts with account numbers, login details, passwords etc
- Details of any credit cards
- Details of safety deposit boxes
Assets
- Property, land and cemetery deeds
- Timeshare ownership
- Proof of loans made
- Vehicle ownership documents or rental agreements.
- Stock certificates, brokerage accounts, investment platform details, online investment account details
- Details of holdings of premium bonds, government bonds, investment bonds
- Partnership and corporate operating/ownership agreements (including offshore companies)
Liabilities
- Mortgage details
- Proof of debts owed
Details of gifts
- Dates and amounts/values (potentially helpful when calculating any inheritance tax liability)
Gifts which have been made many years ago can be hard to track down and so it’s important that when you make a gift to a family member or anyone else, that you keep a copy of the bank statement showing the amount paid, on what date and to whom.
If you made a larger gift, in Italy, then it will likely have been made through a notaio and so paperwork should be available. Keep these documents safe.
Income sources
- Make a listing of all your sources of income, especially ones that your family might not know too much about
- Employer details
- A copy of your most recent tax return or accounts.
Your historical Italian tax returns are all available to view and download on the Agenzia delle Entrate website under the section ‘Cassetto Fiscale’, which you can access with your SPID or CiE.
Monthly expenses
(so they can be maintained if necessary or cancelled if not. Essentially list the fixed costs which would need to continue after death)
- Utilities
- Insurance
- Rent/mortgage
- Loans
- Subscriptions/memberships
Email and social media account details
Essentials
- Will / testament + details of the legal firm that helped create it
- Living will details.
Did you know that you can write a ‘Testamento Biologico’ in Italy which will allow someone or more than one person to make medical decisions on your behalf (e.g life support and organ donation rather than day to day medical decisions) and this form can be lodged with your comune.
- Instruction letter/s
- Trust documents
- Burial/cremation wishes
Contact details
- List of names and contact numbers for: Financial adviser, doctor, lawyer/solicitor, accountant, insurance broker,
How often should ‘THE’ folder be reviewed?
Firstly, it is sensible to note the date that it was last reviewed so that anyone using it has an idea of how up-to-date the details are.
Going forward, reviewing the file on an annual basis should be sufficient.
Online passwords
I think it’s safe to say that this is the most problematic part of the whole process because we have so many passwords nowadays and need to change them all the time.
f you are not comfortable keeping these in your hard copy folder, consider using a password management program. A password manager allows you to save all account usernames and passwords in one place. They are then protected using one master key. There are a number of them available. Don’t forget to leave note of how to access the password manager though!
This may, however, be a step too far for you given the data breaches that seem to happen often and I appreciate that and if you are not comfortable in using such an app then its important to have a physical record some where that can be accessed in the event of your death.
PHONE PASSWORDS
This may seem like common sense but our lives now revolve around our phones and so ensuring that you leave details of not just your password to access the phone / PIN or line drawing shape, but also the PIN or access codes when the phone has been switched off AND your PUK code in the event that they get blocked out. If you use fingerprint authentication then you may also want to ensure that you leave open another access possibility, such as the PIN so that the phone can be opened without the need for your fingerprint, when that is no longer possible.
COMPUTER PASSWORDS
As per the above, do the same for your computer.
SPID and CIE
It’s probably worth a note about your SPID (Sistema Pubblico di identità digitale) and / or your CIE ( carta d’identità abilitata). These are digital identities accessed via apps and are now arguably some of the most important phone apps to access important financial and legal information held by the Italian state and therefore ensuring that you leave details of your passwords to access the apps could help your beneficiaries resolve estate issues without needing to engage or financial professionals to communicate with the various agencies on your behalf and at great cost.
And finally…
Get started…….don’t delay!!! It might seem like a huge task but getting started and putting some paperwork together is better than doing nothing. You can always go back to it at a later date and add more until it is finished. Don’t leave it until it’s too late!
Lastly, be sure to tell someone about it. There is little point going to the effort of creating such a folder if no one knows of its existence / where to find it.
Banking, Italian style
By Andrew Lawford
This article is published on: 5th March 2026
05.03.26
Missing billions, shady finance, body-snatchers and a murder investigation.
Is it a new Netflix series?
No, it’s banking, Italian style…
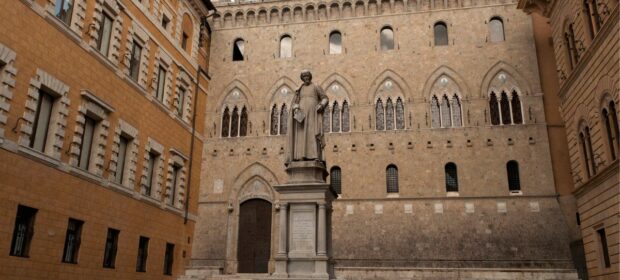
Recently we have had confirmation that the proposed acquisition of Mediobanca by Banca Monte dei Paschi di Siena (MPS) will be completed. This amounts to the apparently inexplicable phenomenon of one of Italy’s best banks being taken over by what is, arguably, the country’s worst. Read on for proof that truth is certainly stranger than fiction in the world of Italian banking.
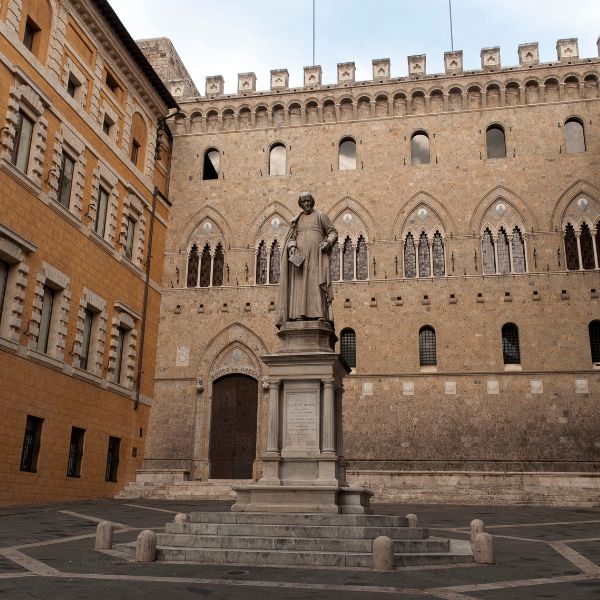
Let’s start at the beginning. Well, not exactly the beginning, because MPS was founded in 1472. We do, however, need to go back to 2008 and the disastrous aftermath of the takeover of Dutch bank ABN Amro.
Many will remember this moment as the beginning of the end for Royal Bank of Scotland, the lead acquirer, but there were in fact two other banks involved in the takeover (Santander and Fortis), which led to a curious side-show in the context of ABN Amro’s Italian assets.
Banca Antonveneta, at the time a moderately important domestic bank, had only been acquired by ABN Amro in 2005 as a result of the bankopoli scandal.
This is a whole other story involving market manipulation, a corrupt Governor of the Bank of Italy (the only one ever to have been forced to resign) and an investor group that nicknamed itself I furbetti del quartierino (the local hustlers) – but I digress. Antonveneta ended up in the hands of Spanish group Santander as part of the ABN Amro takeover and the asset was assigned a value of €6.6 billion, yet it was sold a few days later to MPS for €9 billion. The ridiculousness of this situation was summed up by one of the analysts present when the deal was announced. He posed this simple question to MPS management: “Did you even negotiate the price for five minutes?”
Of course, 2008 was no time to be doing an ambitious bank purchase and MPS soon found itself secretly counting the cost of the transaction. In order to save face, it organised a series of derivatives transactions designed to hide the reality of its deteriorating solvency position. It took a while for the truth to come out, but it was breathtaking when it did. The tone was set by the death of David Rossi, the bank’s Head of Communications, whose body was found in the alleyway beneath his office window in 2013.
Whilst officially ruled to have been a suicide, there was plenty of speculation that other, darker forces were involved. Of course, as is so often the case in financial frauds, lengthy court proceedings resulted in acquittals on criminal charges for all concerned.
Now, if the sordid story finished here with the collapse of MPS, the next chapter could not have been written, but of course politicians never want to let a good crisis go to waste and banks are always fun political toys.
Amongst the state’s interventions to prop up MPS, we can highlight the issuance of guaranteed bonds (Tremonti Bonds, named after the finance minister of the Berlusconi era, and then Monti Bonds, named after technocrat PM Mario Monti), subsequently repaid during rounds of capital increases that left the state on the hook for about €7 billion by the end of 2022. Subsequent equity sales brought in about €2.7 billion and left a remaining stake of about 12% in MPS. Following the takeover of Mediobanca, the state’s shareholding in the combined group has now been diluted to under 5%, currently worth somewhere over €1 billion. Not a great return on its investment so far.
But what of Mediobanca? Founded immediately following the end of WWII to finance the reconstruction of Italian industry, it was led by Enrico Cuccia, a legendary figure in Italian finance, until his death in 2000.
It is said that Cuccia played his cards so close to his chest that he would type any particularly important letters on his own typewriter so as not to allow the possibility of sensitive information leaking from his office.
To give you a taste of the kind of deal Cuccia was famous for: when FIAT was in grave financial difficulties in the ‘70s, Cuccia arranged for Gaddafi’s Libya to buy a 10% shareholding – it wasn’t a good look for FIAT’s Gianni Agnelli, who was rather happier in the company of friends like Henry Kissinger, but needs must. It’s not surprising that Cuccia was generally considered to be the one pulling the strings that made the stock market move – a point that was made rather morbidly when his corpse was stolen from its grave on Lake Maggiore and held to ransom. The demand, aside from cash, was that the Milan stock exchange index had to regain the level of 50,000 points (+35%!) by the end of the year. This didn’t happen, so evidently there were at least some limits to the man’s power.
The question of course is: why has this transaction occurred?
The following is from the official MPS press release following the acquisition:
The new Group structure is aimed at achieving strategic and profitability objectives and at fully achieving industrial synergies so to maximize value creation. This configuration is designed to enhance the distinctive expertise of Mediobanca and its professional resources, within a specialized operating model.
Right. This type of communication is technically known as a supercazzola in Italian. Don’t worry about the lack of subtitles – nothing he says makes any sense, which is sort of the point…
The sad reality is that Mediobanca, aside from being one of the crown jewels of Italian finance, sits atop another crown jewel: a 13% shareholding in the insurer Generali, a stake currently worth about €7 billion. It may well be that the dismemberment of Mediobanca and Generali and the distribution of value to its shareholders will be part of the Italian government’s strategy to promote nationalist capitalism. It’s hard to resist the temptation to say that Cuccia, who studiously avoided political interference, will be rolling in his grave (yes, his body was eventually returned to its rightful resting place).